How These Calculators Actually Work in Practice
Most people I talk to assume a Construction To Perm Loan Calculator is just a simple multiplication problem. It's not. The reality is messier, and the margin for error is where deals fall apart. I've seen borrowers and even some loan officers get tripped up by the same three issues over and over. The calculator itself is straightforward enough, but the inputs it needs aren't always obvious until you've been through a few projects. The core function takes your total construction budget, your down payment percentage, and your estimated interest rate, then runs the numbers through a two-phase model. Phase one covers the construction draw period, which is usually 6 to 12 months. During that window you're paying interest-only on the draws as they come out. Phase two kicks in once construction is certified complete and the loan converts to a standard amortizing mortgage. The calculator stitches those two periods together into a single projected payment number. Here's what most people miss. You don't just plug in the full project cost. You need to break it into draw schedules. Each draw represents a milestone—foundation, framing, roofing, final walkthrough—and the lender releases funds incrementally. If your calculator doesn't let you model draw timing, it's not giving you an accurate picture of your actual cash flow during construction. I ran into this specifically on a project in Tennessee where the borrower was using a generic online tool that assumed the entire loan amount was disbursed upfront. The monthly payment estimate was nearly double what they'd actually owe because the tool ignored the draw schedule entirely. The workaround was to manually calculate the interest-only portion for each draw period separately, then merge it with the amortized post-construction payment. Takes about ten minutes and saves you from showing up to closing with a payment number that doesn't match reality.
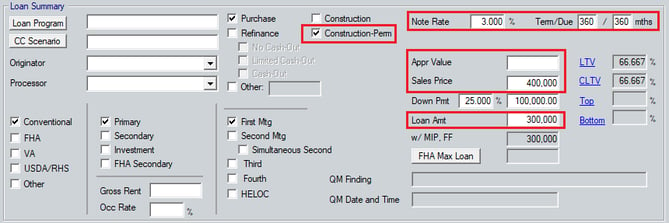
The fields you'll typically need to fill in are the total project cost, your down payment amount or percentage, the construction phase length in months, the interest rate during construction, and the permanent loan rate and term after conversion. Some calculators also let you input property tax and insurance estimates, which matters more than you might think. A $400,000 project in a high-tax county can add hundreds to your monthly PITI without you realizing it until the first statement lands.
Inputs That Actually Move the Needle
Interest rate differentials between the construction draw period and the permanent loan are where people get burned. Lenders often price the construction phase slightly higher, sometimes by 0.25 to 0.50 percent. That gap looks small on paper but compounds across the draw period. A 0.50 percent difference on a $300,000 construction loan over nine months adds roughly $1,125 in extra interest costs alone. Good calculators let you enter separate rates for each phase. Cheap ones force you to pick one rate and give you a false sense of accuracy. Another thing that gets glossed over is the conversion trigger. Not every construction-to-perm loan converts automatically. Some require a new appraisal, a Certificate of Occupancy, and full documentation review before the switch happens. If your timeline is tight and the conversion drags, you could be paying construction-phase interest for longer than planned. I had a client in Georgia whose conversion got delayed three weeks because the appraiser couldn't schedule the visit fast enough. The extra interest cost came to about $840, and nobody had budgeted for it because the calculator assumed a clean conversion at month six. Your down payment also plays a role you might not expect. Higher down payments reduce the construction loan balance, which lowers your interest-only payments during the build phase. But more importantly, a larger down payment improves your loan-to-value ratio at conversion, which can bump you into a better permanent rate tier. Lenders often have rate breakpoints at 80, 75, and 70 percent LTV. Jumping from 82 to 78 percent might not seem like much, but it can drop your permanent rate by a quarter point or more.
Get the Full Details

When This Tool Falls Short
Construction To Perm Loan Calculator tools have a real limitation that almost no one advertises. They assume your project stays on budget. The moment you hit a change order—a material upgrade, unexpected site conditions, permit delays that add months to the timeline—the entire calculation becomes useless. I've watched borrowers walk into closing with payment estimates that were 30 to 40 percent off because their project cost blew up by $50,000 and nobody updated the calculator. The tool doesn't know about your change orders. It only knows what you fed it. Another blind spot is the assumption that your permanent loan terms are locked in at the same time as your construction draw. In practice, rate locks expire. A 90-day lock might run out during construction, and when you re-lock, the rate could have moved. Some lenders offer rate lock extensions, but those usually come with a fee. The calculator won't account for that. You need to track your lock expiration date independently and have a plan for what happens if rates shift before conversion. If you're working with a smaller lender or a local credit union, the calculator might not match their exact pricing model. Regional lenders sometimes use different amortization methods or build in lender credits that standard calculators don't recognize. In those cases, ask your loan officer for a preliminary Good Faith Estimate before you trust any online tool. It takes five minutes and prevents the embarrassment of walking in with numbers that don't align with what they're actually quoting you.
The best approach is to treat a Construction To Perm Loan Calculator as a planning instrument, not a commitment device. It gives you a directional answer, not a binding one. Run it early to understand your ballpark. Run it again after you've locked your rates and received your final construction estimate. Run it a third time if anything changes during the build. Three passes will always be more accurate than one, and the extra time is negligible compared to the cost of showing up to closing unprepared.