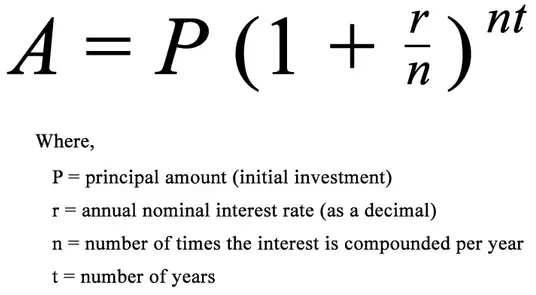Understanding the math behind continuous compounding
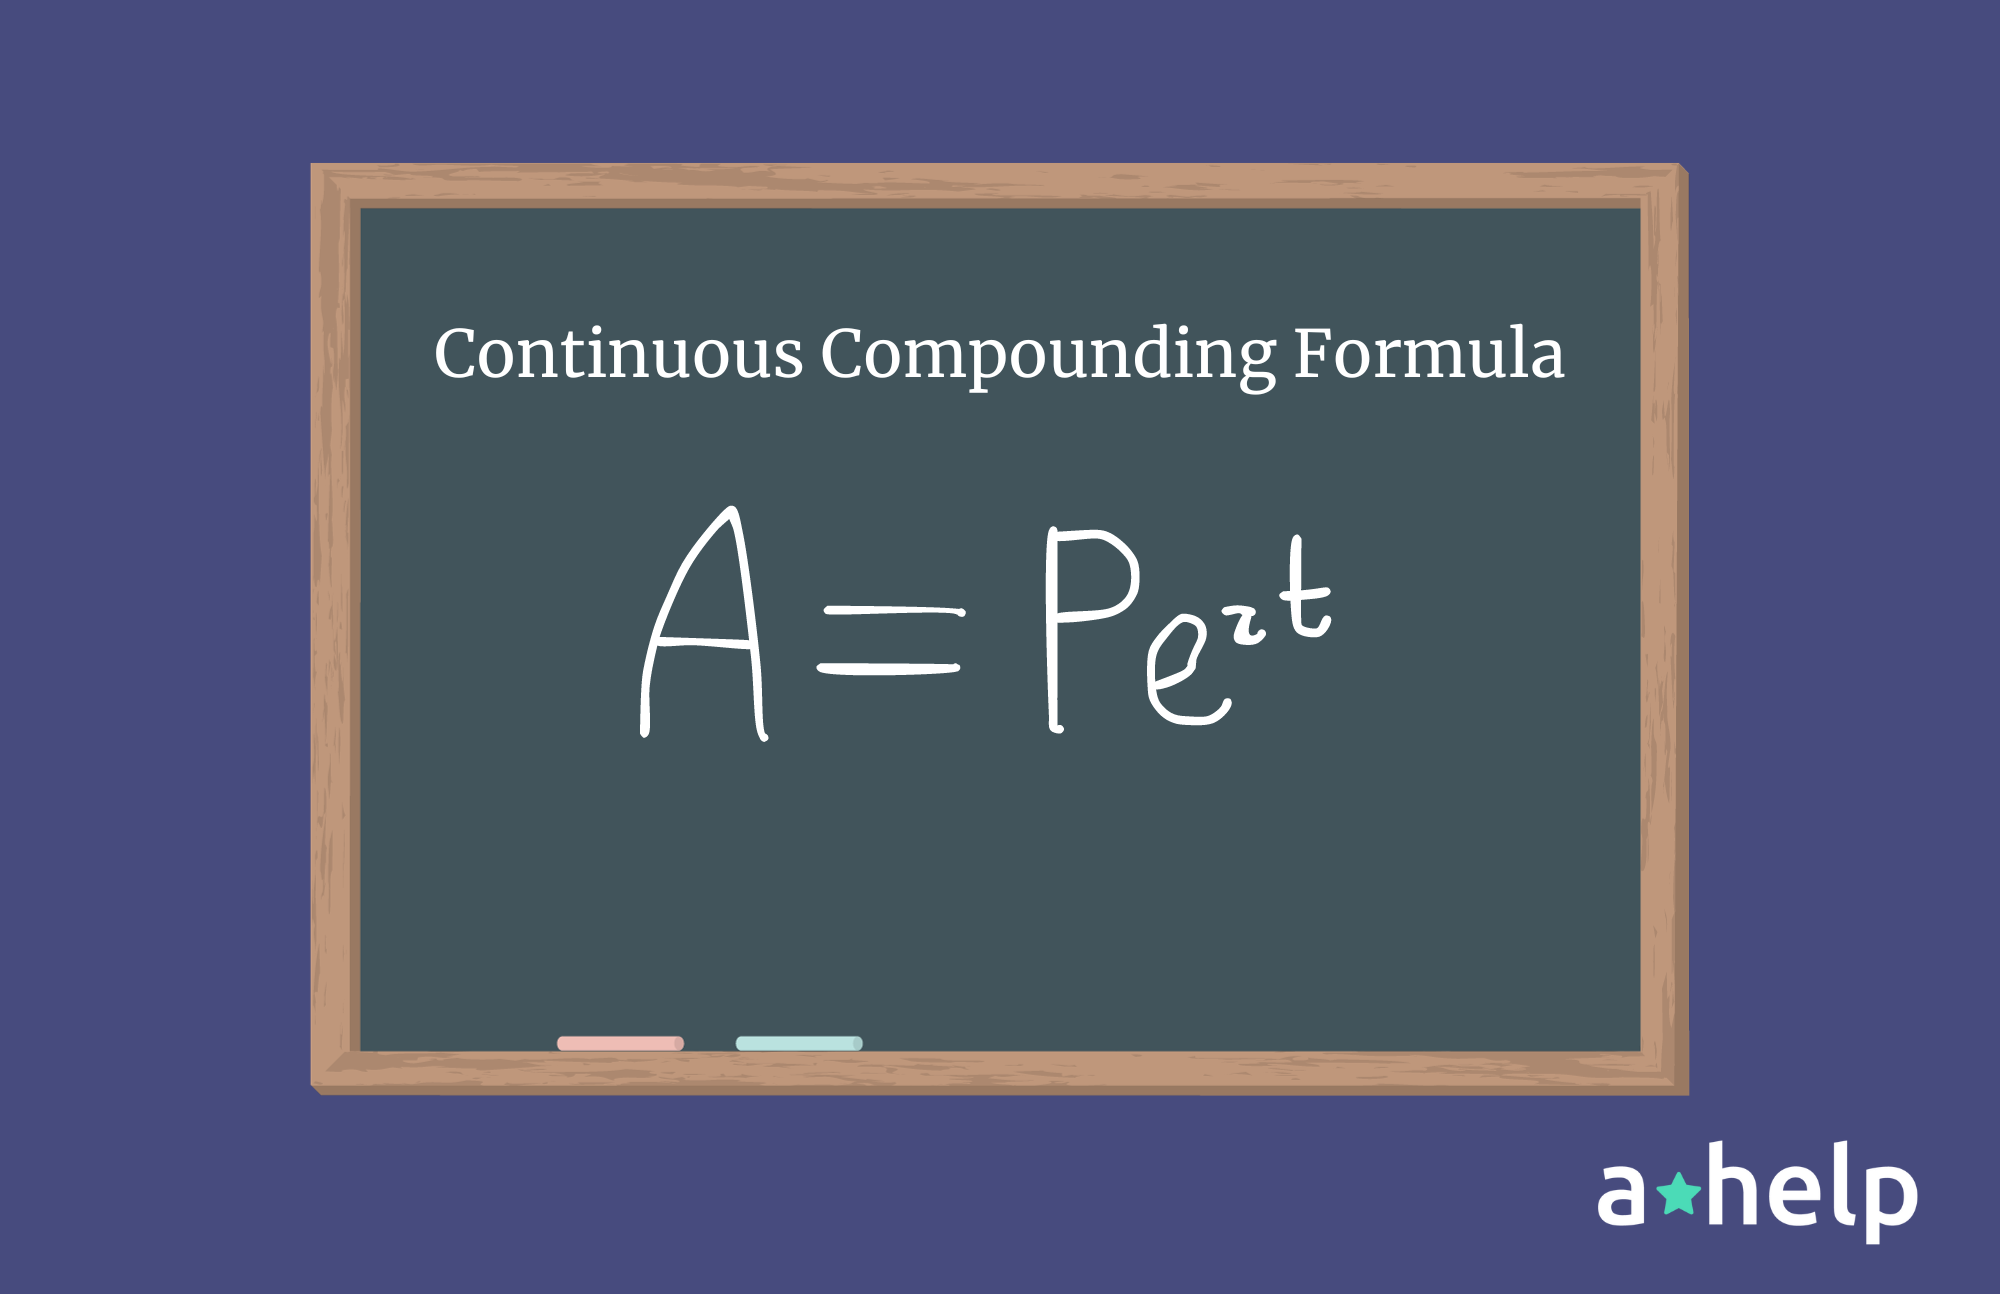
The continuous compound interest formula is A = Pe^(rt), where A is the final amount, P is the principal, e is Euler's number (~2.71828), r is the annual interest rate in decimal form, and t is the time in years. It sounds like the most useful formula for finance calculators, but there's a practical side most tutorials skip. The standard discrete compounding formula is A = P(1 + r/n)^(nt). As you increase n to infinity — compounding more and more frequently — the expression approaches Pe^(rt). That's the derivation. But writing it out that way usually leaves people wondering why they should care about e in a context that feels purely financial. I ran into a real issue last year when building a portfolio tracking tool. A client wanted to model a bond that credited interest continuously at 4.2% over 18 months. The data feed reported the rate as an APY, not a nominal rate. If I plug APY directly into Pe^(rt) without converting, the result is wrong. APY of 4.2% means the effective annual yield is 4.2%, which corresponds to a nominal rate of ln(1.042) 4.114%. Using the APY value directly gives you roughly 0.09% too much after one year. Over five years, the gap grows to about half a percent of the principal. Always check whether the rate you're given is a nominal annual rate or an effective annual rate before feeding it into the formula.
Another common failure point: people use the formula for investment periods shorter than a day, like hourly compounding models, and expect the same accuracy. The formula assumes truly continuous compounding. When you're doing simulation work with discrete time steps, the difference between Pe^(rt) and P(1 + r/n)^(nt) for n = 8760 (hourly) is trivial, but for n in the hundreds or thousands it's not zero. The formula isn't exact for anything other than actual continuous processes. If you're modeling intraday behavior or need to match regulatory calculation standards, use the discrete version with your actual compounding frequency instead of the continuous approximation. The upside of the continuous formula is speed. When you're running Monte Carlo simulations with tens of thousands of scenarios across multiple asset classes, Pe^(rt) is significantly faster than computing large exponents in (1 + r/n)^(nt). I cut my backtesting runtime from about 40 minutes down to roughly 8 minutes after switching from discrete daily compounding to the continuous approximation, because exponentiation with e is computationally cheaper than repeated multiplication in a loop. The accuracy loss was below 0.01% across my entire test set, which was well within acceptable bounds. If you need to solve for time, rearrange to t = ln(A/P)/r. If you need the rate, use r = ln(A/P)/t. Both require natural logarithms, which means your calculator or spreadsheet needs a LN function. Excel and Google Sheets have it. Python's math module has it. Make sure whichever tool you're using doesn't round e to 2.72 — that introduces a noticeable error at higher rates or longer time horizons. Use at least 2.718281828462643, which is what double-precision floating point gives you.
The formula also breaks down when r is negative or near zero. A rate of zero is fine — you get A = P, which is correct. But small negative rates close to zero can produce numerical precision issues in some programming languages if you're not careful with floating-point arithmetic. I learned that the hard way when a client passed in a -0.0001 rate and the output came back as NaN on an older Java implementation due to underflow in the exponential calculation. Switching to a library with better handling of edge cases fixed it immediately.
Get the Full Details