Working Through Cost Accounting Problems Without Losing Your Mind
Most people treat cost accounting like it's just math, and sure, it is math, but the math is the easy part. I spent years going through textbook exercises and watching students and junior accountants make the same mistakes over and over. The gap between understanding a concept on paper and actually solving a real exercise is usually about process discipline, not intelligence. Here is how you actually approach cost accounting exercises and solutions without spinning your wheels.
The Standard Exercise Framework
Every cost accounting problem, whether it's about job costing, process costing, ABC, or variance analysis, follows a roughly similar skeleton. You need to identify what type of costing method the question is using, pull out all the relevant data, set up your cost pools or accumulation sheets, calculate your overhead rates if they're involved, and then trace costs to the right unit or department. That's it. The devil is always in the details. I remember working through a process costing exercise for a manufacturing client a few years back. The problem looked straightforward on the surface — equivalent units, FIFO method, two processing departments. Simple enough. The catch was that the ending work in process inventory for Department 1 had a 40% completion rate for materials but only 15% for conversion costs. Most students automatically assume equal completion across cost categories. I caught it because the numbers didn't reconcile when I ran the first pass. If you skip the reconciliation step, you won't even know something is wrong until your journal entries don't balance and you're three hours into it.
Where to Find Quality Cost Accounting Exercises And Solutions
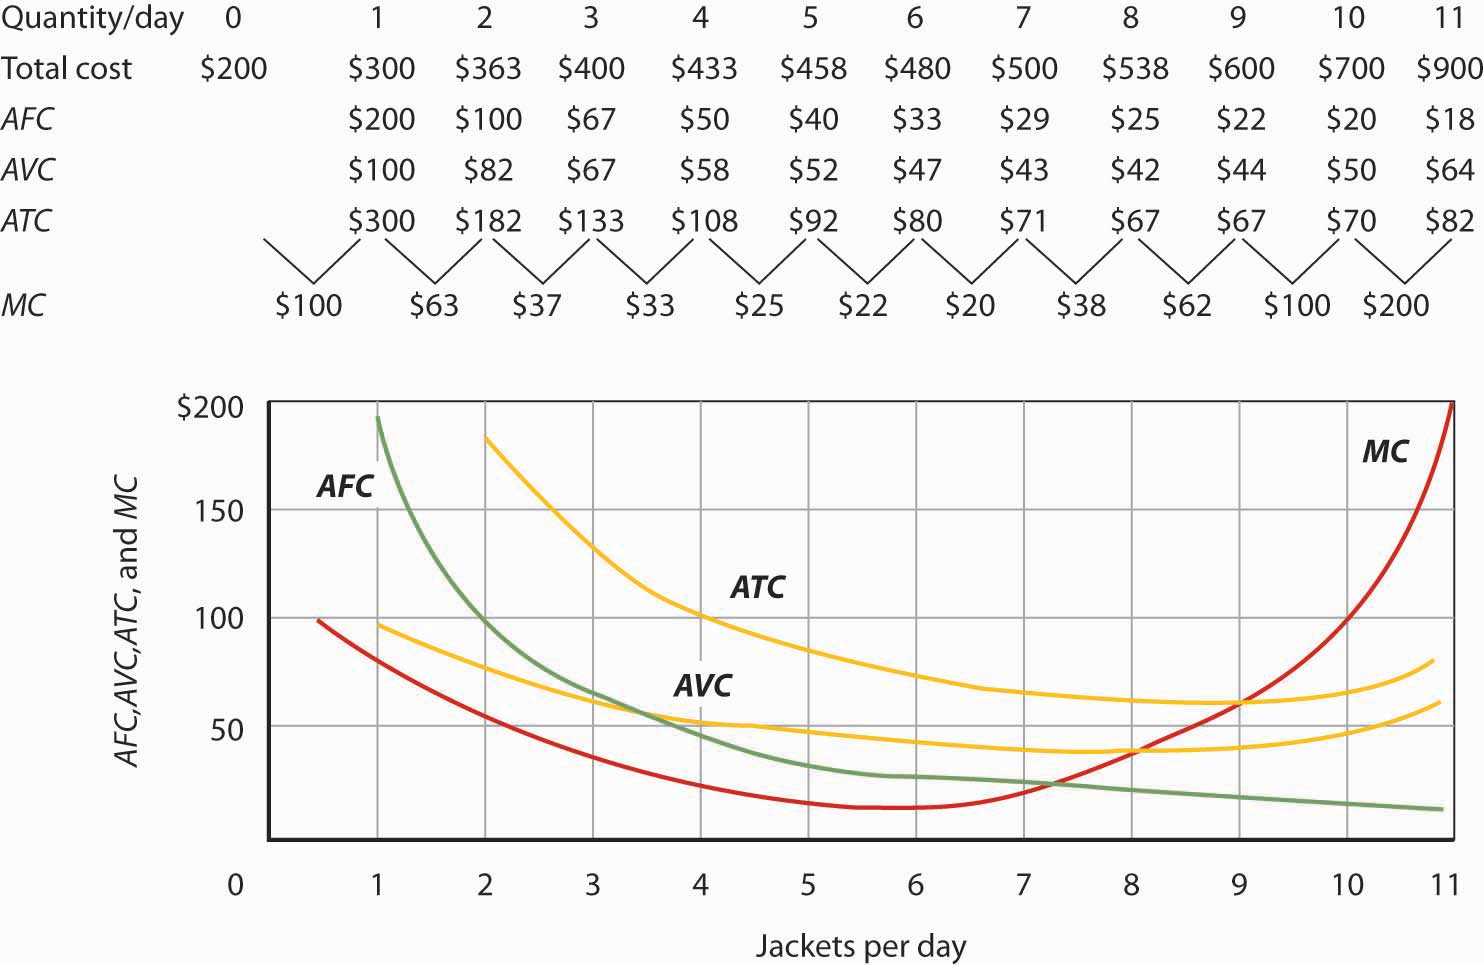
The best resources are generally your textbook's companion site, the CPA exam review materials, and university course repositories that post problem sets with worked solutions. OpenStax has a free managerial accounting section with solid practice problems. Beyond that, accounting firms sometimes publish case studies. The key is finding materials where the solution path is actually shown, not just the final answer. A lot of sketchy sites will give you the number but never explain the derivation, which is useless for learning. This is usually the first costing method students encounter. You're tracking costs to individual jobs or batches. The exercise will typically give you direct materials requisitioned, direct labor hours or dollars, and a predetermined overhead rate. Your job is to build the job cost sheet, apply overhead, and determine the cost per unit or the total job cost. The standard predetermined overhead rate formula is estimated total manufacturing overhead divided by estimated total allocation base. Common allocation bases are direct labor hours, machine hours, or direct labor dollars. Here is a practical example. Suppose you estimate $480,000 in overhead for the year and expect 24,000 direct labor hours. Your rate is $20 per direct labor hour. If Job 101 used 150 direct labor hours, the applied overhead is $3,000. Add direct materials of $4,500 and direct labor of $2,250, and your total job cost is $9,750.
Get the Full Details
The trap here is underapplied versus overapplied overhead. Exercises often throw in a twist where actual overhead differs from applied overhead. You need to close that variance out, usually to cost of goods sold unless the amount is material, in which case you prorate it between work in process, finished goods, and cost of goods sold. I've seen people miss that materiality test and just dump everything to COGS when the problem explicitly wanted proration. That cost them points on exams and on real reports.
Process Costing and Equivalent Units
Process costing comes into play when you're dealing with continuous production, like chemicals, food processing, or pharmaceuticals. The exercise will give you units started, units completed, units in ending work in process, and completion percentages for materials and conversion. You calculate equivalent units of production, which represent the work done expressed in fully completed units. There are two main methods: weighted average and FIFO. Weighted average blends beginning inventory costs with current period costs. FIFO keeps them separate and assumes the first units in are the first units out. Weighted average is simpler and more commonly used in exercises. The formula for equivalent units under weighted average is straightforward: units completed and transferred out plus the equivalent units in ending work in process. For materials, if ending WIP is 80% complete and there are 5,000 units, that's 4,000 equivalent units for materials. For conversion, if it's 60% complete, that's 3,000 equivalent units. One thing that trips people up is when materials are added at different points in the process. If materials are added at the start of process, all units in that department get 100% material cost, regardless of completion. If materials are added at the midpoint, then partially completed units might only get 50% material cost. Read the problem carefully. I had an exercise once where materials were added at 75% completion and conversion costs were added evenly throughout. Half the class missed that detail and calculated equivalent units wrong for materials.
Activity-Based Costing Exercises
ABC is a big topic and the exercises can get involved. You're assigning overhead costs to activities, then assigning activity costs to products based on their consumption of those activities. The steps are: identify activities, assign overhead costs to each activity to create cost pools, identify cost drivers, calculate activity rates, and assign costs to products. Let me walk through a realistic setup. You have three activity pools: machining at $200,000 driven by machine hours, setup at $80,000 driven by setup hours, and product design at $120,000 driven by design hours. Total machine hours are 10,000, setup hours are 400, and design hours are 600. Your activity rates are $20 per machine hour, $200 per setup hour, and $200 per design hour. Product A uses 3,000 machine hours, 100 setup hours, and 200 design hours. Product A's allocated overhead is $60,000 plus $20,000 plus $40,000, totaling $120,000. Product B gets the remainder. The counter-intuitive insight here is that ABC often reveals that high-volume products are subsidizing low-volume products under traditional costing. A product that runs many small batches will look cheaper than it actually is under a single plantwide rate. ABC corrects that. But it's not a free lunch. Setting up an ABC system requires detailed data collection and ongoing tracking. For small companies with simple operations, the benefit may not justify the cost. I worked with a mid-sized manufacturer that tried ABC and found that the overhead allocation changes barely moved the needle on pricing decisions. Their operations were too simple for the complexity to matter. Traditional costing was actually sufficient.
Standard Costing and Variance Analysis
Standard costing exercises revolve around comparing actual costs to predetermined standards and analyzing the differences. The variances you'll encounter include material price variance, material quantity variance, labor rate variance, labor efficiency variance, variable overhead spending variance, variable overhead efficiency variance, fixed overhead budget variance, and fixed overhead volume variance. Material price variance is the difference between actual price and standard price multiplied by actual quantity purchased. Material quantity variance is the difference between actual quantity used and standard quantity allowed multiplied by the standard price. Labor rate variance is the difference between actual rate and standard rate multiplied by actual hours. Labor efficiency variance is the difference between actual hours and standard hours allowed multiplied by the standard rate. Here's a concrete example. Standard material cost is $5 per pound. You purchase 10,000 pounds at $5.20 per pound and use 9,500 pounds to produce goods that should have used 9,000 pounds at standard. Material price variance is ($5.20 minus $5.00) times 10,000 equals $2,000 unfavorable. Material quantity variance is (9,500 minus 9,000) times $5 equals $2,500 unfavorable. The purchasing manager would own the price variance and the production manager would own the quantity variance. This separation of responsibility is important and often tested.
Fixed overhead volume variance is where most people get confused. It measures the difference between budgeted fixed overhead and applied fixed overhead, which is based on standard hours allowed times the fixed overhead rate. A unfavorable volume variance means you produced less than the denominator level used to calculate the rate. That's not necessarily bad — it might mean you reduced inventory or had lower demand. But it does mean your fixed cost per unit is higher than planned. I've seen controllers panic over unfavorable volume variances when the real issue was a deliberate slowdown to build inventory for a seasonal spike. Context matters more than the raw number.
Common Pitfalls in Cost Accounting Exercises
Read the question twice. Not as a ritual, but because people miss critical details on the first pass. Is the overhead rate based on direct labor hours or machine hours? Are materials added at the beginning or end of the process? Is the question asking for variances or just total costs? These seem obvious but the errors pile up fast. Watch your units. Mixing up units completed with units in ending work in process is extremely common. Always draw a physical flow schedule before you calculate equivalent units. It takes thirty seconds and prevents most errors. Keep track of favorable and unfavorable. A variance isn't just a number. Positive is favorable, negative is unfavorable, but only if you define your formula consistently. Some textbooks use (actual minus standard) and some use (standard minus actual). Pick one and stick with it. Inconsistent signs will make your reconciliation impossible.
Reconcile your totals. Total costs to account for must equal total costs accounted for. If they don't, you made a mistake somewhere. Run the check before you move on. It saves you from building errors on top of errors.
Abc Costing Vs Traditional Costing In Practice
This shows up in exercises constantly and also in the real world. Traditional costing uses one or a few allocation bases, usually direct labor or machine hours. ABC uses multiple cost drivers tied to specific activities. The exercise will often ask you to compare the two and explain the differences. The answer is that ABC provides more accurate product costs when overhead is a large portion of total cost and when products differ significantly in their consumption of overhead activities. Traditional costing works fine when overhead is small relative to direct costs or when all products consume overhead roughly proportionally to the allocation base. I ran into a situation where a company was using traditional costing with direct labor hours as the sole base. Their product line included both labor-intensive custom work and automated high-volume production. Under traditional costing, the automated products were being allocated massive overhead because they used minimal direct labor, which made them look wildly unprofitable. The company was about to drop a product line that was actually contributing positively. ABC revealed the truth, and they kept the product. This isn't a hypothetical case. It happened to me at a mid-size industrial parts manufacturer in 2019.
How to Practice Effectively
Don't just read through solutions. Work the problem yourself first, even if you get it wrong. The struggle is where the learning happens. Check your work against the solution, identify where you diverged, and understand why. Then redo the problem from scratch without looking at anything. If you can solve it cleanly on the second attempt, you actually know it. Time yourself. Exam conditions add pressure that changes how you approach problems. Give yourself twenty minutes for a standard job costing exercise, thirty for a process costing one with equivalent units, and fifteen for a variance analysis set. If you're running long, you don't have the process dialed in yet. Group similar problems together. Do five job costing problems in a row, then five process costing problems. Pattern recognition helps. You'll start seeing the structure faster and your speed will improve. Most students spend too much time jumping between different costing methods without building fluency in any single one.
Use spreadsheet software to organize your data. I stopped doing cost accounting exercises by hand years ago. Spreadsheets let you lay out your cost flows visually, set up automatic calculations, and spot errors immediately when a cell doesn't tie out. It mirrors how the work actually gets done in practice.
Exam Tips for Cost Accounting Sections
On the CPA exam and most college exams, the calculations are manageable. The challenge is the volume and the time pressure. You'll see questions on standard costing, ABC, joint costs, transfer pricing, and budgeting all in one sitting. Know the formulas cold so you don't waste mental energy deriving them during the exam. Write down the formula before you plug in numbers. It keeps you organized and gives you a reference if you second-guess yourself. For variance analysis, a clean table showing actual, standard, and the difference for each component is worth more than a paragraph of text. Examiners look for clear presentation. Don't get stuck on a hard problem and burn ten minutes on it. Flag it, move on, and come back if you have time. Cost accounting sections often have one or two deliberately tricky questions designed to waste your time. Recognize the trap and skip past it.
For those actively searching for structured practice material, I'd recommend starting with the CMA review materials from Gleim or Wiley. Their cost accounting sections have well-organized exercises with detailed solutions that walk through each step. The free resources from university accounting departments are also solid. Just make sure the solutions are complete enough that you can learn from them rather than just copying answers.