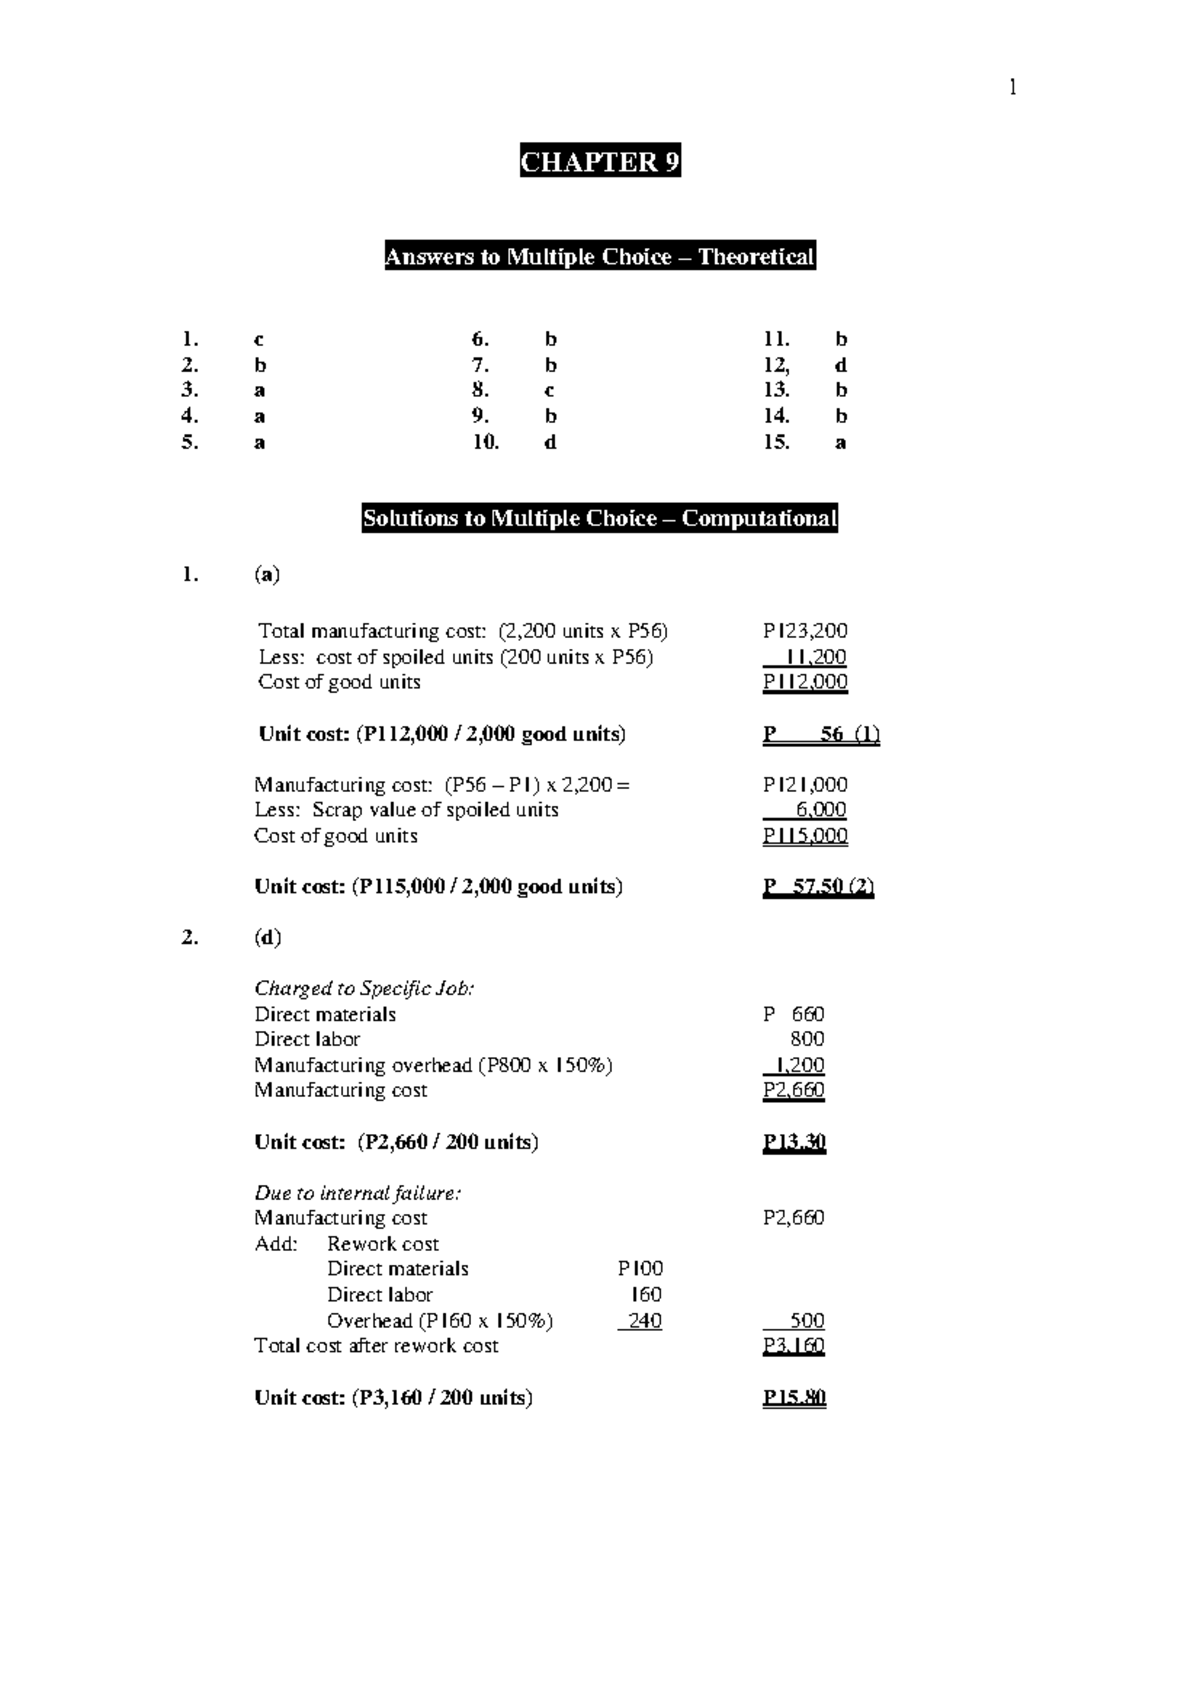
Understanding Activity-Based Costing Through Cost Accounting Solutions Chapter 9
Most students struggle with Activity-Based Costing because they treat it like a memorization exercise. It isn't. The chapter walks you through how to assign overhead costs using multiple cost drivers instead of a single plantwide rate. The basic logic is straightforward, but the mechanics trip people up when they hit real problems. The two-stage allocation process is the core concept here. First you identify the activities that drive costs—setup, inspection, machine processing, material handling, that sort of thing. You collect the total cost for each activity and divide by its cost driver to get an activity rate. Then you assign those costs to products based on how much of each activity the product actually consumes. That is stage two.
Working Through Cost Accounting Solutions Chapter 9 Step by Step
I remember working on a textbook problem where a company produced two products: a high-volume simple part and a low-volume custom part. The traditional system assigned overhead based on direct labor hours. Under ABC, the custom part was being massively undercosted. It required far more setups and inspections per unit, but those activities weren't showing up in the overhead allocation at all. The fix came down to identifying the right cost pools. Setup costs, inspection costs, machine maintenance, and material movements. Each one got its own rate. The custom part used two setups per batch and one inspection per unit. The simple part needed maybe one setup per hundred units. The ABC system revealed that the custom part was eating about 60 percent of total overhead despite being only 15 percent of volume. That number doesn't show up anywhere in a traditional allocation. When you work through the problems in the textbook solutions, pay attention to the worksheet format they use. They lay out cost pools in columns with driver quantities underneath. It looks tedious but it prevents the common error of mixing up driver units with dollar amounts. I've seen students divide total overhead by total machine hours when they should have been dividing setup costs by setup hours. The answer looks plausible until you trace it back.
One counter-intuitive point that textbooks don't emphasize enough: not every activity deserves its own cost pool. When an activity's cost represents less than five percent of total overhead, the effort to track it separately usually isn't worth the accuracy gain. I once worked with a company that tried to create fifteen cost pools for a facility with moderate complexity. By the time we pruned it down to eight meaningful pools, the product cost estimates barely changed. The detail was noise, not signal. Another nuance beginners miss is the difference between unit-level, batch-level, product-level, and facility-level activities. Unit-level varies with each unit produced. Batch-level varies with each batch regardless of size. Product-level supports a specific product line. Facility-level supports the operation as a whole and typically shouldn't be allocated to products under ABC. If your textbook problem includes facility-level costs in your allocation base, the product costs will be distorted. Skip those costs and allocate only the first three categories. The practical limitation of ABC is that it requires data most companies don't readily have. You need to know how many setups each product run requires, how many inspection hours per batch, how much material handling time per order. Gathering that data can take weeks and often requires input from shop floor supervisors who already consider their time valuable. Many organizations abandon the method after six months because the data collection burden becomes unsustainable. If your problem set asks you to design an ABC system for a small manufacturer, note in your answer that ongoing data tracking would be a significant operational cost. That observation separates students who understand the method from students who just completed the calculation.
Get the Full Details
For companies looking for a middle ground, there is Time-Driven Activity-Based Costing, which replaces detailed time studies with average processing times per transaction type. It produces similar results with a fraction of the data collection effort. Most modern textbooks mention this variant in an later chapter or appendix. If you are stuck on a particular problem from Cost Accounting Solutions Chapter 9, the most useful approach is to redraw the problem on paper using the four-category activity structure. Label each cost with whether it is unit-level, batch-level, product-level, or facility-level. Then verify that your driver quantities match the activity type. That single check catches most errors before you run the final calculation.