What a Cost Analysis Template Actually Does
A cost analysis template is a structured document that organizes financial data so you can see where money is going and which projects are actually profitable. It sounds simple, but the way you structure it determines whether you get useful answers or just a lot of columns you never look at again. The template typically has sections for fixed costs, variable costs, labor, materials, overhead allocation, and revenue comparison. Some people build theirs in Excel with five-minute setups. Others spend weeks on elaborate models that break the first time actual data hits them. I've done both and the shorter one usually wins unless you have genuinely complex multi-project operations.
How I Built a Cost Analysis Template That Actually Worked
Start with the structure, not the formulas. I learned this the hard way when a client spent three weeks perfecting conditional formatting and conditional currency conversions before we'd even defined what a cost category meant in their business. The template ended up being beautiful and completely useless. The columns I use are straightforward: cost item, category (direct, indirect, or overhead), amount, allocation method, and notes. That's it. The notes column is where most people fail because they skip it. Without notes, you cannot audit the template later when someone asks why a line item changed by forty percent. For allocation methods, I recommend picking one and sticking with it. Activity-based allocation is more accurate but requires data most teams do not track. Straight-line allocation is easier and usually good enough. The choice matters less than consistency, because switching methods mid-year makes comparison impossible.
One specific problem I encountered involved a manufacturing client who tried to include all shared equipment depreciation in the overhead pool. This inflated their per-unit costs by roughly twenty-two percent compared to competitors who allocated depreciation directly to the products using that equipment. The workaround was creating a separate "shared resource" category within the Cost Analysis Template that applied a usage multiplier based on machine hours rather than a flat percentage split. This took one afternoon to implement and immediately improved their pricing competitiveness without reducing internal margin visibility.
Get the Full Details
Common Mistakes That Break Cost Analysis Templates
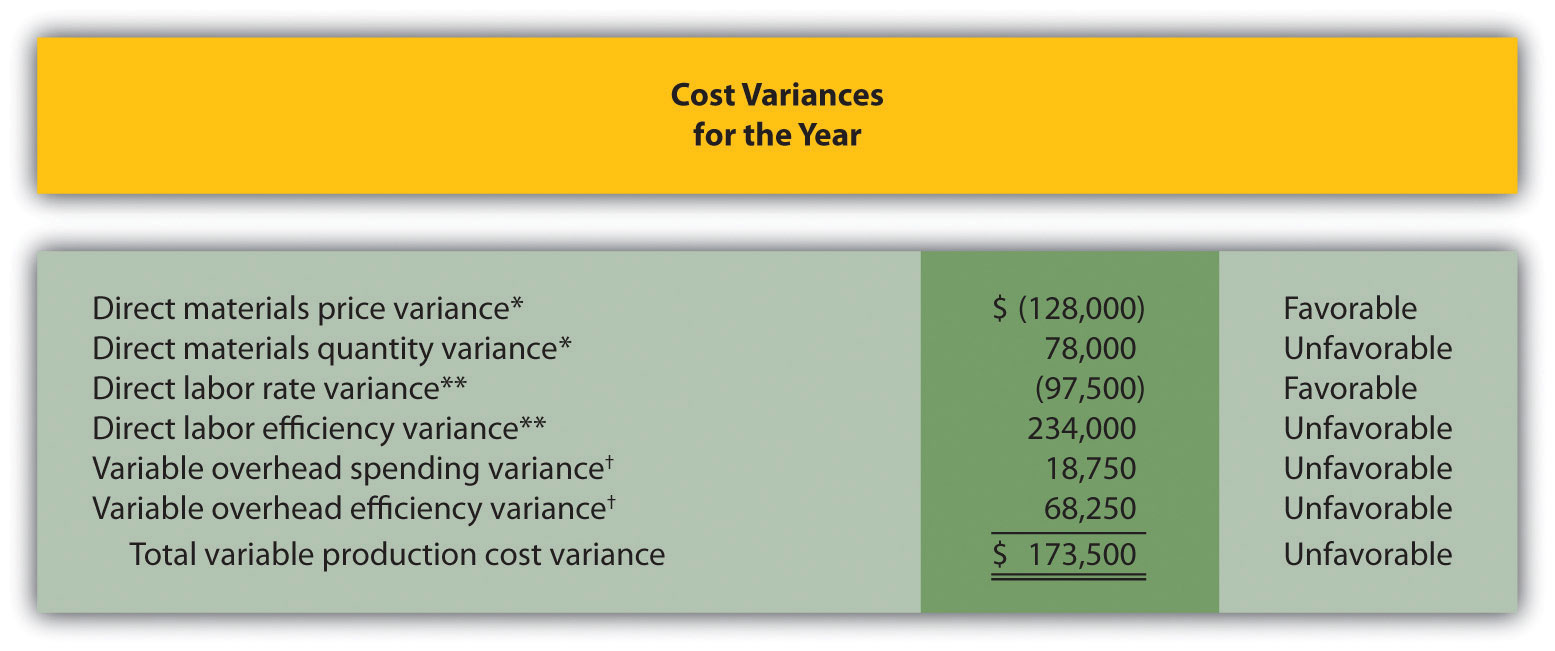
The biggest mistake is treating the template as a historical record instead of a decision-making tool. Most templates I review capture what happened last quarter but do not help answer whether the next quarter should continue the same spending pattern. That is a documentation exercise, not an analysis. Another frequent issue is cost categorization inconsistency. Different departments will classify the same expense differently, which makes aggregation unreliable. A marketing team might call a software license a "tool cost" while finance classifies it as "overhead." Neither is wrong, but combining them without a standard produces numbers that do not reflect reality. Templates that only model static cost assumptions fail when actual conditions change. I recommend building three cost tiers into your template: baseline, aggressive, and worst-case. This usually takes an extra thirty minutes during setup but prevents panic when a supplier increases prices by fifteen percent and you already committed to fixed bids.
Some people try to capture every possible cost variation in a single template. This creates maintenance overhead that most teams abandon after six months. A simpler template with quarterly review cycles produces better results than a perfect monthly model nobody updates. The goal is actionable insight, not comprehensive accounting.
Advanced Nuances Most People Miss With Cost Analysis Template
Here is something counter-intuitive: including every minor expense in your cost analysis often reduces accuracy rather than improving it. Small items create noise that masks the larger cost drivers. I recommend setting a materiality threshold, typically five percent of total costs, and routing anything below that into an "other" bucket with a comment field. This usually cuts template maintenance time in half while preserving visibility into the costs that actually matter. Most cost analysis templates treat costs as independent variables, but in practice they interact. A twenty percent increase in raw materials might trigger a ten percent increase in quality control labor. Your template should have a section for cost correlations, even if you estimate them roughly. This prevents the common error of modeling each cost driver in isolation and arriving at an aggregate figure that looks precise but is systematically wrong. Another nuance involves timing mismatches between when costs are incurred and when they are recognized. Accrual accounting creates these gaps deliberately, but most simple templates ignore them. If your template tracks cash outflow rather than expense recognition, adjust your revenue comparison accordingly. Mixing the two approaches produces margin figures that look healthy while actual cash position deteriorates.
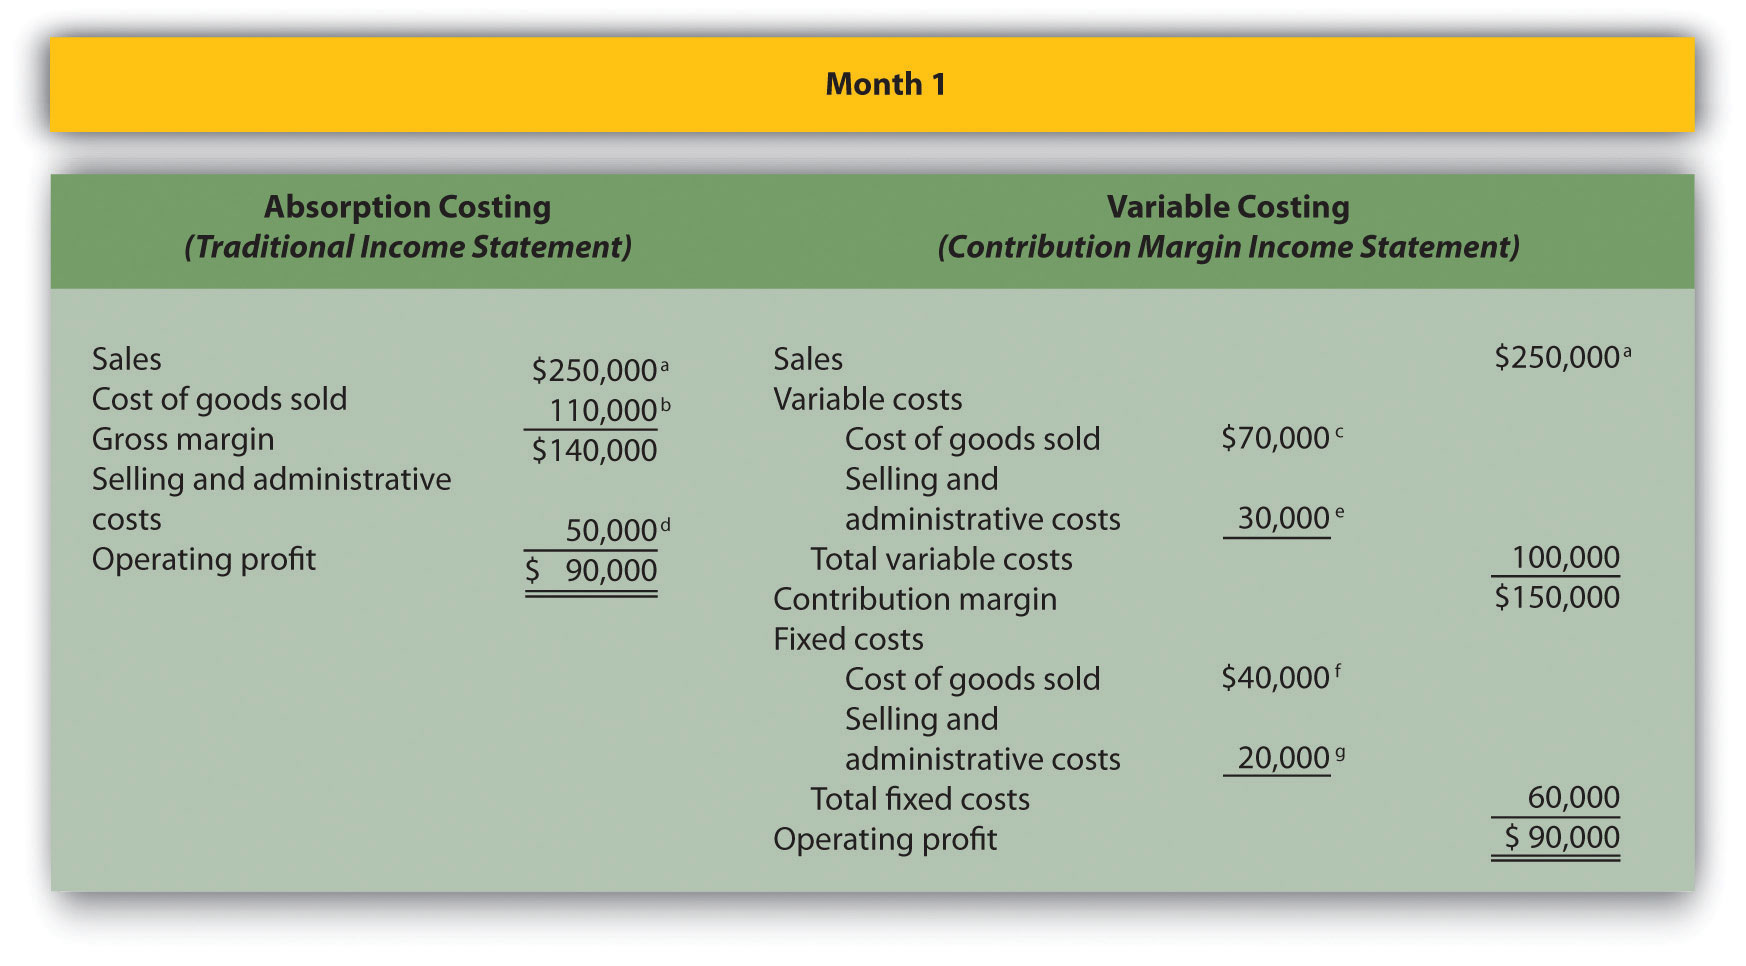
I also recommend building a sensitivity table into the template, showing how margins change when individual cost drivers shift by ten or twenty percent. This usually reveals which costs are leverage points and which are noise. In my experience, teams often obsess over categories that have minimal margin impact while ignoring the one or two drivers that actually determine profitability.
When a Cost Analysis Template Is Not the Right Tool
There are scenarios where this approach fails completely. If your costs are highly unpredictable, such as in early-stage research or creative development, a structured template may impose false precision on genuinely uncertain spending. In those cases, a simpler tracking method with regular review cycles often works better than an elaborate Cost Analysis Template that nobody trusts. Another limitation involves data quality. The template is only as reliable as the input data. If your accounting system does not capture costs at the project or product level, you will spend more time cleaning data than analyzing it. Consider whether your existing systems can support the template before investing weeks in custom development. Templates also assume stable cost structures. If your business model changes frequently, such as transitioning from project-based to subscription revenue, the template may require constant restructuring. In these situations, a more flexible approach like rolling budget variance analysis might adapt better without losing the cost visibility you need.
The most honest assessment is that a cost analysis template typically reduces decision-making time from several hours to about twenty minutes per review cycle, but only if the structure matches your actual operations. A mismatched template creates additional work without generating better insights. Test the template on three months of historical data before committing to it as your standard process. If you need a starting point, the essential structure is minimal: cost categories, allocation methods, and comparison metrics. Everything else is refinement. I have seen teams spend more time debating whether to use dropdown menus than actually analyzing their cost data. The template should serve the analysis, not the other way around.