Getting Started With Cost Behavior Analysis
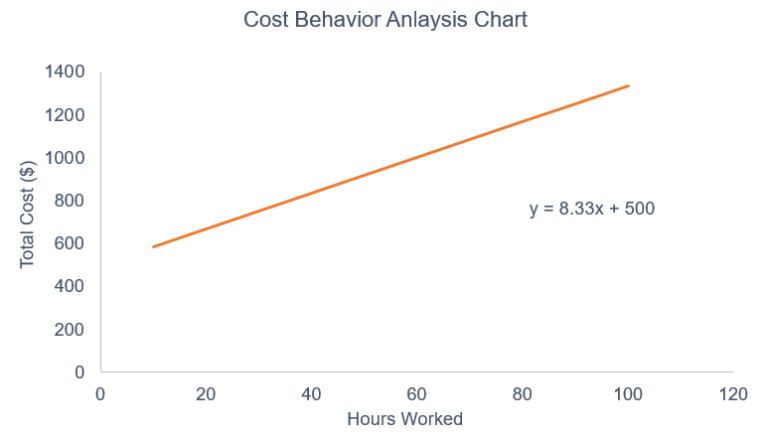
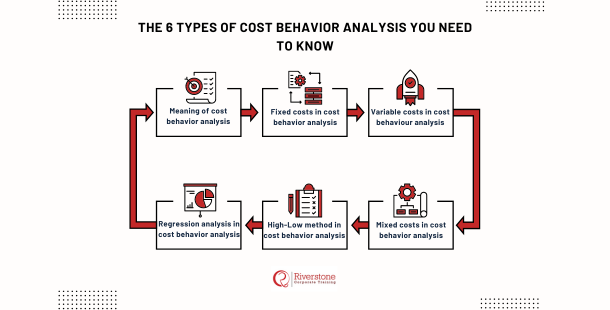
Most people approaching this for the first time will run straight into a regression analysis tool, throw their data at it, and call it a day. That's not wrong per se, but you're going to miss the parts that actually matter in practice. Cost behavior analysis focuses on how costs change when your activity level changes. That's the textbook definition, and it's barely useful until you've seen what goes wrong with it. The core job here is separating costs into buckets: variable, fixed, and mixed. Variable costs move in direct proportion to output. Fixed costs sit there doing nothing regardless of what happens. Mixed costs do a bit of both. That's straightforward until you're looking at real data where nothing lines up neatly. I spent probably six months dealing with a manufacturing client who had a cost that looked fixed on paper but was actually stepping fixed. Every time they added a shift, they needed another supervisor, and that supervisor came with a salary plus benefits that didn't vary hour to hour. The regression said "fixed." The reality said "step." If you don't catch that, your cost predictions are going to be off by a noticeable margin every time they change shift patterns. The workaround was basically to map the headcount schedule against the supervisor costs and treat it as a step function rather than a straight line. Took about an hour once you knew what to look for.
The Practical Side Of Classifying Costs
Let's talk about the actual process. You pick a cost pool first. It could be something like electricity, maintenance, or indirect labor. Then you find your activity base - machine hours, units produced, direct labor hours, whatever drives that cost in your operation. You plot the data points on a scatter diagram. Visual inspection alone will usually catch the obvious problems before any math. From there you have a few methods to separate the fixed and variable components. The high-low method is the quick and dirty option. You take the highest activity period and the lowest, calculate the difference in cost and the difference in activity, and divide. That gives you a variable rate per unit. Subtract that from the total cost at either point and you've got your fixed cost estimate. It's fast, usually takes about ten minutes per cost item, and it's also unreliable if those high and low points aren't representative. I've seen people use it on quarterly data where the peak happened to be a holiday surge and the trough was a planned shutdown. The results were completely misleading.
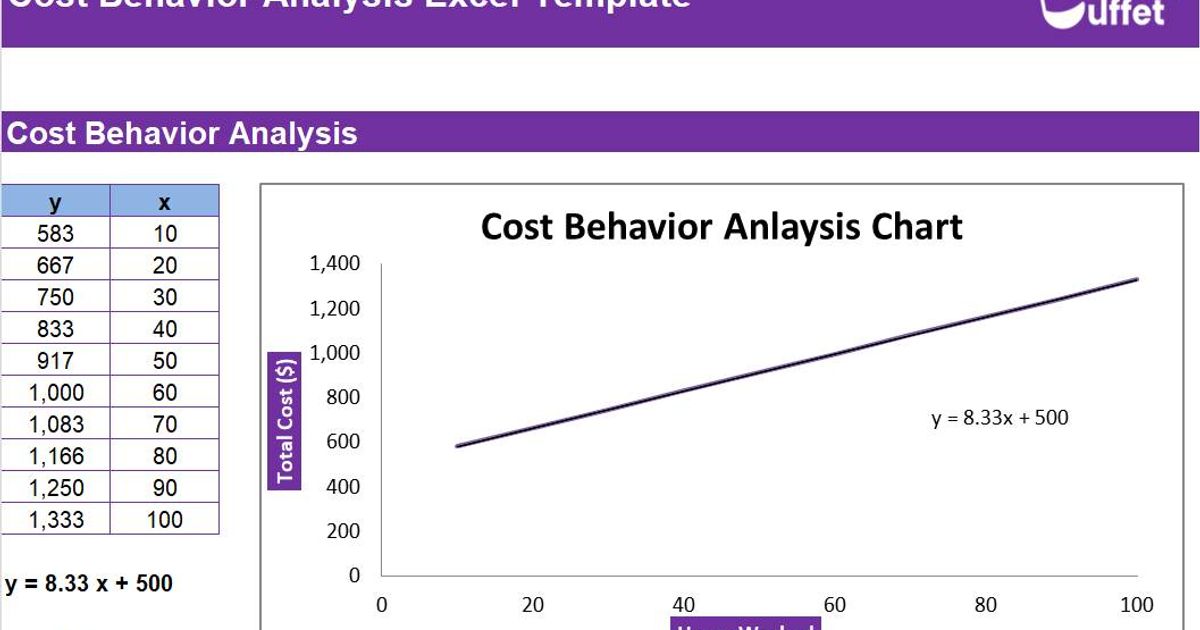
Regression analysis is the more proper approach. You run least squares on your data set and let the math sort out the slope and intercept. This works better when you have enough data points - I'd say at least twelve months of monthly data minimum. Anything less and the regression is just guessing with fancy clothes. The R-squared value tells you how much of the cost variation is explained by your activity base. Below 0.7 and you should start wondering if you've picked the wrong driver or if the cost structure is more complicated than a simple linear model can handle. There's also the scattergraph method where you actually plot the points and draw a line through them by eye. Sounds informal, but experienced people can spot outliers and nonlinear patterns faster this way than through any statistical output. I usually do this first, then confirm with regression.
Get the Full Details
Common Pitfalls That Cost You Money
The biggest mistake I see is assuming linearity across all activity levels. Costs are usually only linear within a relevant range. Cross that boundary and your fixed costs jump, your variable rates can shift, and everything you estimated falls apart. A common example is utilities. There's a base charge that's fixed, a usage charge that's variable, and then tier pricing that kicks in after a certain threshold. If you run a regression across your entire history without accounting for the tiers, your variable rate estimate will be wrong for any forecast that pushes into those higher tiers. Another issue is confusing correlation with causation in your activity base selection. Just because maintenance costs and production volume move together doesn't mean production drives maintenance. Sometimes both are driven by equipment age, or by environmental conditions, or by something else entirely. I worked with a facility where maintenance costs actually tracked more closely with humidity levels than with output, because the machinery rusted faster in certain seasons and required more overhaul work. Regression alone wouldn't have shown that without domain knowledge. There's also the problem of allocated costs inflating your fixed cost estimates. When overhead gets distributed based on some arbitrary base like direct labor hours, your cost pool includes pieces of costs you can't actually control or predict. This makes your analysis noisy and your decisions based on it shaky at best.
When This Method Falls Short
Cost behavior analysis is blunt. It works best for operational costs that have a clear link to production volume. It struggles with costs driven by strategic decisions, market conditions, or external factors. Take advertising spend - it's essentially discretionary and tied to revenue targets or market share goals, not to how many units you make. Running a regression on advertising versus production volume would give you numbers, but they wouldn't mean anything useful for forecasting. Similarly, if your cost structure has changed recently due to automation or outsourcing, historical data becomes less relevant. I had a situation where a client automated their packaging line and half their labor costs disappeared overnight. Using the previous year's data for future projections would have been a waste of time. The old cost behavior patterns were gone. You need fresh data that reflects the new operation, ideally three to six months of it before trusting any model. For services or project-based businesses, the whole concept of a single activity base breaks down pretty quickly. Revenue per project varies too much, and costs don't scale linearly with any single metric. In those cases, activity-based costing or even just tracking costs by project type gives more actionable results than traditional cost behavior analysis.
A Worked Example
Let's walk through a simple scenario. You're looking at your factory's power costs over twelve months. Your activity base is machine hours. Here's what the data might look like: Month one: 4,200 machine hours, $28,500 in power costs. Month six: 5,800 hours, $33,700. Month nine: 3,900 hours, $27,400. Month twelve: 6,100 hours, $34,600. You plot these and the pattern looks reasonably linear. Regression gives you a variable rate of about $2.15 per machine hour and a fixed component of roughly $19,500 per month. The R-squared comes in at 0.89, which is solid. So your cost equation is: Total Power Cost = $19,500 + ($2.15 × Machine Hours). If you expect 5,000 machine hours next month, you'd budget around $30,250. That's the practical application in a nutshell. The value isn't in the calculation itself - it's in knowing when to question the assumptions behind it and when to dig deeper instead of trusting the output.
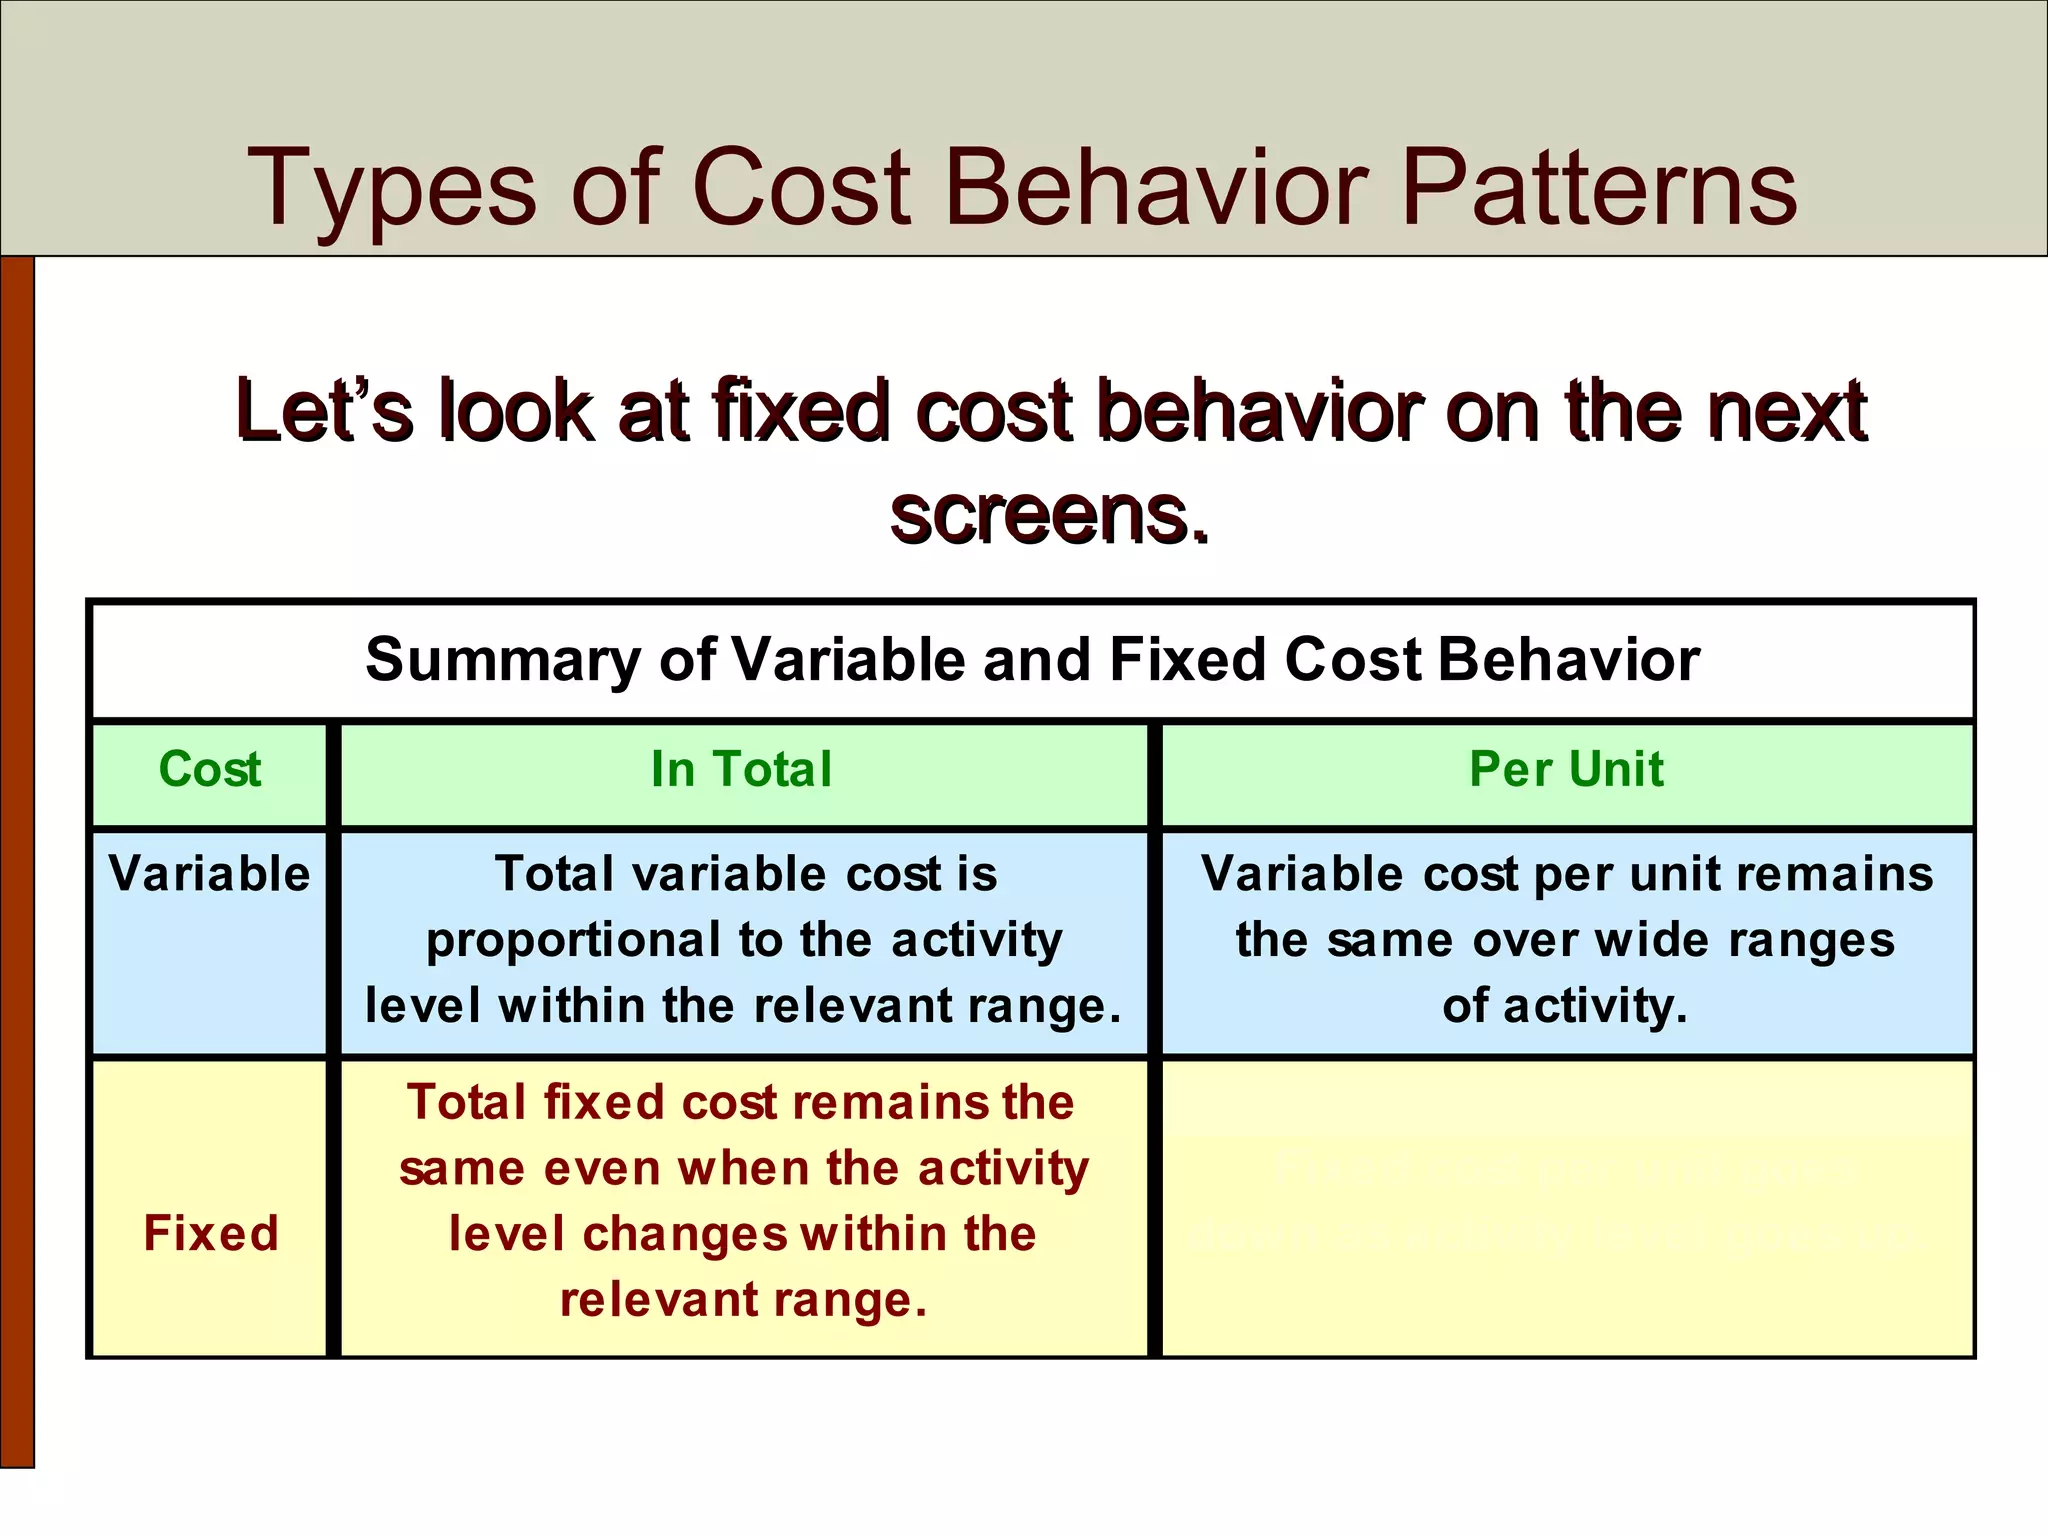
One thing worth noting: the fixed component here isn't purely fixed in the sense that it never changes. It's fixed within the relevant range of your current operations. If you add a new production line next quarter, that $19,500 base is going to shift. The analysis still holds, but you need to update it when the operating environment changes significantly.