Building a Cost Benefit Analysis Worksheet That Actually Survives Review
A Cost Benefit Analysis Worksheet is just a structured table where you list every cost and every benefit for a proposed decision, assign dollar values or scores to each, and then subtract total costs from total benefits. If the number is positive, the project passes. That is the entire method in its purest form. The reason most people struggle with this isn't the math. It is the column on the left side of the spreadsheet labeled "intangibles," where someone tries to assign a monetary value to employee morale improvements, brand reputation gains, or regulatory risk reduction. You will see people value a potential 10% drop in turnover by multiplying headcount savings at full market salary, even though you have zero evidence the project would actually change retention. That single line item can flip a negative NPV into a positive one and make an indefensible decision look sound. I worked on a facility upgrade proposal where the IT team wanted to replace aging server infrastructure. The raw hardware and licensing costs were clear. What sank the initial analysis was the intangible category labeled "reduced downtime risk." Someone plugged in a figure based on average industry downtime costs for companies our size, then multiplied it by a subjective probability factor they called "moderate." The resulting benefit number was larger than the total project cost. It didn't hold up under scrutiny.
The workaround was straightforward. I created a separate appendix column that listed only quantifiable downtime events from the past 24 months. We calculated actual lost revenue per incident, applied a weighted average, and used that as the only downtime benefit. The project still made sense, but the justification was defensible instead of decorative.
How to Build a Cost Benefit Analysis Worksheet
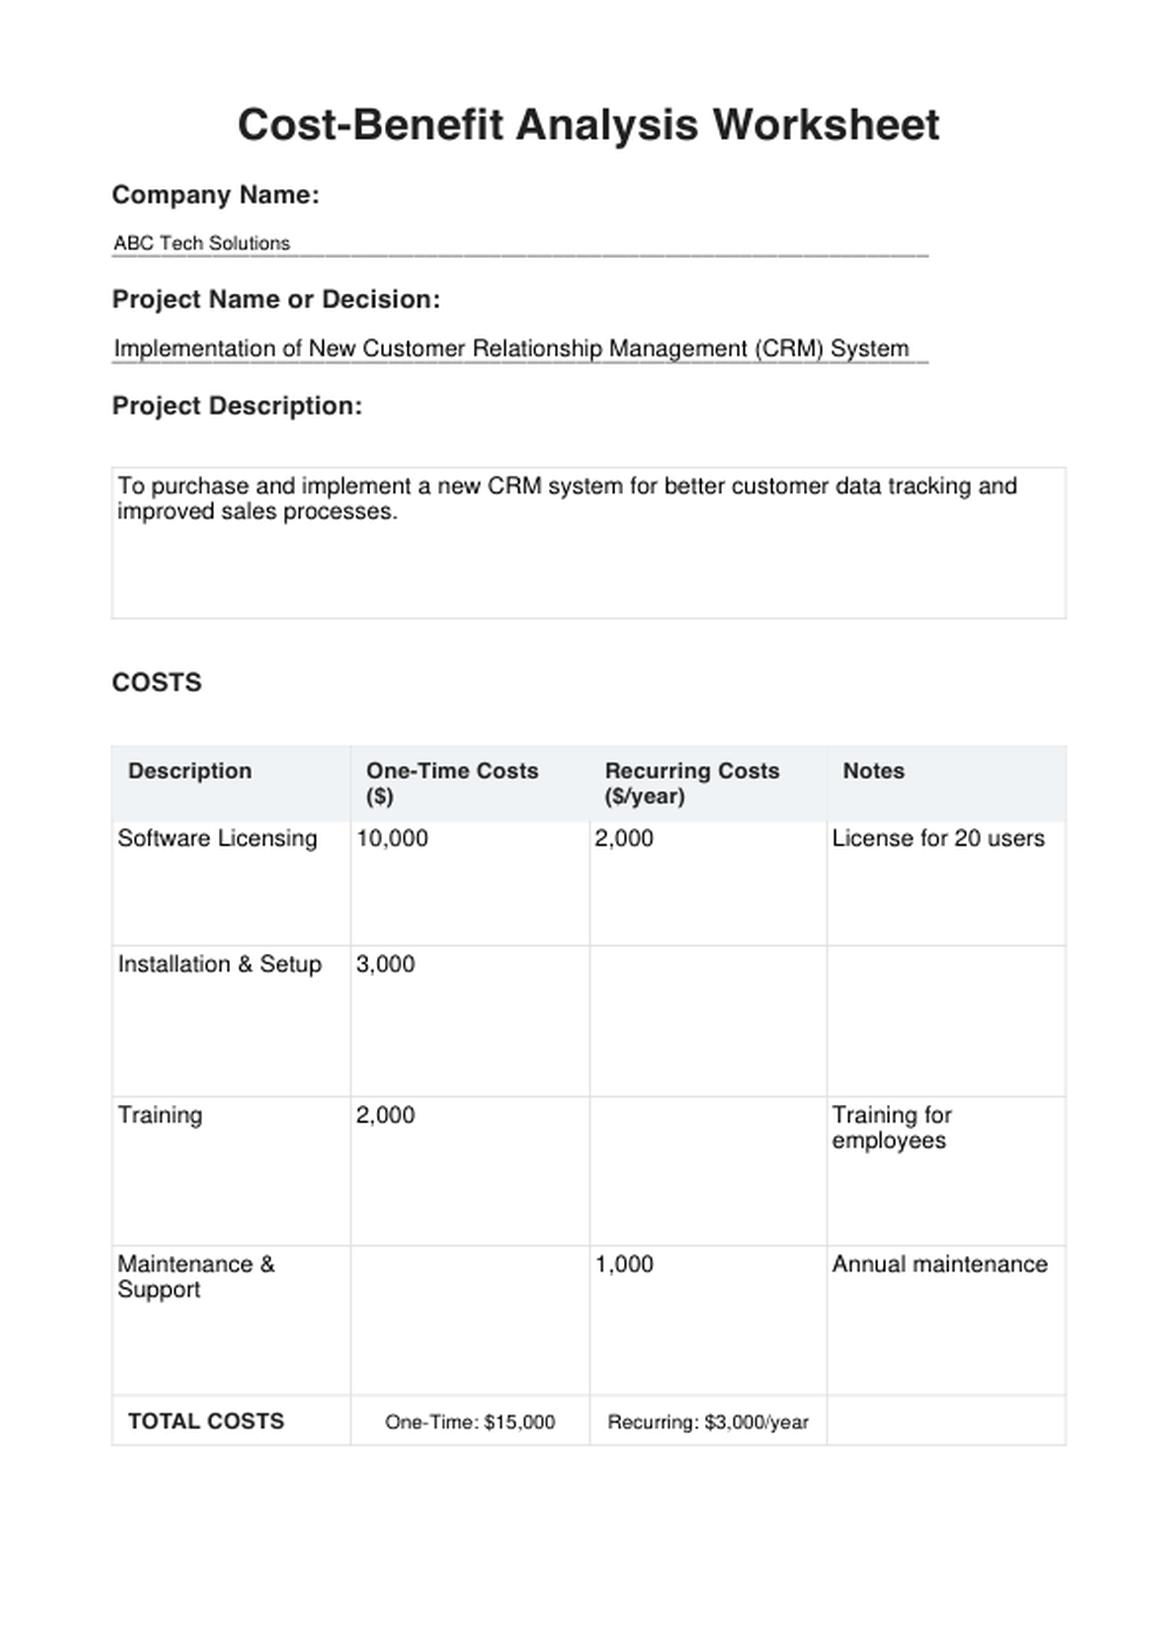
Start with a blank spreadsheet. Set up five columns: Category, Description, Type (Cost or Benefit), Value, and Notes. Put a header row and color-code costs in one shade and benefits in another so visual scanning takes seconds instead of minutes. List every cost you can identify. Hardware, software licenses, implementation labor, training hours, ongoing maintenance, decommissioning fees, opportunity costs if staff time could be deployed elsewhere. Do not lump "implementation" into a single line item. Break it into phases. A vague line labeled "setup costs" at $50,000 tells nothing. Three lines for data migration, user acceptance testing, and go-live support with individual estimates add up to the same total but expose where the real spend lives. Next, list benefits. Direct revenue increases, cost savings from replaced processes, reduced error rates, compliance avoidance, capacity gains. Value each one conservatively. If a benefit depends on a projection, state the assumption in the Notes column. "12% efficiency gain based on pilot program Q3 results" is infinitely more credible than "estimated efficiency improvement."
Get the Full Details
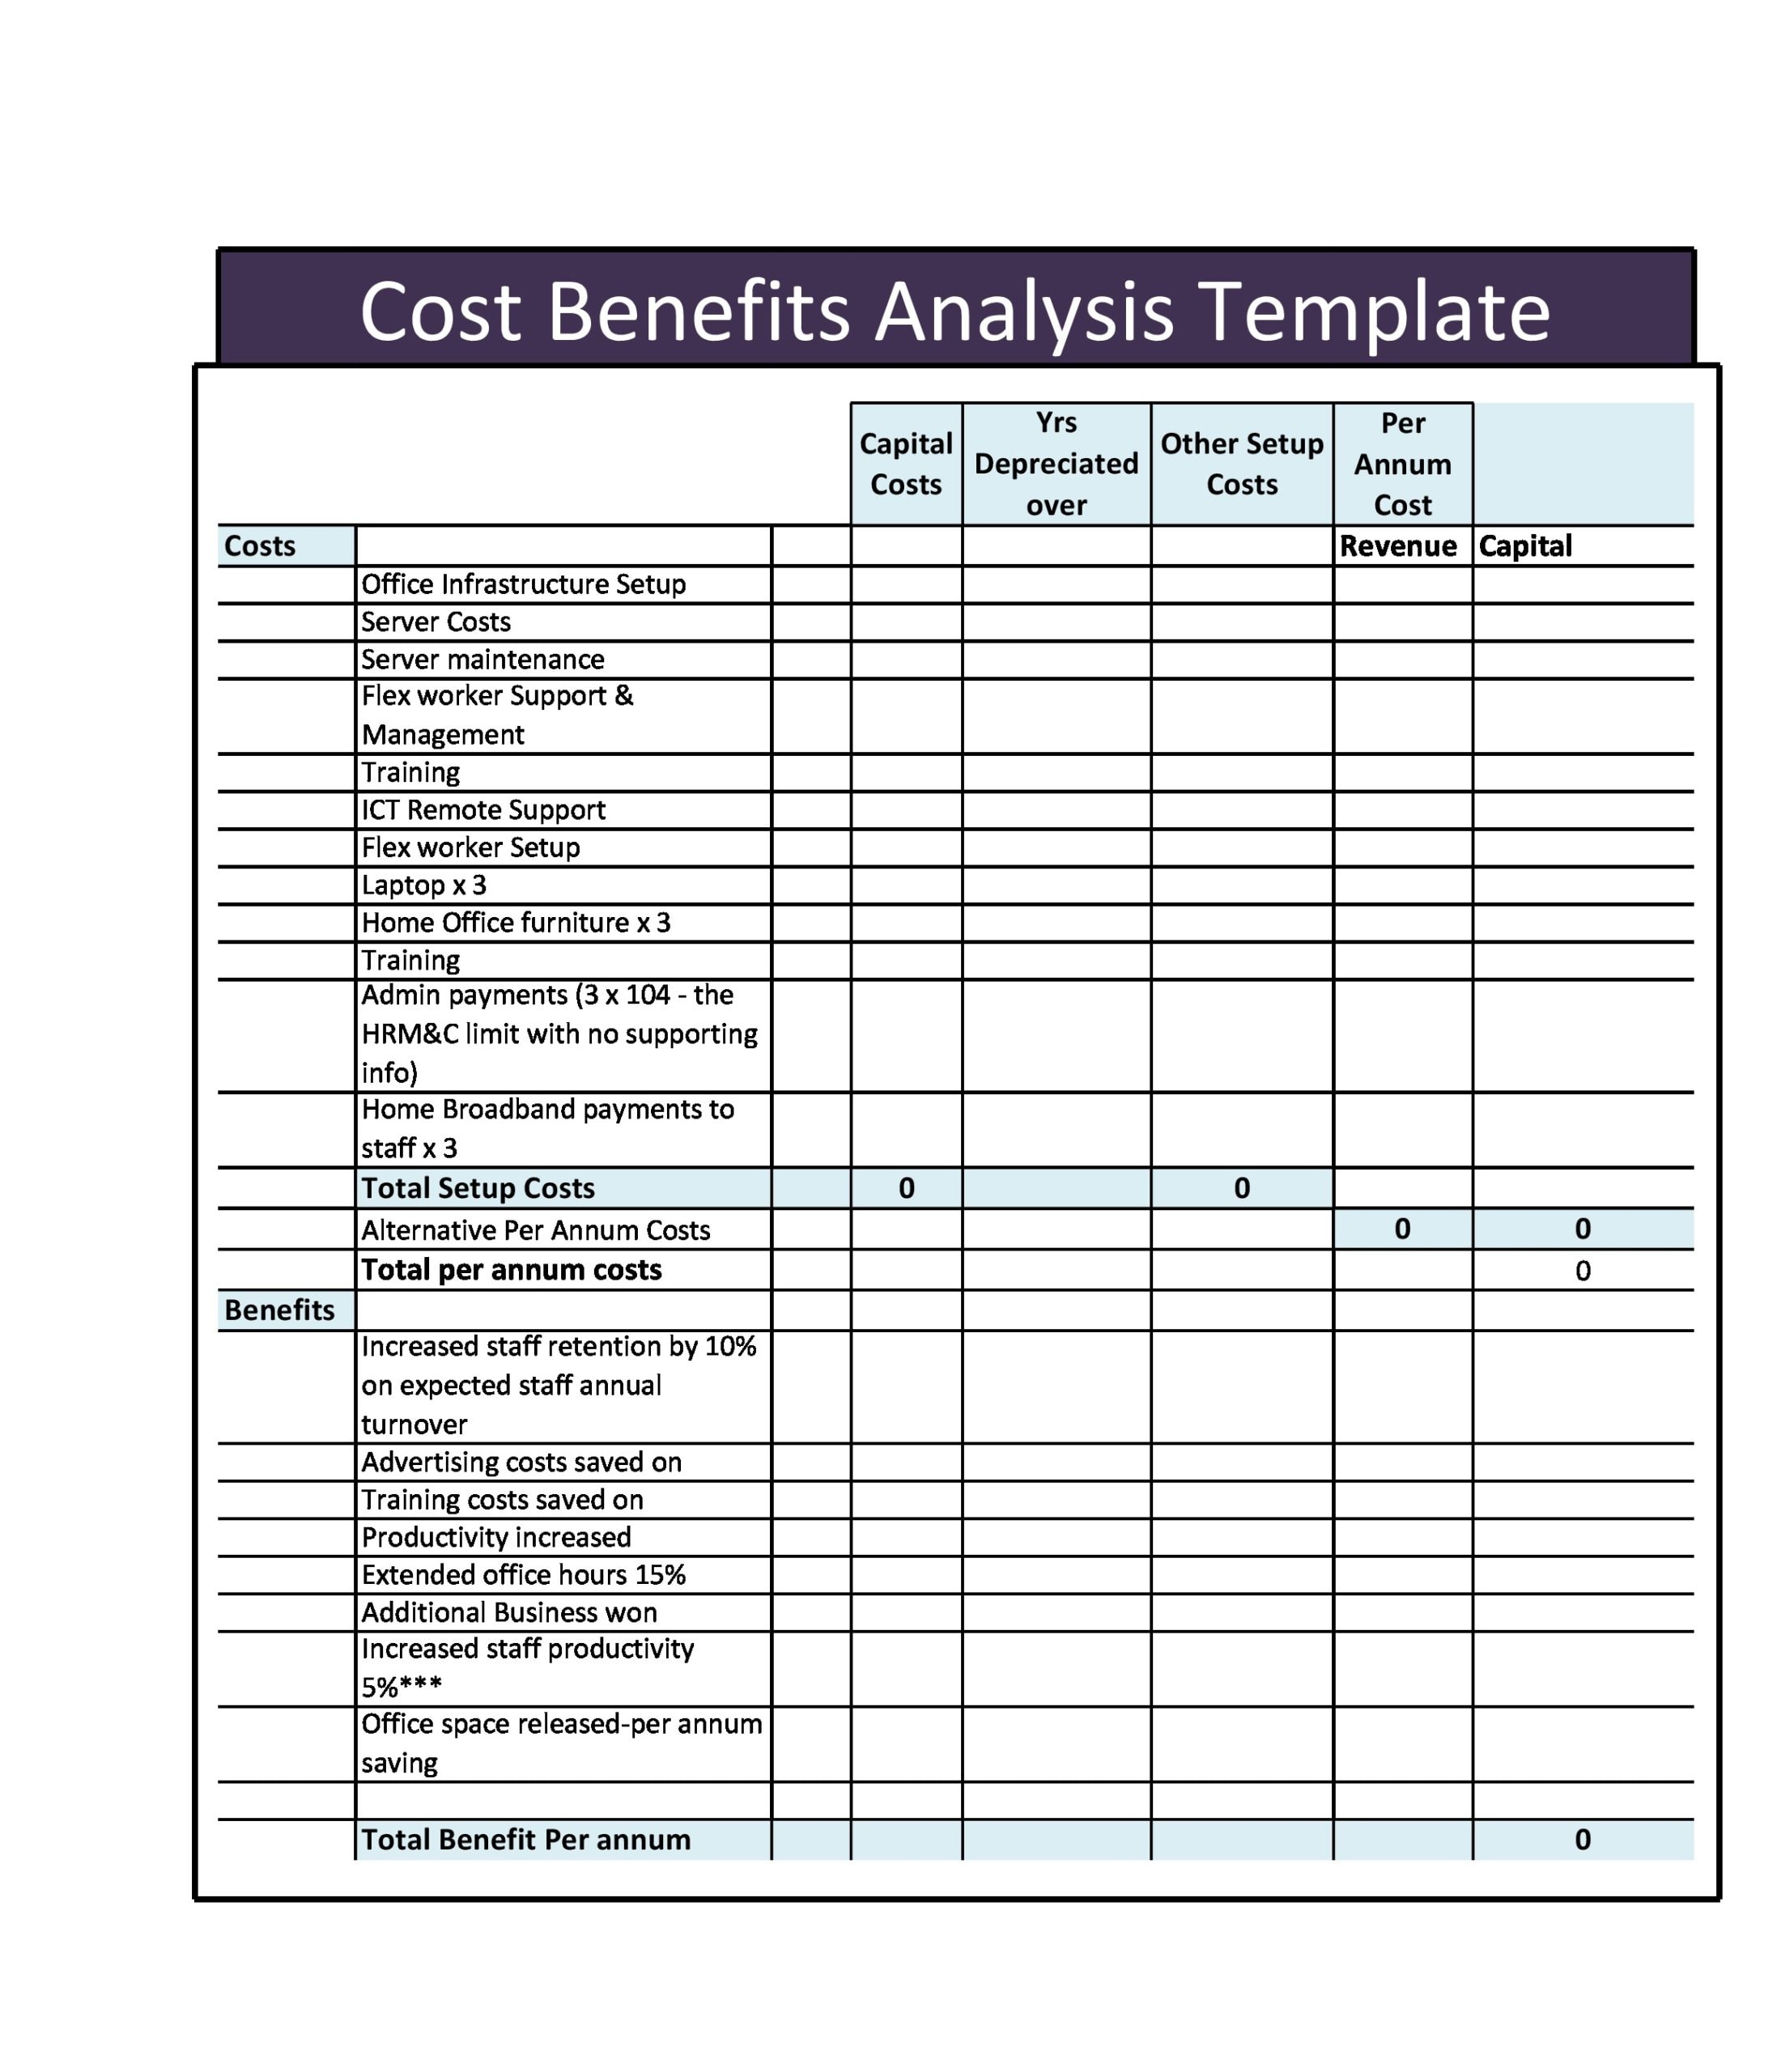
Sum the cost column. Sum the benefit column. Subtract costs from benefits. Label the result Net Present Value if you are discounting future cash flows, or Net Benefit if you are working with nominal figures. Compare the result against your organization's hurdle rate or minimum acceptable return threshold. The actual mechanics take maybe 15 to 30 minutes once you have a template built. The first version of any worksheet for a new project type will take longer because you are still figuring out what categories matter. After that, reuse and adapt the same structure. Most of the work is already done.
Things Beginners Miss About Cost Benefit Analysis
People routinely forget to discount future benefits. A $100,000 saving two years from now is not worth $100,000 today. Apply your organization's standard discount rate, usually between 8 and 12 percent for internal projects, to bring future values to present terms. Without discounting, long-cycle projects appear artificially attractive. The difference between undiscounted and discounted analysis can shift a marginal project from green to red. Another common error is treating the CBA result as the decision itself. A positive net benefit does not mean you should proceed. It means the project clears one specific bar. Capital allocation, strategic alignment, risk tolerance, and resource availability all operate independently. A project can have a strong net benefit and still be a poor use of capacity if your team is already at maximum utilization on higher-priority work. Sensitivity analysis is the step most people skip. Change your key assumptions by plus or minus 10 to 20 percent and watch how the result moves. If a 15 percent increase in estimated costs turns a $200,000 net benefit into a negative, your decision is fragile. Document those break-even points. Stakeholders will ask about them whether you planned to or not.
There are also scenarios where a Cost Benefit Analysis Worksheet is the wrong tool. It struggles with qualitative decisions where values cannot be reasonably monetized. Strategic positioning, competitive response timing, and brand-direction investments resist clean quantification. In those cases, a weighted decision matrix or scenario-based assessment serves better. The worksheet creates an illusion of precision that does not exist. The template itself should live somewhere accessible to the team, not buried in a single person's downloads folder. Shared drives, internal wikis, or a dedicated project management tool work fine. Consistency matters more than sophistication. Five people using the same structure produce comparable results. Five people building five different spreadsheets produce noise.