Why your budget tracking is lying to you
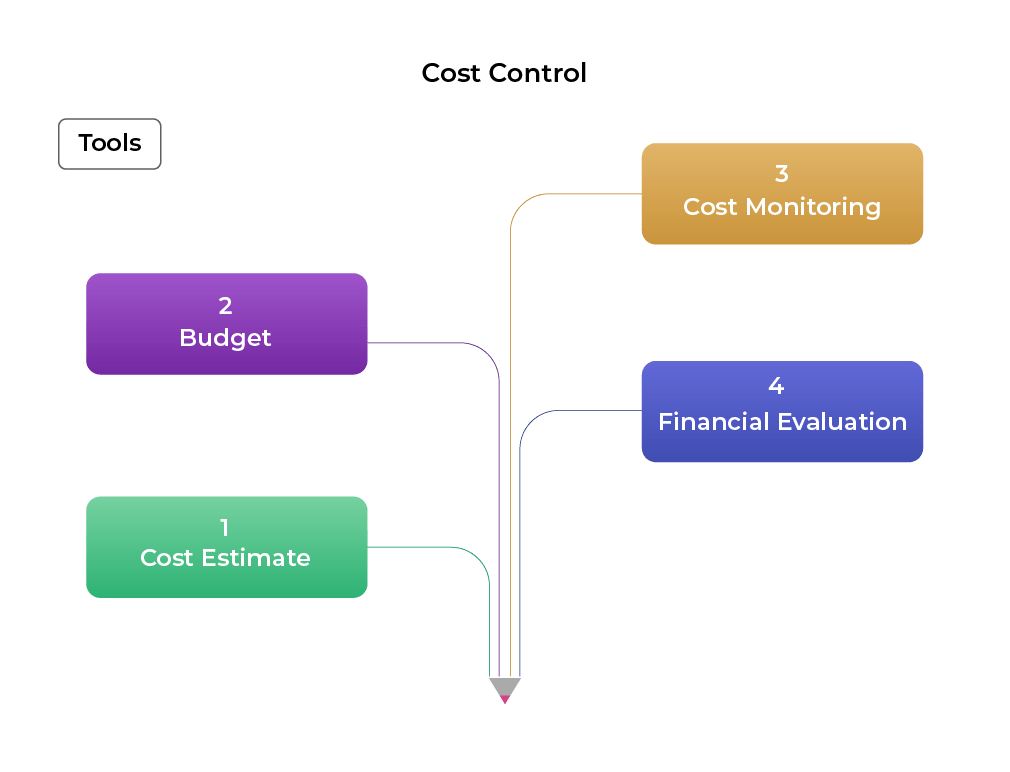
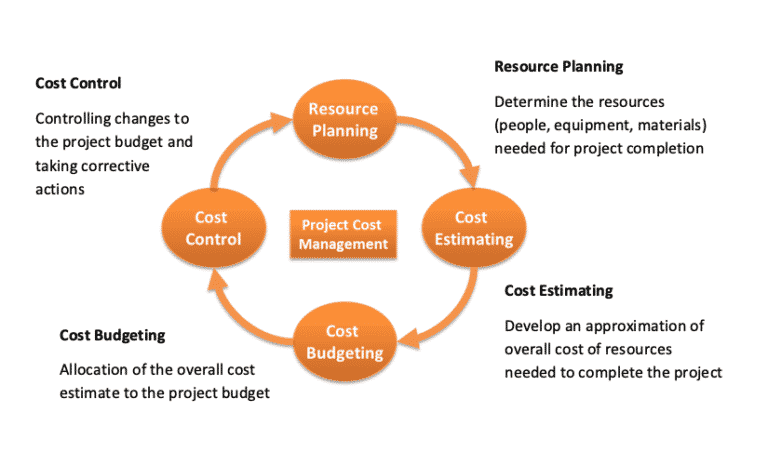
Most project managers track costs by comparing actual spend against planned spend at the end of each month. That approach only tells you where you've already failed. By the time you see a negative variance, the money is gone and the work is mostly done. The useful techniques are the ones that catch problems while there is still time to do something about them. Cost Control Techniques In Project Management aren't complicated concepts. They're just easy to execute poorly. The standard toolkit includes earned value management, budget at completion tracking, reserve analysis, change control processes, and periodic earned value reporting. Most teams use some version of these. Very few use them effectively because the execution depends on discipline, not methodology. Earned value is the cornerstone, and it's also the most misunderstood tool on the list. You calculate three data points: planned value, actual cost, and earned value. From those you derive schedule variance and cost variance. A positive cost variance means you spent less than the work performed warrants. Negative means the opposite. The formula is straightforward, but the data quality required to make it useful is where things fall apart.
I worked on a construction project a few years back where the earned value numbers looked fine on paper but the project was bleeding money. The problem was that earned value was being calculated based on % complete estimates from the field team, and those estimates were optimistic to the point of fiction. The site supervisors were giving me percentages that matched their schedules, not their actual resource consumption. We were 70% complete on paper but had already spent 85% of the budget. The variance wasn't showing up because the input data was corrupted at the source. The workaround was to stop accepting % complete estimates and start tying earned value to verified units of work completed. Every deliverable was broken into measurable chunks with predefined unit values. You couldn't claim credit for 60% of a wall being built. You got credit for the wall when the wall was done, or for the quarter-section when that quarter-section met the. It took more effort to track, but the numbers suddenly meant something. Variance went from a smooth line to a jagged mess, and that jagged mess told us exactly where we had problems instead of hiding them. Reserve analysis is another technique that gets treated as an afterthought. You establish a management reserve and a contingency reserve, then monitor their drawdown rates. The counter-intuitive part is that a reserve that isn't being touched is often worse than one that is. An untouched contingency reserve usually means your risk identification was insufficient or your scope assumptions are wrong. You should expect some consumption over the project lifecycle. Zero drawdown suggests you didn't plan properly, not that everything is going well.
Change control is where most cost overruns originate. A change request might look small in isolation. One additional fixture here, a material upgrade there, a revised specification from the client. Individually they don't break the budget. Together they typically account for 15 to 30% of the original project cost, which is the standard range for uncontrolled scope growth in my experience. The technique isn't sophisticated. It's requiring that every change request include a cost impact estimate before it gets approved, logging those estimates in a running cumulative change register, and reporting the register alongside the regular budget report so stakeholders see the aggregate effect rather than reacting to individual changes in isolation. Rolling wave planning helps with forward-looking cost control. You detail the work packages and associated budgets for the next two to three weeks with high specificity, while keeping subsequent phases at a higher level of abstraction. As those early weeks complete, you pull the next wave into focus. This prevents the common problem where early-phase spending distorts later-phase estimates because the later work hasn't been properly decomposed yet. The budget looks accurate for phase one and speculative for phase three, which is when you tend to make poor commitment decisions. The technique that nobody talks about but should is variance threshold analysis. Instead of treating every small variance as a problem, you set acceptance thresholds and only escalate when variances exceed them. A one percent cost overrun on a line item that's already ten percent under budget is noise. A three percent overrun on a critical path deliverable with no float is a signal. Defining those thresholds upfront saves managerial attention for things that actually matter. My rule of thumb is a two percent threshold on any single work package above fifty thousand dollars and absolute escalation on any critical path variance regardless of magnitude.
Get the Full Details

There are situations where earned value simply doesn't work. Rapidly prototyping environments, research and development projects, software development with frequently shifting requirements, and projects where deliverables are qualitative rather than quantitative. In those cases, forcing EVM data creates false precision. The alternative is control chart methodology applied to cost drivers. You track the metrics that actually move the needle for your specific project type and set statistical control limits around them. When a data point crosses the control limit, you investigate. When it stays within limits, you continue normally. This replaces the artificial structure of earned value with something that matches your actual work pattern. Cash flow forecasting is separate from budget control but directly affects your ability to maintain it. A project can be profitable on paper and still fail because of cash flow timing. You need to forecast when expenditures will actually occur versus when they're budgeted. Vendor payment terms, material delivery schedules, subcontractor milestones, and payroll cycles all create timing mismatches between your budget and your bank account. A monthly cash flow forecast updated biweekly catches these mismatches before they become emergencies. One practical detail that people miss is the relationship between cost control frequency and project duration. Weekly cost reviews make sense for projects longer than six months. Biweekly is adequate for three to six month projects. Monthly reviews for shorter engagements. More frequent than that and you're spending more time on reporting than on managing. Less frequent than that and you lose the feedback loop entirely.
Resource leveling intersects with cost control in ways that aren't always obvious. When you level resources to smooth out peaks and valleys in utilization, you're also leveling cost expenditure. A project with a massive resource spike in month three will have a corresponding cost spike that can trigger cash flow issues even if the total budget is fine. Leveling the resource profile levels the cost curve, which makes forecasting and control more stable. The hardest part of implementing any of these techniques consistently is getting the initial data structured correctly. Your work breakdown structure needs to align with your cost account structure. If your WBS has work packages that don't map cleanly to cost categories, you're going to spend your time reconciling formats instead of managing costs. Take two weeks upfront to get this mapping right. It saves months of friction later. You should also track cost per unit of output where applicable. Not just total project cost but cost per square foot, per line of code, per user story completed, per unit manufactured. These ratios catch cost drift that absolute numbers hide. If your total cost is on budget but your cost per unit has increased twenty percent, you've lost efficiency even though the aggregate number looks fine.
Procurement cost tracking deserves its own attention. The purchase order commitment amount, the actual invoice amount, and the variance between them should be tracked separately from your operational cost data. Procurement variances often stem from different issues than operational variances. Market price shifts, supplier errors, and contract terms create their own patterns that get diluted when mixed with day-to-day spending data. Separating them gives you different diagnostic information. Here's something that surprises people: sometimes the best cost control action is to deliberately overspend early. If you have a clear understanding of where your risks are and you front-load the mitigation spend, you reduce the probability of costly rework later. This is especially relevant for quality assurance activities and testing. Spending fifteen percent more on thorough testing in the design phase can save you eighty percent of what you'd spend fixing defects in production. The budget looks worse in month two. The final cost is materially lower. Most cost control systems punish the early spend and reward the delayed spend, which is backwards for anything involving risk reduction. The tools you use matter less than the process discipline. Spreadsheet templates, project management software, dedicated cost control modules, all of them produce the same output if the underlying process is sound. They also produce garbage if the process is weak. I've seen teams spend thousands on enterprise project management platforms and still miss cost overruns because nobody was doing the basic work of updating actuals regularly and comparing them against earned value. The software doesn't control costs. People do.

What matters for implementation is starting small. Pick one or two techniques and apply them rigorously to one project before rolling them out org-wide. Earned value and change control registers are the most impactful starting points. Reserve analysis and cash flow forecasting are secondary but important. Resource leveling and unit cost tracking are tertiary. Get the fundamentals right first. The advanced techniques compound on top of a working foundation. A final note on reporting. Your cost reports should answer three questions in the first ten seconds of reading: Are we over or under budget? When will we know for sure? What needs attention now? Everything else is detail. If your report requires the reader to understand the methodology before they understand the situation, it's too complex. Strip it down until only the essential information remains.