What Actually Happens When You Segregate Depreciation
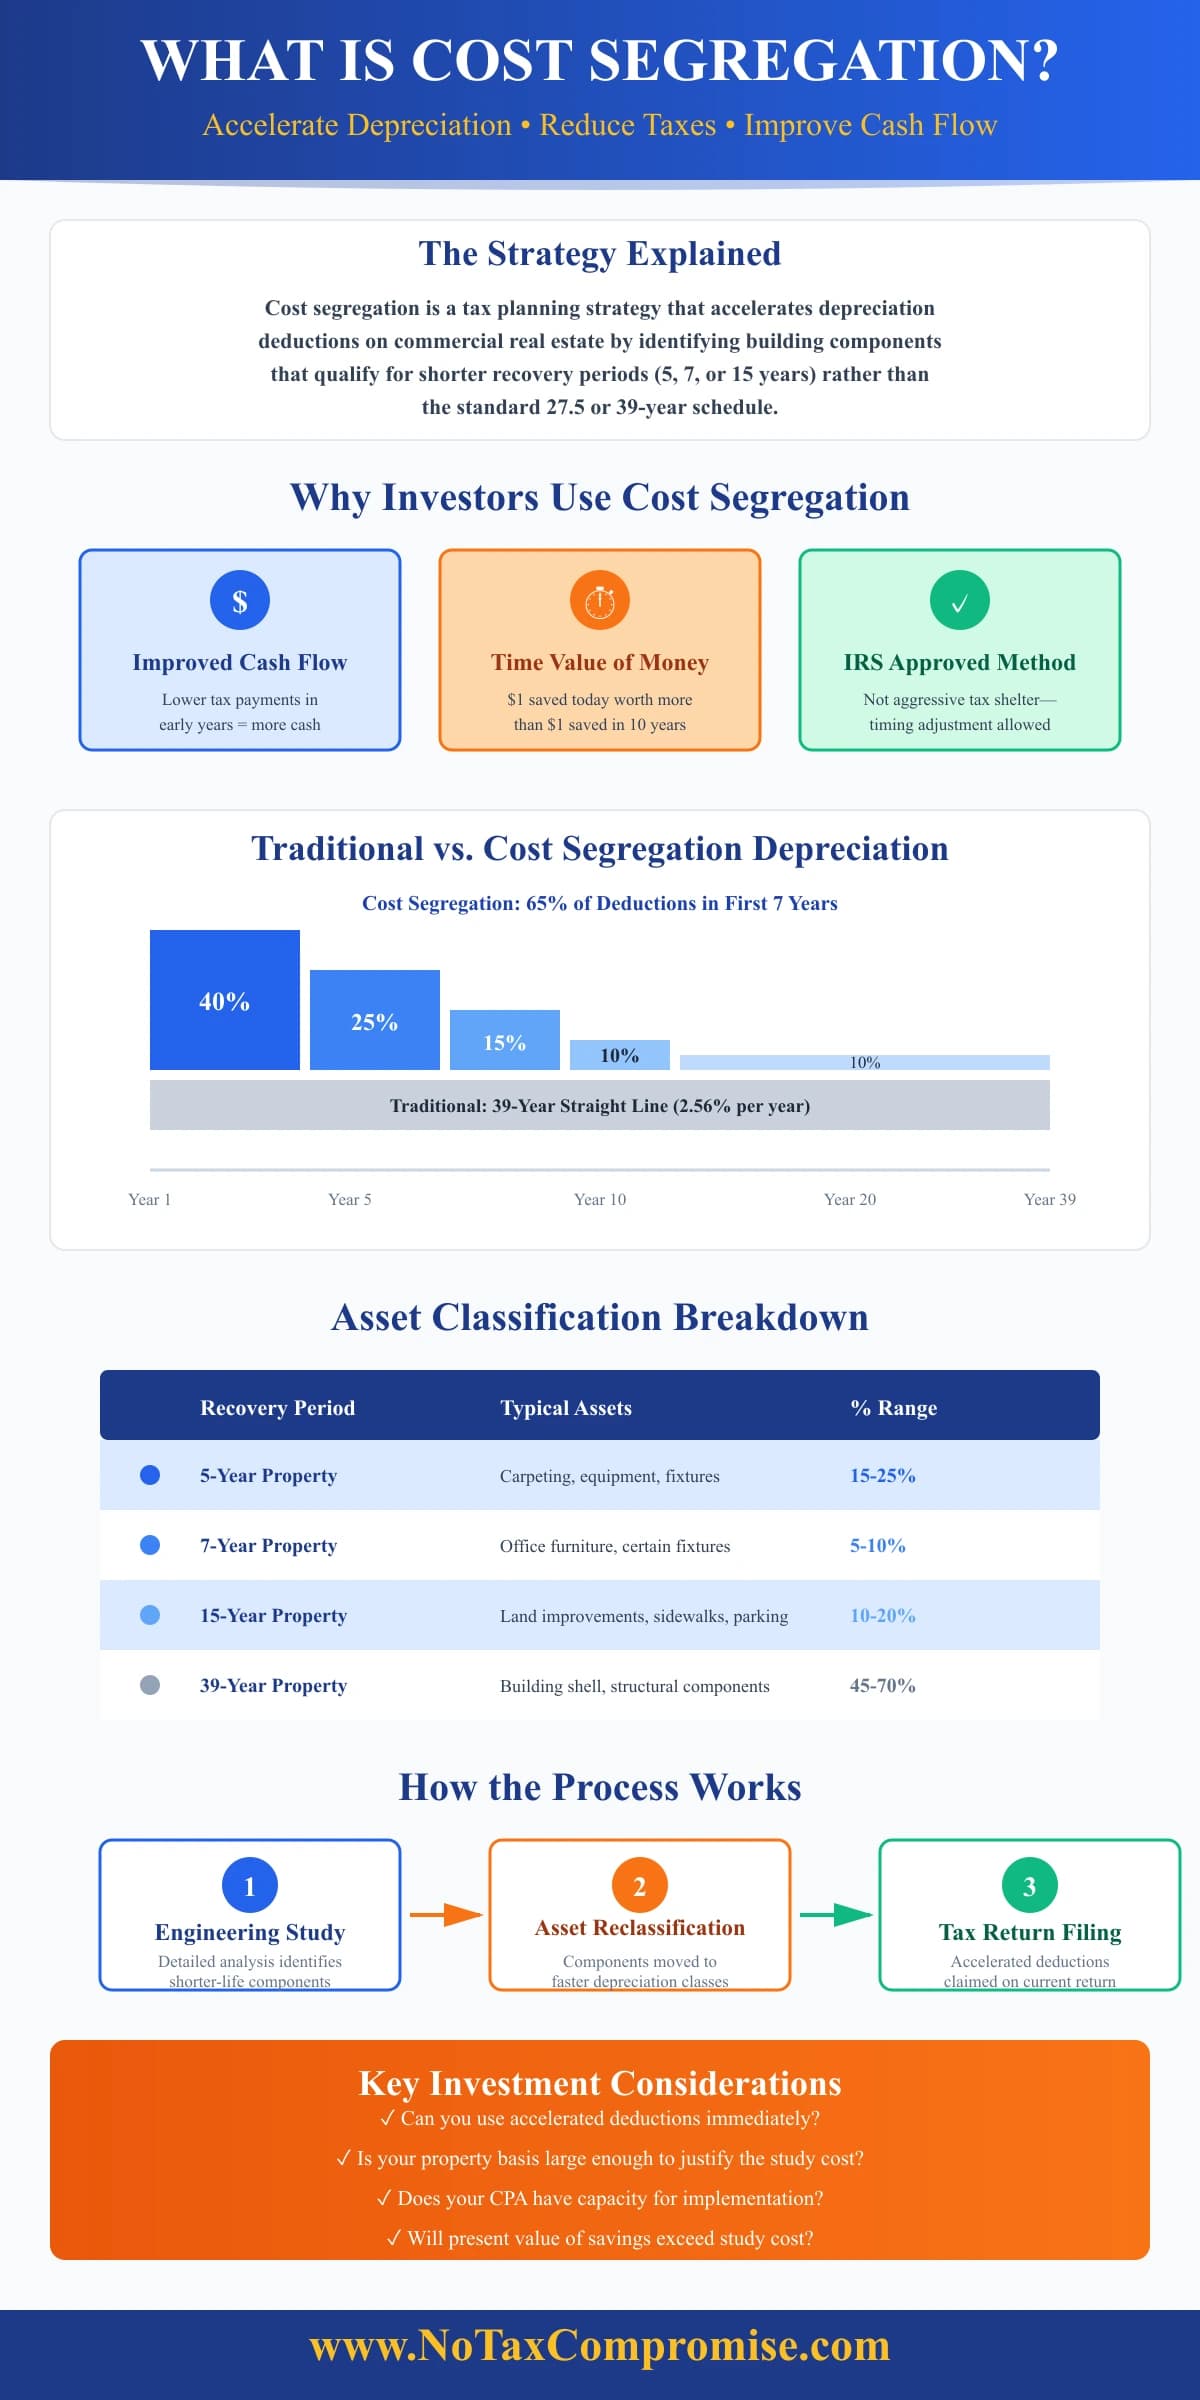
A commercial building gets treated as one long-life asset on paper, but that is not how it breaks down in reality. The HVAC system fails before the roof. The carpet gets replaced while the foundation stays good for decades. Cost Segregation Depreciation Guide is really just a method for splitting those components apart so you can depreciate each piece at its actual rate instead of dragging everything out over 39 years. You start by taking the purchase price or construction cost of a building and having a engineer or specialized preparer go room by room, system by system. They identify personal property and land improvements that qualify for shorter recovery periods. Five-year property covers things like carpet, flooring, certain lighting fixtures, and some signage. Seven-year covers office furniture and equipment. Fifteen-year covers qualified improvement property like roofing, HVAC systems, and certain interior renovations. Land improvements such as parking lots and fencing fall into that same 15-year bucket. Everything else stays on the 39-year straight-line schedule for non-residential real property.
Getting a Cost Segregation Depreciation Guide That Actually Works
I spent six hours last year trying to figure out why a client's first-year depreciation schedule looked nothing like what the engineer's report projected. The issue was MACRS mid-month convention applied retroactively because they placed the building in service in the middle of the year. The engineer's spreadsheet assumed mid-year convention throughout. We recalculated using the proper IRS tables and adjusted the schedule by about $42,000 in the first year alone. The fix was purely mechanical, but finding it required someone who actually understood the interaction between the convention and the component breakdown. The practical process usually goes like this. You commission a cost segregation study from a qualified firm, ideally within the first year of acquisition or placement in service. The report will itemize each component with its remaining useful life, adjusted basis, and depreciation method. You then feed those numbers into your depreciation software or schedule manually. For a typical $2 million office building, you might find between $300,000 and $600,000 reclassified into shorter life categories, depending on how much tenant improvement work was done and what systems were recently replaced. The biggest mistake I see people make is assuming the study itself is the final product. It is not. The study produces data. Someone with tax software knowledge or a preparer needs to translate that data into actual filed schedules that comply with current IRS conventions. Without that step, the study sits in a drawer and does nothing for your tax position.
Where This Method Falls Apart
Cost segregation only makes sense if you have enough depreciable basis to make the acceleration worthwhile. On a $500,000 mixed-use building where the land value consumes most of the basis, you might recover an extra $20,000 to $40,000 in the first year after all adjustments. The study itself typically costs between $3,000 and $8,000 depending on property size and complexity. The ROI becomes thin when the reclassification amount barely clears the preparation cost, especially if the taxpayer does not have sufficient passive or ordinary income to absorb the accelerated deduction against. Another hard limitation is the personal property recapture rule under Section 291 for C corporations. If you are a C corp, 40 percent of the additional depreciation you accelerate through cost segregation gets recaptured as ordinary income when you sell the property, instead of flowing through to capital gains treatment. That eliminates a significant chunk of the upfront benefit and changes the math considerably. S corporations and partnerships do not face this rule, which is why the strategy sees far more use there. There is also the issue of state conformity. Some states follow federal depreciation rules automatically and you get the benefit immediately. Others require you to add back the difference between your accelerated federal depreciation and your straight-line state depreciation, then recapture it over time. In states like New York and California, the add-back requirement can reduce the net present value advantage by roughly half compared to a conforming state. You need to check your specific state's rules before committing to the strategy, because the paperwork burden increases and the cash flow timing shifts.
Get the Full Details

Things the Standard Guides Do Not Tell You
Most publicly available resources treat cost segregation as a one-time event tied to acquisition. That is incomplete. When you place an addition or renovation in service on an existing building, you can run a separate cost segregation study on just that new basis, even if you bought the original building years ago. I had a client who added a $1.2 million annex to a warehouse they acquired in 2014. We ran a cost seg on the annex alone in 2023 and got roughly $210,000 in accelerated deductions in year one without touching the original building's depreciation schedule. The two studies coexist independently on the same return. A second thing that trips people up involves the treatment of prepaid rent improvements. Tenant improvements that a landlord funds and the tenant later repays through increased rent are still the landlord's depreciable assets, but the timing of when you start depreciating them depends on when you place them in service, not when the lease formally begins. I once saw a preparer delay the depreciation start date until the tenant moved in, which pushed the entire first-year deduction into year two and lost the taxpayer a full year of accelerated write-off. The IRS position is clear on this, but the mistake happens often enough that I assume it is a common point of confusion until someone directly addresses it.
What to Ask When You Commission a Study
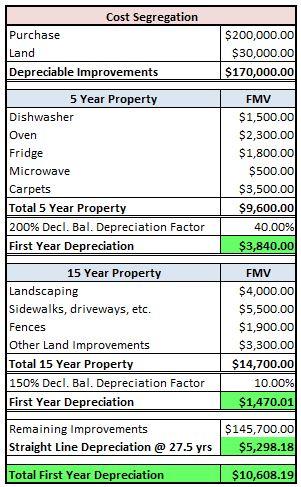
Make sure the preparer uses a current software platform that outputs MACRS schedules with the correct convention calculations built in. Hand-spreadsheet studies are a real risk, and the error I described above came from a study prepared on an outdated template. Ask for a summary page that shows the total reclassified amount, the breakdown by recovery period, and the estimated first-year depreciation impact. If the preparer cannot provide that, it is a red flag. You should also confirm whether the report distinguishes between property that goes to five years, seven years, fifteen years, and the remaining thirty-nine years, and whether it accounts for any partial disposition elections if components were replaced previously. The IRS allows you to elect to deduct the adjusted basis of retired components rather than continuing to depreciate them, and a proper cost segregation study should factor that option into the analysis. Skipping this detail means leaving money on the table or creating a potential audit trigger if the IRS notices continuing depreciation on assets that are no longer in service. The bottom line is that this is a legitimate strategy with real constraints. It produces meaningful first-year deductions on properties with sufficient basis, it interacts poorly with C corp recapture rules and certain state conformity requirements, and it requires competent follow-through to actually translate the engineering report into filed numbers. If your property qualifies and you have the income to use the deductions, it is worth the effort. If not, the study cost may not justify the outcome.