What Cost Volume Profit Analysis Examines Actually Means
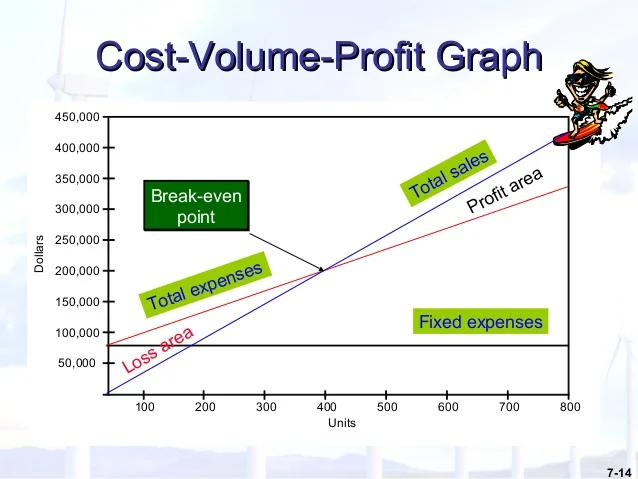
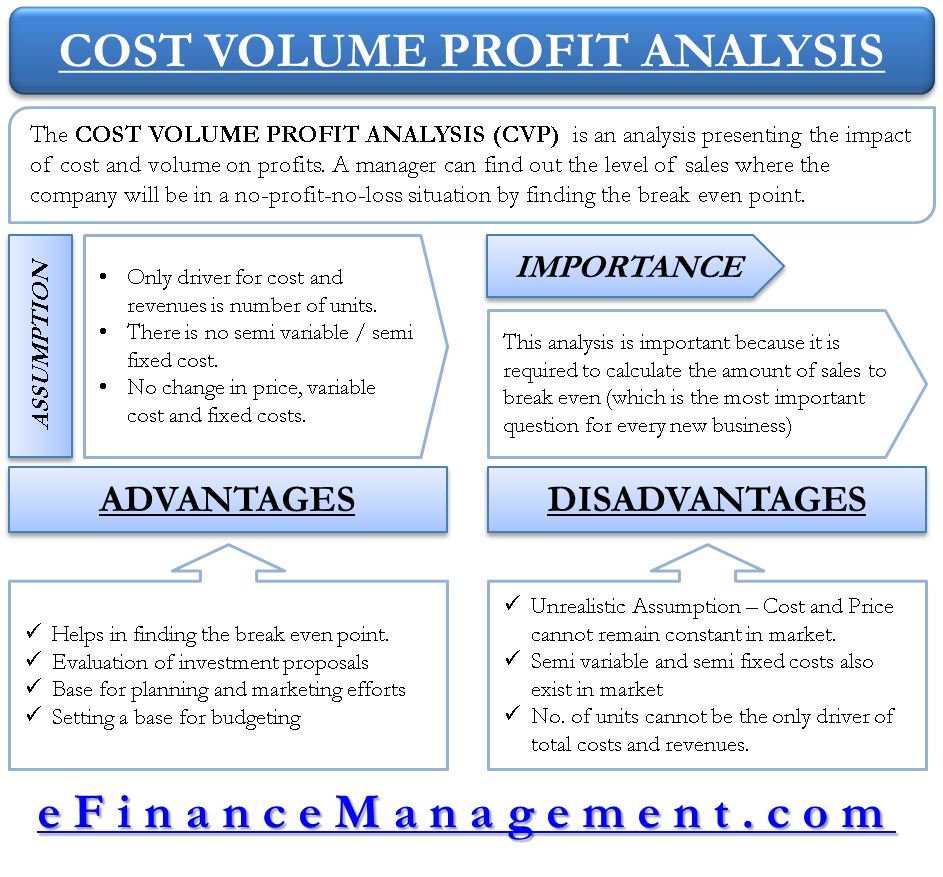
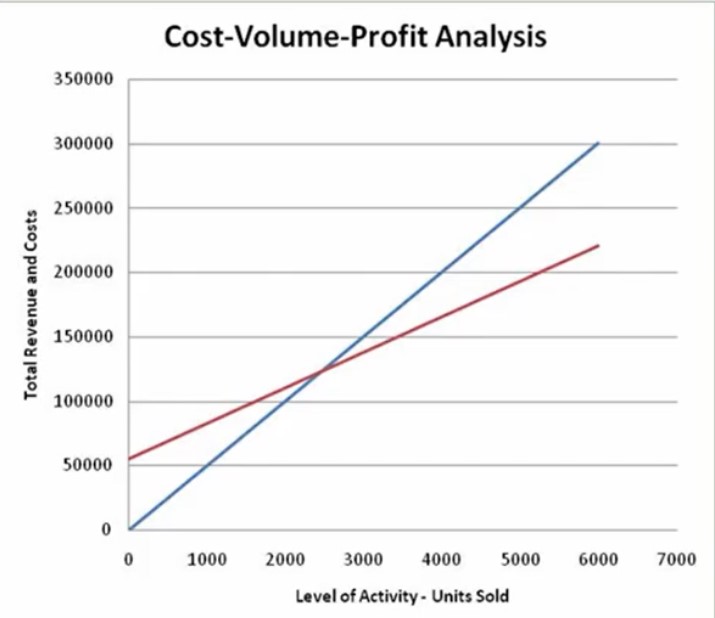
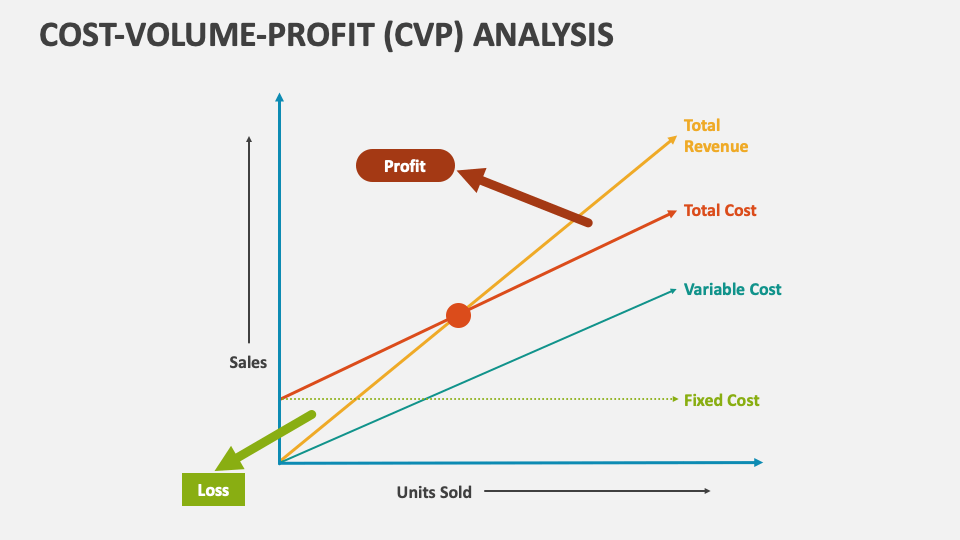
Cost Volume Profit Analysis Examines the relationship between a company's revenues, costs, and operating profit across different levels of production or sales volume. It's a straightforward framework that answers one practical question: how does changing volume affect your bottom line? That's it. No magic. The core logic rests on three things you already know from basic accounting. Revenue minus total cost equals profit. Total cost splits into fixed costs and variable costs. Fixed costs stay the same regardless of how much you produce, while variable costs scale directly with output. When these three pieces line up, you get a tool that tells you what volume level you need to hit just to cover every cost. Below that point, you lose money. Above it, you keep making money. The break-even point is where the math lands at zero profit.
How the Basic Method Works
I need to walk through this because people consistently mess up the variable cost assumption. The contribution margin per unit is your selling price minus your variable cost per unit. Take fixed costs and divide by that contribution margin, and you get break-even units. Say you sell a widget for $50. Your variable cost per widget is $30. Your fixed costs are $80,000 a month. Contribution margin is $20 per unit. Divide $80,000 by $20 and you get 4,000 units to break even. Sell 5,000 units and you make $20,000 in profit. The math doesn't lie, but the assumptions underneath it do. That's where things get interesting. The standard CVP model assumes linear cost behavior across a relevant range. That means variable cost per unit stays flat and fixed costs stay flat. In reality, neither of those holds true forever. Bulk material discounts shift your variable cost curve downward at higher volumes. Step-fixed costs jump when you need a second machine, a new supervisor, or a warehouse lease renewal. These don't appear in textbook examples.
I learned this the hard way in 2019 when I built a CVP model for a small manufacturing client producing custom industrial enclosures. The model projected break-even at 3,200 units. We closed the deal at 3,400 units and celebrated. Then month two hit and our unit variable cost crept up 18 percent because we were paying overtime on the assembly line and the aluminum supplier hit us with a mid-contract price adjustment. The break-even point had silently shifted to roughly 4,100 units. We had already committed to deliveries at the old margin assumption. We took a $14,000 hit that quarter that the original CVP analysis should have flagged if I'd accounted for the step changes properly. The fix was brutal but simple. I restructured the model to use tiered variable costs instead of a single average. I built in a sensitivity table that showed break-even at three different volume brackets with their respective unit costs. It took me about an hour to redo, but it prevented that scenario from happening again. Now I always model at least three volume tiers with differentiated cost assumptions.
Get the Full Details
What Most People Get Wrong About CVP
The biggest mistake I see is treating contribution margin as a permanent percentage of revenue. When sales mix shifts, the overall contribution margin ratio shifts with it. If your company sells both high-margin custom products and low-margin standard products, and the standard product sells more than expected, your blended contribution margin drops and your break-even volume rises even though total revenue looks fine. I've seen this destroy forecasts. A distributor I consulted for in 2022 had two product lines. Line A ran at 65 percent contribution margin. Line B ran at 22 percent. Their CVP model used a blended 48 percent margin based on the prior year's sales mix. When Line B gained market share and became 55 percent of sales instead of 30 percent, the actual blended margin dropped to 38 percent. They were selling more volume than projected but still missing their profit target by $92,000. The volume was fine. The mix was wrong and the CVP model didn't account for it. Mixed costs are another trap. Not every cost is purely fixed or purely variable. Utilities, maintenance, quality control labor. These have components of both. The high-low method or regression analysis can help separate them, but both have limitations. The high-low method uses only two data points. Regression requires clean historical data that most small companies don't maintain well enough.
If you're working with messy real-world data, don't force a single variable cost assumption. Build ranges. Show best case, normal case, and worst case on your break-even chart. Stakeholders understand ranges better than they understand false precision.
The One Scenario Where CVP Completely Breaks Down
CVP analysis assumes you can sell everything you produce. That works in theory. In practice, it fails hard when demand is constrained, when you operate under long-term contracts with fixed quantities, or when you're pricing new products with no historical demand signal. If you can't move units regardless of what price you set, the volume variable in the equation becomes meaningless. I ran into this with a specialty chemical firm that had C&MA-grade compliance requirements. Their regulatory approvals capped monthly output at 12,000 kilograms regardless of demand. Their CVP model showed them breaking even at 8,000 kilograms, which looked excellent on paper. But 8,000 kilograms was also the maximum the regulatory framework allowed. The model gave them a false sense of headroom. They couldn't scale. I told them to build a capacity-constrained version of the model that treated volume as a ceiling rather than a variable. It changed the entire strategic picture. For those cases, I switch to scenario planning instead of pure CVP. You map out revenue and cost combinations under different volume ceilings and identify the profit-optimal production level within constraints. It's more work. It's also closer to reality.
Practical Steps to Build a Useful Model
Start by classifying every cost in your P&L as fixed, variable, or mixed. Don't guess. Pull actual accounting data from at least the last 12 months. For mixed costs, use regression if you have enough data points. If you only have quarterly data, use the high-low method and label it as approximate. Define your relevant range. This is the band of volume where your cost assumptions hold. Above or below it, the model drifts. Write that range on the document. I put it right under the title so nobody forgets. Build the base model in a spreadsheet. Link revenue, variable costs, contribution margin, fixed costs, and operating income. Add a data table that shows break-even across a range of assumptions. One for price changes. One for variable cost shifts. One for fixed cost additions. A three-way sensitivity table takes about 20 minutes and saves you from building three separate models later.
When you present it, lead with the break-even point and the margin of safety, not the formula. Margin of safety tells you how far current sales are from the point where you start losing money. That's what decision-makers care about. The algebra is background work. Update it quarterly. Stale CVP models are worse than no model because they create false confidence. I've watched operations teams make hiring decisions and capital expenditure commitments based on models that hadn't been touched in eight months. The world changed. The model didn't.
When to Use Something Else
If your cost structure is heavily variable with minimal fixed overhead, CVP still works but adds less value than other methods. Activity-based costing gives you a clearer picture of what actually drives costs in those environments. If your business has high fixed costs and volatile demand, like seasonal tourism or event ticketing, you're better off using probability-weighted expected value models rather than a single-point break-even estimate. CVP is a starting point, not an endpoint. It forces you to think about cost behavior clearly and identify where your margins come from. That alone makes it worth building. But the moment you treat it as precise prediction, you're using it wrong. The model I use now has four tabs. Base assumptions, sensitivity tables, tiered cost scenarios, and a constraint check where I verify that projected volume actually falls within our relevant range. It takes about 15 minutes to run after the initial setup. The initial build usually takes me two to three hours depending on how clean the source data is. If your data isn't clean, spend the time cleaning it first. A garbage-in CVP model is dangerously wrong, not just barely wrong.