Why most couples blow past their budgets every single month
I used to watch this exact same scene play out over and over at the dinner table during financial planning sessions. Two people who clearly care about each other, both making decent money, somehow still wondering where $400 disappeared to in March. The problem is never one thing. It is a combination of mismatched spending rhythms, untracked shared obligations, and the stubborn assumption that if you just talk about money more often, everything will sort itself out. It does not. A couples financial planning worksheet is really just a single structured document that forces two separate mental models of money onto the same page. You write down income, you list fixed expenses, you allocate discretionary spending, and then you reconcile where the two of you actually agree versus where you silently disagree. That last part is the hard part. The spreadsheet itself is boring. The reconciliation is what separates people who eventually get on the same page from people who keep having the same argument about whether restaurants count as a necessary expense. I built my first one from scratch about ten years ago because I could not find anything that accounted for the weird stuff. Most templates online assume one person earns everything and the other spends it, or they treat dual incomes as just two separate lines with no coordination mechanism. Neither reflects how most modern couples actually function. One partner gets a bonus in November. The other gets paid biweekly while the first is monthly. There is a co-signed car loan, a student payment plan that quietly auto-deducts, and a side hustle that does not show up on any W-2. A blank spreadsheet does not help you organize that.
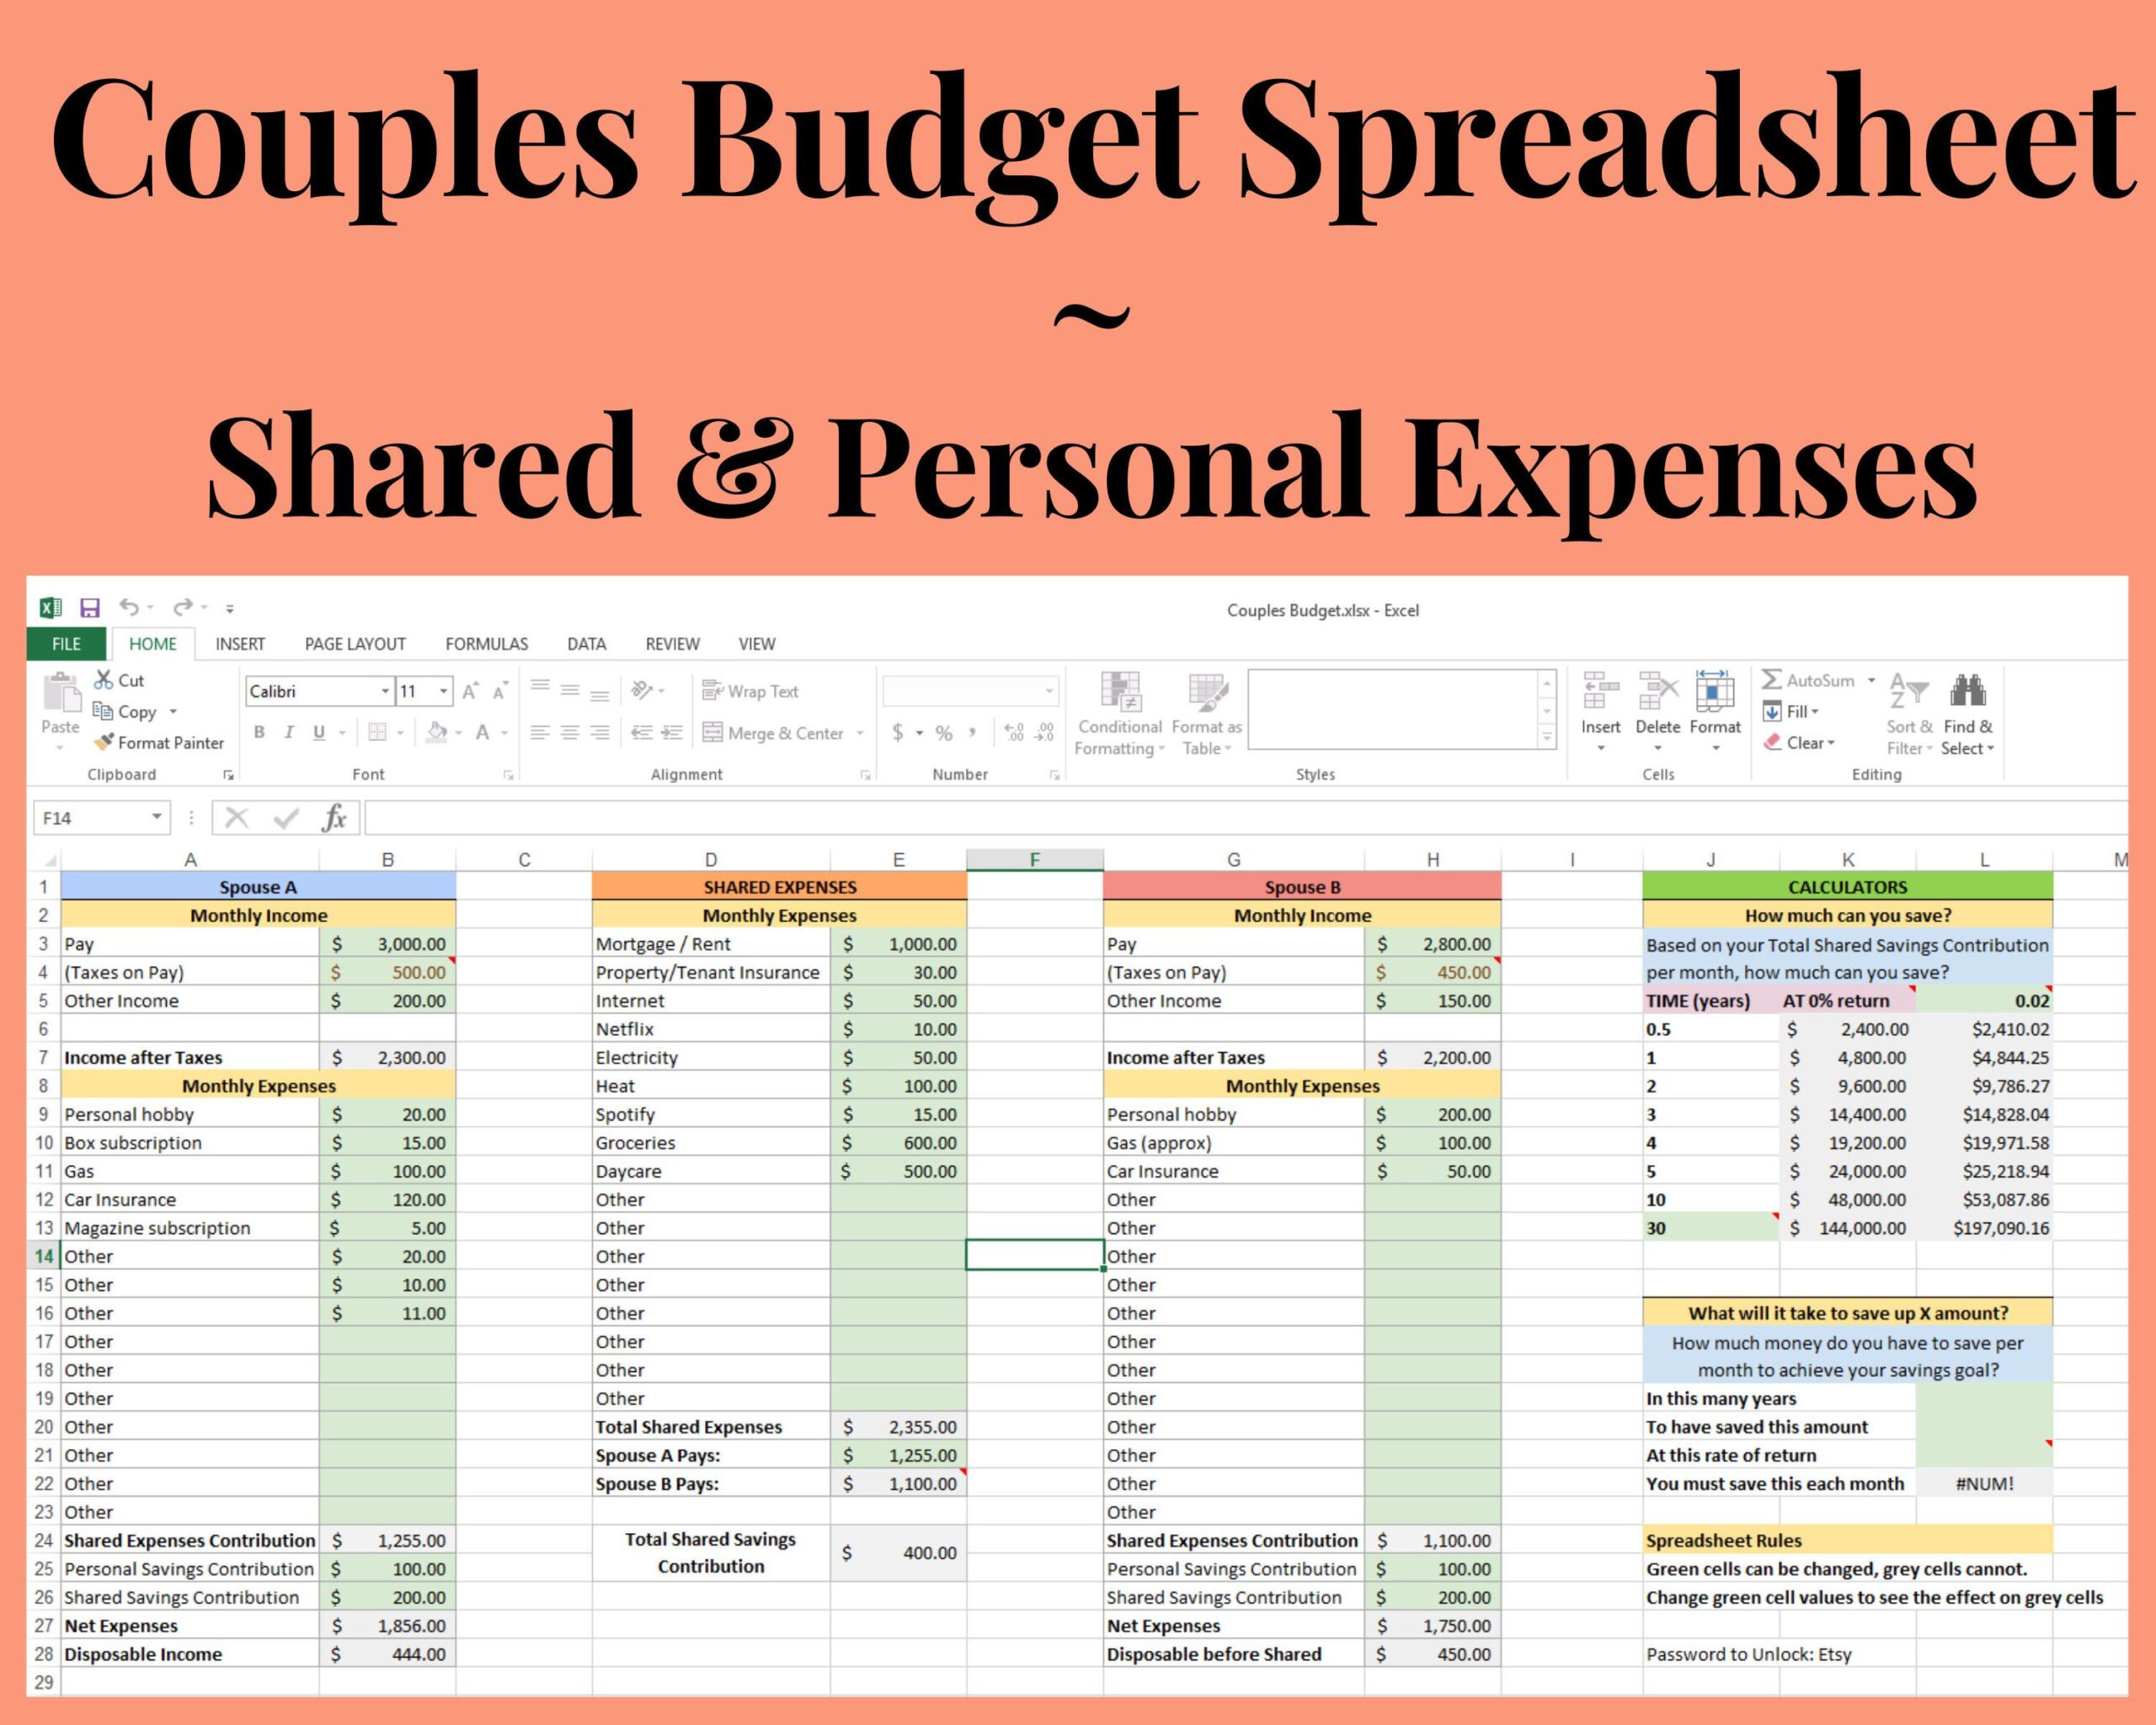
The practical version looks like this. Open a fresh sheet. Row one is combined monthly net income broken down by source and frequency. Row two is fixed obligations: rent or mortgage, utilities, insurance, minimum debt payments, subscriptions you cannot cancel without penalty. Row three is variable shared costs: groceries, gas, childcare, household supplies. Row four is discretionary personal spending for each person individually. Row five is savings and investment contributions, split according to whatever ratio you actually agreed to. Row six is irregular annual expenses divided by twelve so they do not surprise you. I learned the hard way that row six is where most couples fail. You can track every grocery run and streaming service for months and still get crushed by a $1,200 annual water heater repair that hits in July. The workaround is to create a sinking fund line inside the worksheet itself, equal to the annual estimate divided by twelve, and treat it as a non-negotiable fixed cost. I used to tell clients to just save separately for that, but people do not save separately for things that live outside their main budgeting app. Put it in the worksheet where it competes with everything else, and it finally gets protected. There is a counter-intuitive detail that nobody warns you about. The worksheet should list your discretionary personal spending as a fixed number, not a reminder. If you write "entertainment - $200" and leave it vague, you will spend $380 and then feel guilty for the next two weeks. If you write "personal discretionary: $175" in bold and move on with your life, you actually stick to it. The specificity reduces decision fatigue. It also removes the need to justify every coffee to your partner because the amount is already on paper.
Another thing beginners consistently miss: the reconciliation step. Filling out the worksheet once is easy. Sitting down with your partner and going line by line until you both physically nod at every number takes about an hour the first time and fifteen minutes after that. I have seen couples skip this because it is uncomfortable. They fill it out separately and compare results like strangers. That approach always creates conflict because you are comparing conclusions without comparing assumptions. Sit together. Read each line aloud. Ask why a number exists before you move to the next one. The argument you avoid by doing this upfront is the one you would have had three months later when the account is empty. If you want a working version rather than a decorative PDF, I keep a clean Google Sheets template that covers all six rows plus a simple reconciliation column. It auto-calculates the gap between combined income and combined outflows and highlights any month where discretionary personal spending is not yet allocated. You can grab it here: Download the Couples Financial Planning Worksheet. It is free, no email required, and it has a notes column on the right for tracking decisions you made together so you can look back later and remember why you agreed to something. There are real limitations to this approach and I should be blunt about them. The worksheet assumes both partners are sharing full financial transparency, which is not always true. I have worked with people who hide purchases on separate cards or maintain accounts their partner cannot see. A worksheet cannot fix that. It can only expose the gap when you try to fill it out honestly, and exposing the gap is often the first real conversation the couple has ever had about money. That conversation is valuable regardless of how it ends.
Get the Full Details
The second limitation is rigidity. Once you commit to a structure, you tend to follow it even when your life changes. A promotion, a layoff, a child, a move across the country. I once had a client keep using her old worksheet for eight months after she switched to remote work because the document felt like proof that she was still in control. It was not. She was controlling a version of reality that no longer existed. The worksheet worked against her until she deleted half the rows and started over from scratch. That is sometimes the right move. The third limitation is that worksheets do not automate behavior. You can fill one out perfectly and still impulse-buy a $600 jacket on a Tuesday. The tool shows you the consequence after the fact. It does not prevent the action. If you need behavioral friction, you need separate mechanisms: joint accounts with spending caps, pre-authorized transfers to savings before the money hits your checking, or a rule that any purchase over a set amount requires a 48-hour waiting period. The worksheet tells you where the money should go. It does not stop you from sending it somewhere else. For couples who share accounts and want something simpler, a joint budget tracker inside an app like YNAB or EveryDollar might replace the worksheet entirely. For couples who maintain separate finances and only coordinate on shared goals, the worksheet is closer to what you actually need. There is no universal right answer here. There is only the version that matches your actual financial setup and the discipline to update it every month instead of treating it as a one-time exercise you did once during engagement season and then forgot about.
The download link is above. Fill in your real numbers, sit down together, and read every line out loud before you move on. The rest is just repetition.