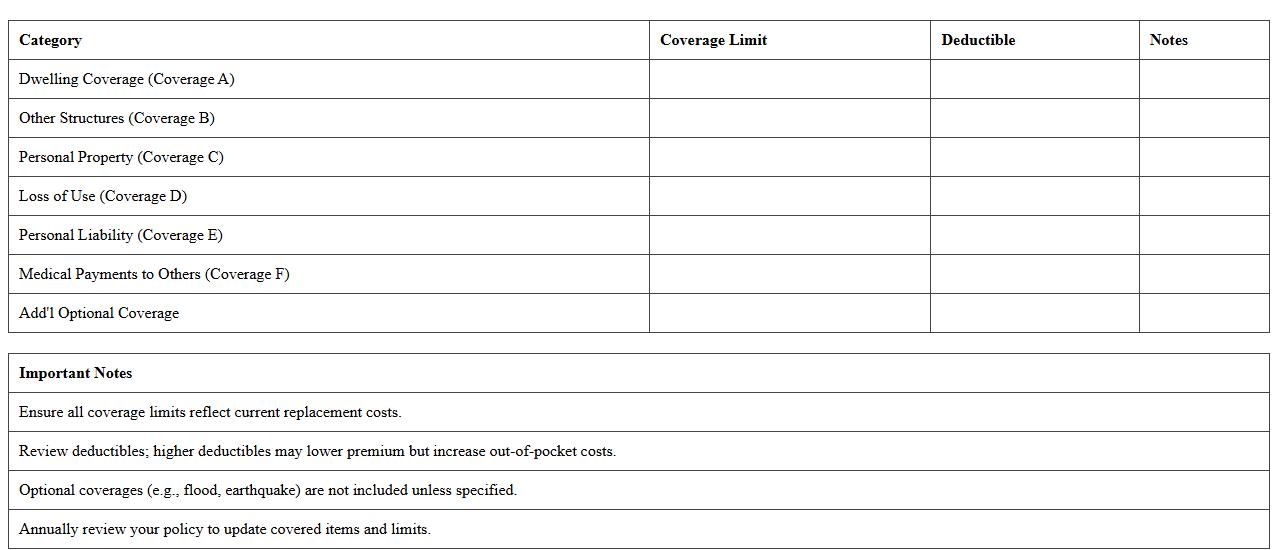
What a Coverage Comparison Worksheet Actually Does
Most people treat this like a simple side-by-side table. It isn't. It's a structured document that lets you map every coverage line from two or more policies against each other, catch the gaps, and flag the overlaps before a client signs anything. I've seen teams skip this step and then spend three weeks untangling duplicate premiums and uncovered risk areas.
The thing nobody tells you is that the worksheet is only as good as the source documents you feed into it. If your policy wording uses different terminology for the same coverage type, the comparison breaks. I learned that the hard way when comparing two commercial liability policies where one called it "products-completed operations" and the other folded it into "contractual liability." They were the same exposure. The worksheet showed a gap. I had to manually cross-reference the definitions and add a note column to reconcile them. After that, I started building a terminology mapping sheet alongside the main worksheet so future comparisons wouldn't require detective work.
Building a Coverage Comparison Worksheet That Won't Waste Your Time
Start by pulling the declarations page and the actual insuring agreement for each policy. Don't rely on summaries or broker pitch decks. Those documents skip the exclusions that matter. Once you have the primary sources, list every coverage part as a row. Typical rows include:
- General liability
- Professional liability / E&O
- Commercial property
- Inland marine
- Workers compensation
- Cyber liability
- Contingent business interruption
- Umbrella / excess
For each row, record the following columns: policy carrier, policy number, coverage limit, deductible, per-occurrence aggregate, annual aggregate, and exclusions that materially affect the coverage. Add a notes column. This column is where the real analysis lives.
I prefer a spreadsheet with color coding. Yellow cells mean the coverage exists in one policy but not the other. Red means there's a conflict between two coverages. Green means they align. It takes about ten minutes to set up the color rules, and then the comparison runs itself visually. Without the colors, you're reading text in twelve different formats and your brain starts merging lines together. You miss the $50,000 sublimit difference between the two D&O policies because both policies say "up to $1 million." One million is the per-claim limit. The other has a $50,000 aggregate for employment practices. That distinction costs someone money if it's not visible at a glance.
Where People Mess This Up
The most common error is comparing only the limits. Limits are easy to read. They're right on the declarations page. Everything else is buried in the body. But the exclusions, the triggers, the territorial scope, and the retroactive dates are what determine whether a claim actually pays. A policy with a higher limit and a narrower exclusion will pay less than a policy with a lower limit and broader terms. I've seen this exact scenario happen with two cyber policies. One had a $5 million limit. The other had $2 million. The $5 million policy excluded first-party ransomware payments above $100,000 without prior consent. The $2 million policy had no such restriction. The cheaper policy ended up being the more useful one for the client's actual risk profile.
Another mistake is treating every policy the same way. A businessowners policy and a standalone general liability policy don't map cleanly. The BOPL bundles property and liability. You can't just list "general liability" once and move on. You have to separate the bundled components and compare them against the standalone equivalents. Otherwise you double-count coverage or miss the fact that the BOPL property section has a coinsurance clause that the standalone policy doesn't.
A Practical Walkthrough
Take two commercial auto policies you're evaluating for a mid-sized logistics company. Policy A is from Carrier X. Policy B is from Carrier Y. Both are stated form policies with similar-looking limits. Open a new sheet. Create your standard columns. Now go line by line through the insuring agreements.
For liability coverage, check the owned, non-owned, and hired vehicle scope. Policy A covers hired vehicles up to $1 million. Policy B covers them up to $500,000 but includes trailer interchange. The worksheet should show this clearly. Don't write it in a single sentence. Put the numbers in the limit column and the trailer interchange detail in the notes column so you can sort and filter later.
For physical damage, check the agreed value versus actual cash value election. Policy A uses agreed value. Policy B uses ACV. That's a material difference on older trucks. Put it in the notes. Add a separate row for rental reimbursement if one policy has it and the other doesn't.
When you finish, run a gap analysis. Highlight any coverage present in one policy and absent in the other. Flag any limits that look identical but have different underlying structures. Then make a recommendation based on the client's fleet mix and risk tolerance, not just the premium difference.
I used to build these worksheets from scratch for every engagement. Now I have a template with preset rows for the most common commercial lines, predefined columns for limits and deductibles, and conditional formatting rules already applied. It cuts a comparison that used to take forty-five minutes down to about twelve minutes for a standard two-policy comparison. Multi-policy scenarios still take longer, but the baseline structure does the heavy lifting.
Limitations of This Approach
A Coverage Comparison Worksheet will not tell you which policy has better claims handling. It won't capture rating nuances like preferred risk discounts or experience modification adjustments unless you manually add those fields. It also assumes you have access to the full policy wording. Brokers sometimes provide redacted declarations-only packets, and in those cases the worksheet becomes speculative. You can note the limitation in the header of the document, but the comparison itself will be incomplete. If you're working from declarations pages only, recommend a full policy review before making any binding recommendation.
There's also the issue of policy endorsements. Endorsements change coverage after the base form is written. If a policy has five separate endorsements modifying liability limits, sublimits, or exclusions, you need to incorporate each one into the worksheet row. I keep a separate endorsement log that references the worksheet rows by line number. It prevents the situation where you note the base form coverage correctly but forget that endorsement 3 reduces the inland marine sublimit by half. That happened to me on a $2.3 million equipment floater comparison. I caught it during underwriting review instead of at binding. The fix was slow but cheap relative to what a missed endorsement would have cost.
When a Coverage Comparison Worksheet Isn't the Right Tool
For highly specialized or niche coverages like pollution liability, directors and officers with side A-B-C structures, or professional liability for healthcare providers, the standard worksheet rows don't map well. The coverage variations are too specific. In those cases, build a custom comparison focused on the unique provisions rather than forcing them into generic rows. It takes more time upfront but saves you from misclassifying coverage.
Gallery Coverage Comparison Worksheet
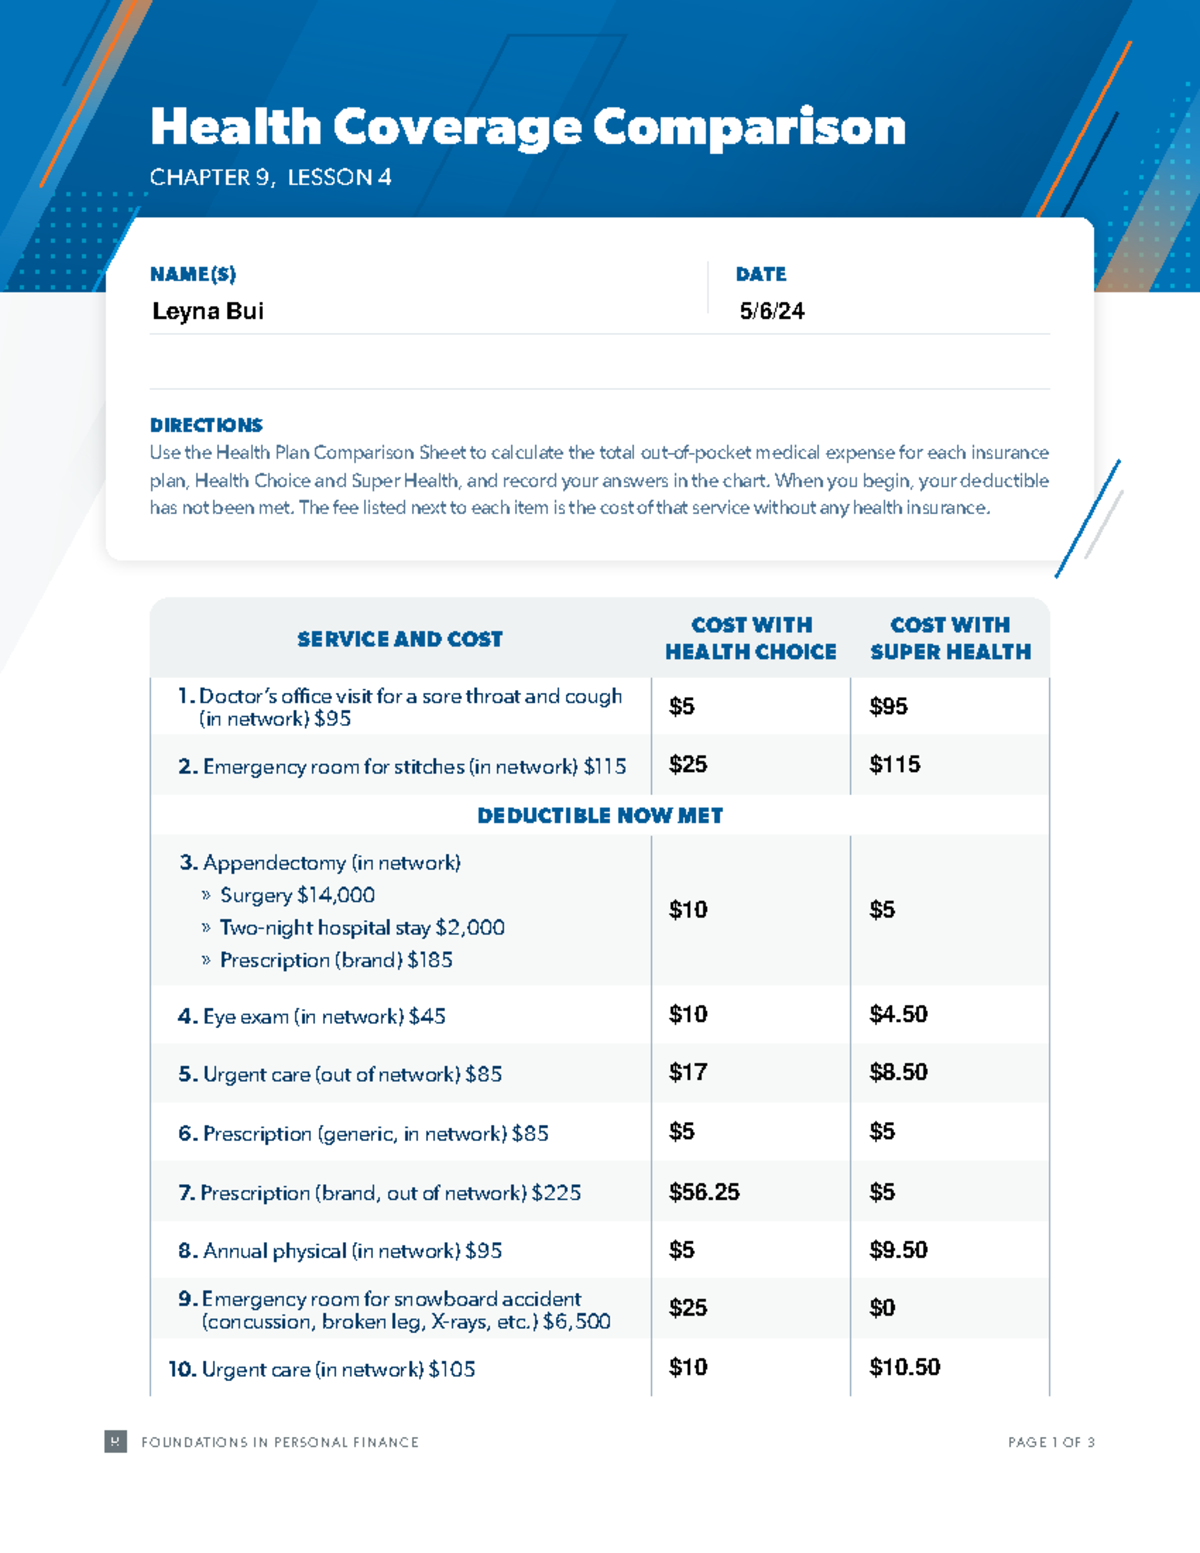
Health Coverage Comparison Worksheet Answer Key - Sheetifyedu Printable
Commercial Insurance Coverage Comparison Template – OHYDHC
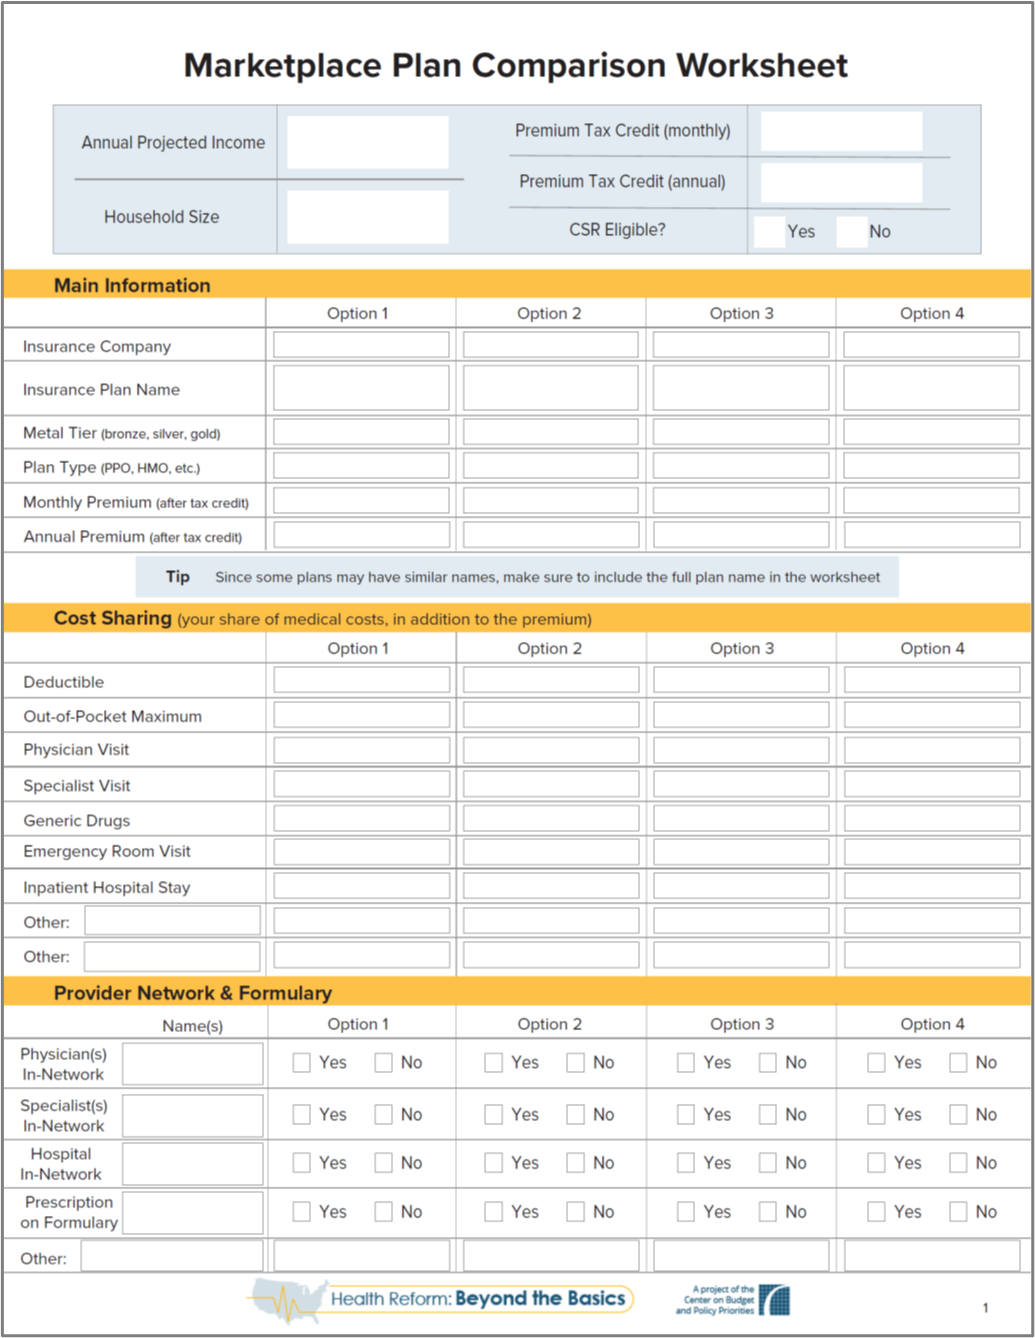
Plan Comparison Worksheet (Available in 8 Languages) | Beyond the Basics
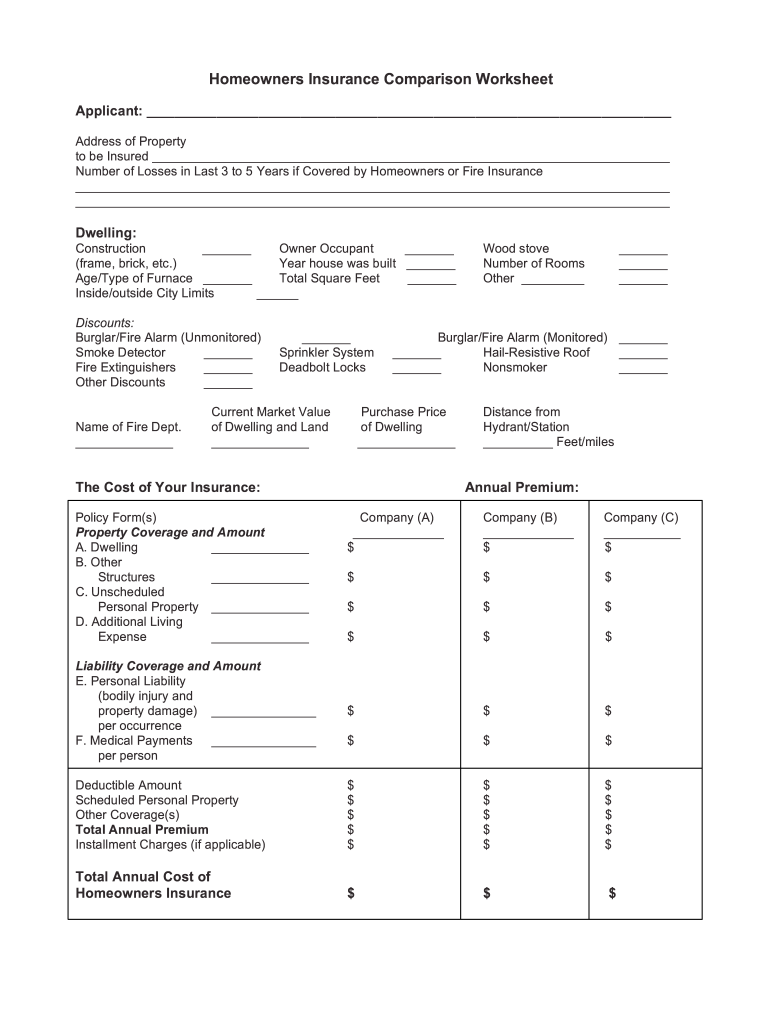
Comprehensive Homeowners Insurance Coverage Comparison Excel Template / exceldir.com
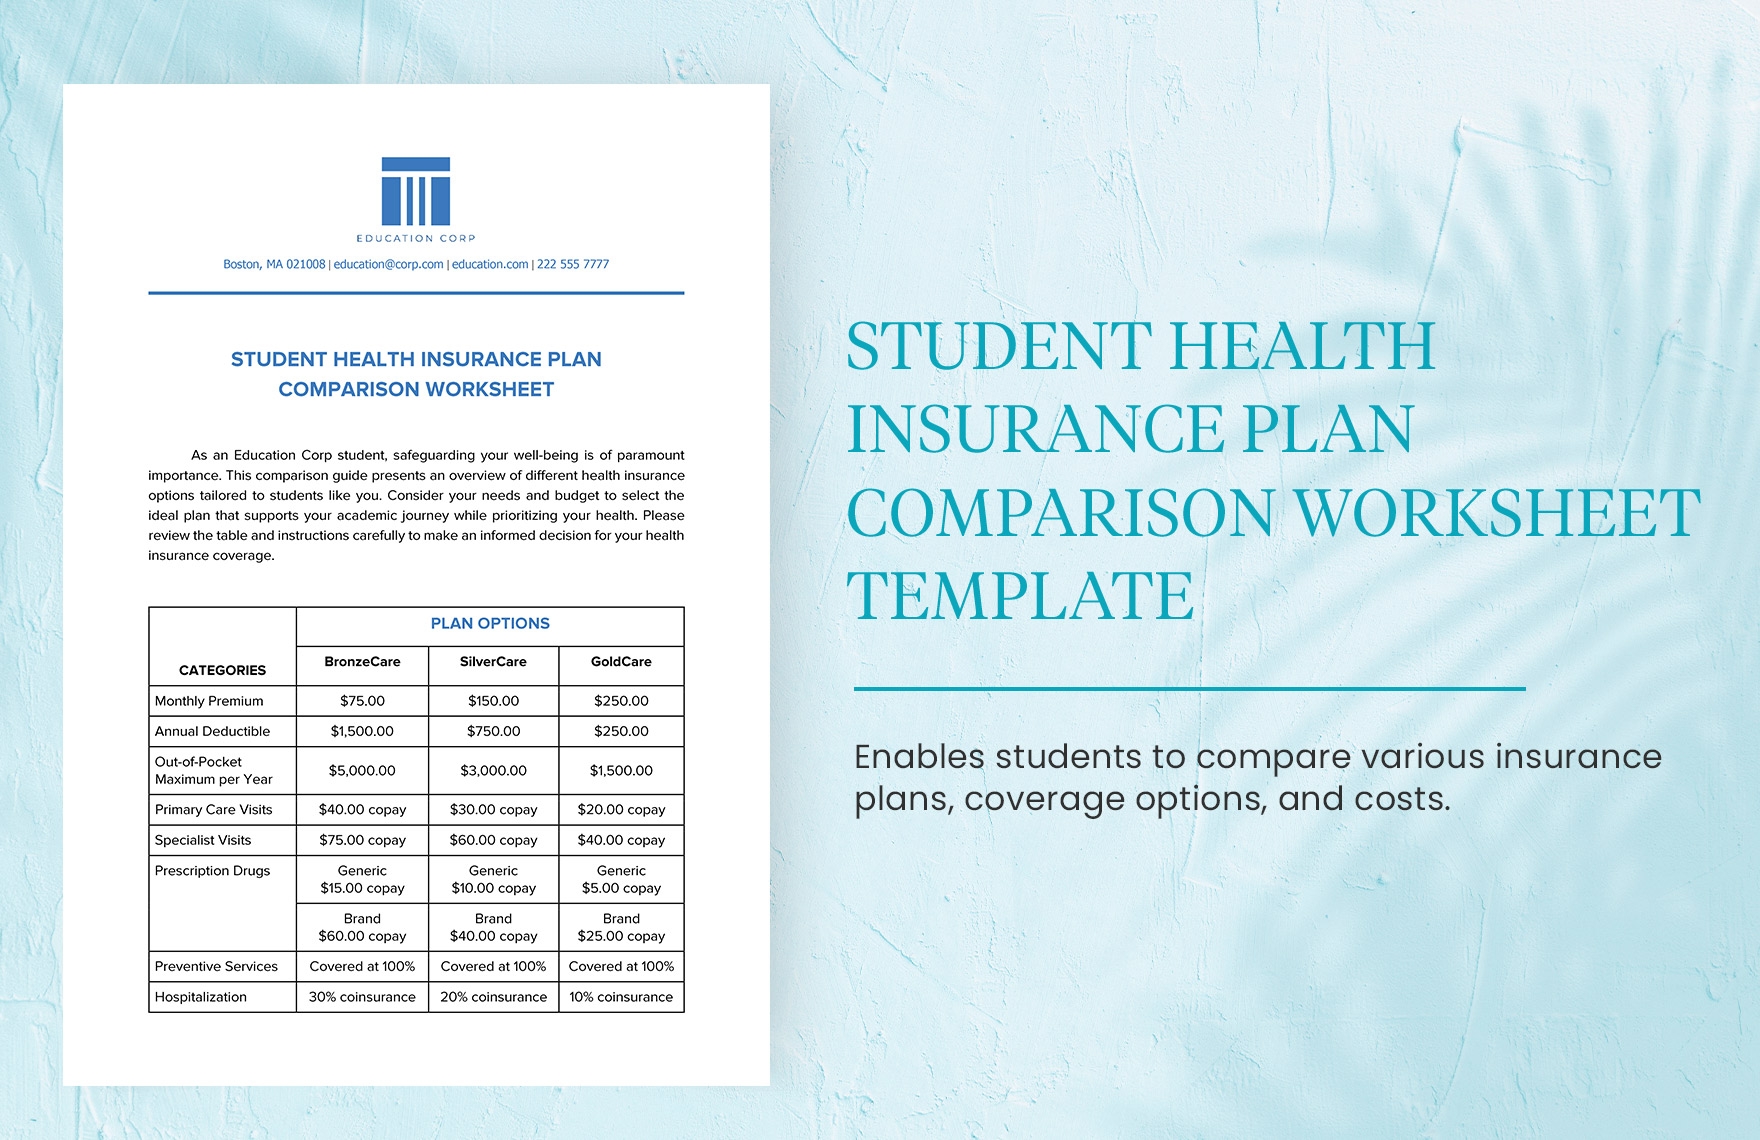
Insurance Coverage Comparison Template