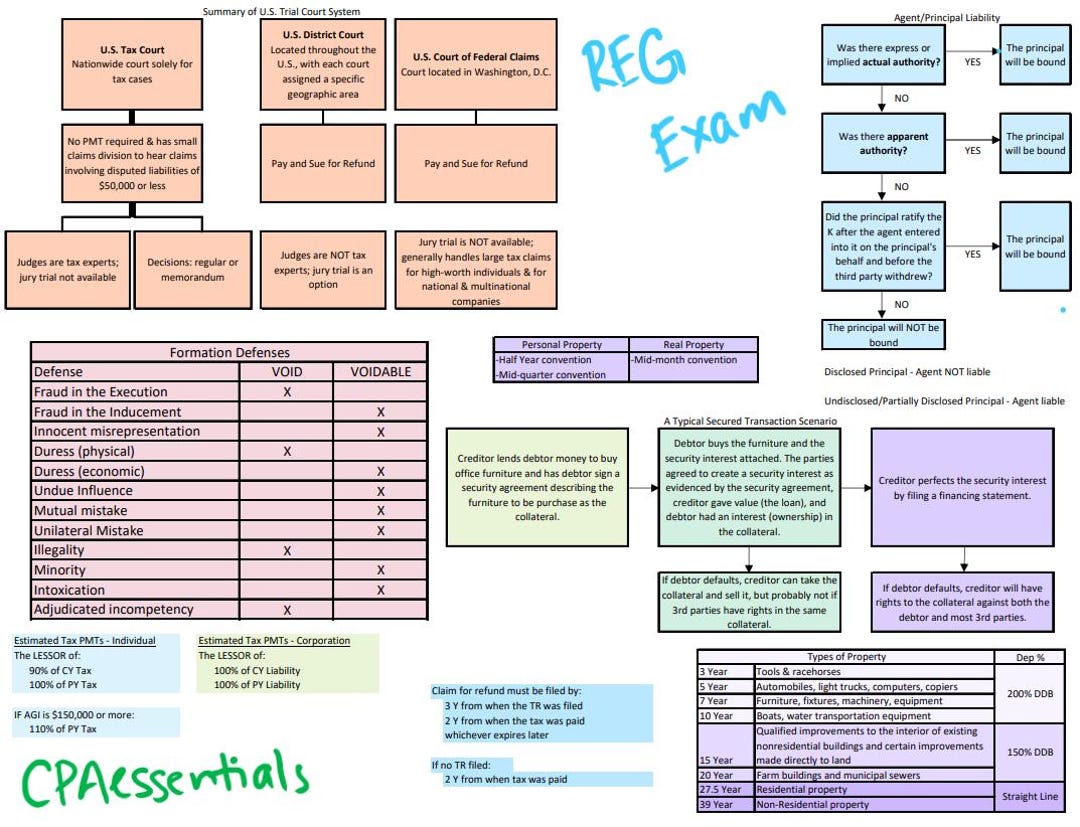
Regulation isn't about memorizing statutes. It's about knowing what the examiners want you to ignore.
I've been writing exam prep materials and reviewing NBECPA test items for longer than I care to admit, and the number one mistake I see people make with a Cpa Exam Regulation Cheat Sheet is using it as a primary study tool instead of a final review mechanism. Regulation tests application, not recall. You can pass this section without ever memorizing IRC Section 179 limits to the digit, provided you understand the underlying framework well enough to work through a multi-part fact pattern under time pressure. When I was studying for my own exam back in 2018, I fell into the trap of creating what I thought was a comprehensive cheat sheet. I spent three weeks compiling every rule, exception, and threshold I could find into a single document. It ended up being over two hundred pages. I never finished reading it before my exam window opened. What actually worked for me was taking that content down to roughly forty pages of decision trees and comparison tables, and then drilling past simulations until my hand moved faster than my brain on the common sequences.
Cpa Exam Regulation Cheat Sheet — What It Actually Should Look Like
A useful cheat sheet for Regulation is not a collection of definitions. It's a set of side-by-side comparisons and flowcharts that force you to make distinctions quickly. The exam loves to throw closely related concepts at you in the same question. Federal income tax concepts that sound identical but have different thresholds depending on whether you're dealing with like-kind exchanges versus involuntary conversions is one of these areas. Business law topics like the differences between corporations and LLCs under state statutes are another. I structured my final version around five categories: federal taxation, business structures, contracts, agency and employment, and professional responsibilities. For each category I created a decision tree that covered the most commonly tested pathways. Instead of writing out the rule for partnership distributions, I mapped out the order of distribution categories with the basis recovery rules attached. When I walk into the exam now, I don't need to recall the entire statute. I follow the tree. The timing matters here. You should be building your cheat sheet during your second or third week of study, after you've already done at least a full pass through a major review course. If you start constructing one on day one, you're just copying the textbook and gaining very little from the process. The cognitive benefit comes from condensing, not from transcribing.
Here's a practical limitation you need to understand upfront. Your actual cheat sheet is going to be significantly less detailed than what you think you need. The National Bar Association simulation software and the AICPA released items use very specific language patterns, and the exam rarely tests the edge cases that fill up those long-form reference guides. The last thing I personally encountered was a question about the standard deduction for dependents in 2022, where the answer depended on whether the dependent had earned versus unearned income and which bracket applied. I had spent twenty minutes the week before memorizing the exact phase-out ranges for every filing status. The exam question only required that I knew the basic earned-plus-thousand rule. That's the nature of this test. One counter-intuitive point that most candidates miss involves the ethical and professional responsibility section. People tend to treat ethics as a minor component and allocate minimal review time to it. The regulation section actually carries a significant ethics weight, and the questions are surprisingly straightforward if you learn the AICPA code framework. The trick is recognizing that these questions often include a scenario where multiple ethical principles seem to apply simultaneously. The correct answer is almost never the one that prioritizes self-interest over public interest, regardless of how reasonable the self-interest argument sounds in the fact pattern. Another common pitfall is assuming that state law questions require knowledge of specific state statutes. They don't. The exam tests general principles of contract and commercial law that apply across jurisdictions. If you see a question referencing a particular state's unusual rule, it's either providing that rule in the question itself or the question is testing whether you can identify the general principle despite the distractor detail.
Get the Full Details
How to Build and Use Your Document Effectively
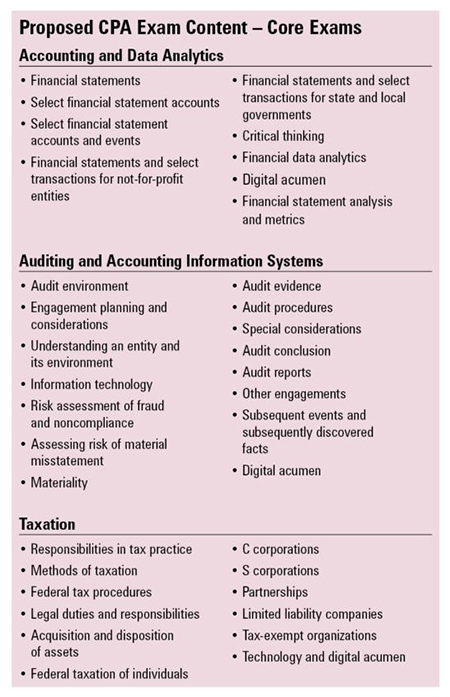
Start by pulling your highest-yield topics from whatever review course you're using. The official content outlines published by the AICPA are publicly available and worth cross-referencing against your materials. Topics like partnership taxation, S corporation elections, and the basics of estate and gift tax consistently carry more weight than areas like fringe benefits or tax-exempt organizations, even though the latter appear frequently in study materials. Format each topic as a comparison table whenever possible. Instead of writing a paragraph explaining the difference between a traditional IRA and a Roth IRA, create a table with rows for contribution limits, deduction rules, withdrawal penalties, and required minimum distributions. Your brain processes these visual contrasts faster than prose during a timed exam situation. Include only current-year thresholds and dollar amounts that you genuinely cannot work through from first principles. For everything else, write the conceptual rule and note the source where the exact number lives. During the exam, if a question requires a specific limit, the value will typically be provided in the simulation interface. Memorizing the exact 2024 section 179 phase-out threshold is a waste of time you'd be better spent understanding when the limitation applies.
I maintain a living document that I update weekly during my study period. Each week I prune content that I've internalized through practice questions and add anything that practice tests consistently expose as weak. By the time I sit for the exam, my sheet is usually somewhere between thirty and fifty pages depending on my font size and spacing preferences. Anything beyond that has ceased to be a review aid and becomes a reference book I'll never read under pressure.
Where to Download a Cpa Exam Regulation Cheat Sheet
There are several sources for pre-made regulation cheat sheets, but the quality varies dramatically. Some commercial providers sell documents that are simply condensed textbooks with no organizational structure, which makes them nearly useless for last-minute review. I've seen candidates try to use these during their final week and spend more time navigating the document than actually learning anything from it. If you don't want to build your own from scratch, look for versions that are organized by decision tree or comparison format rather than by chapter or topic category. A well-structured shared document from a reputable CPA review forum or study group can save you significant time during the condensation phase. The actual act of creating your own version, however, produces better retention than any downloaded file will, regardless of how polished it is. The process of forcing yourself to compress information into a compact format is where the learning happens. The regulation section is the most computationally demanding part of the CPA exam in terms of cognitive load, not because the individual topics are difficult but because the exam continuously shifts between tax codes, business entities, and legal frameworks within single simulation items. A well-built cheat sheet gives you a stable reference point so you can stop rotating those concepts in your head and start working through the questions mechanically. That mechanical fluency is what separates candidates who finish on time from the ones who leave points on the table in the final thirty minutes.

I've watched people fail this section after scoring well on Financial Accounting and Business Concepts. Regulation requires a different study approach entirely, and treating it like a memorization test is the most common reason for that outcome. Build your document early, keep it lean, and practice applying the content under timed conditions rather than reading through it repeatedly. The sheet itself is only as valuable as the practice that accompanies it.