What the CPA Exam Actually Looks Like Now
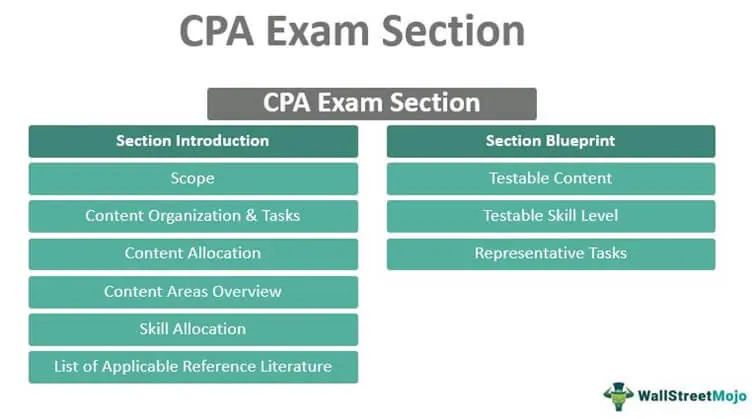
The Big Four changed how they recruit, the NASBA and AICPA adjusted testing windows, and by 2023 the exam had settled into a format that most candidates still find confusing until they actually sit down for a practice test. The shift from the old four-section model to the redesigned uniform CPA exam is not as clean as the promotional material makes it sound. Here is how it works in practice, including the things the review course brochures don't bother mentioning. The exam has four sections, but the content buckets have been reorganized compared to the pre-2024 redesign. The four sections you will register for are: Financial Accounting and Reporting (FAR), Auditing and Attestation (AUD), Business Analysis and Reporting (BAR), and Tax Law and Compliance (REG). BAR and a revised FAR replaced the old Business Environment and Concepts (BEC) section, which was discontinued after 2023. If you saw references to BEC in older materials, those are obsolete. Each section is scored on a 0 to 99 scale, and the passing mark is 75 across all four. That 75 is a scaled score, which means the raw number of correct answers you need varies slightly depending on which question form you receive and how difficult the specific form happens to be that day. This scaling matters more than most candidates realize because it means two people can get different raw accuracy rates and still pass or fail identically.
The question formats are a mix of multiple-choice questions and task-based simulations. FAR and REG each have 62 questions: 36 multiple-choice and 24 simulations. AUD has 51 questions: 33 multiple-choice and 18 simulations. BAR is shorter at 39 questions: 15 multiple-choice and 24 simulations. Time allocations vary accordingly, with FAR and REG getting 4 hours, AUD getting 3 hours, and BAR getting 2 hours. You sit at a Pearson VUE test center or take it remotely under proctoring, depending on your jurisdiction's rules. I ran into a real problem with this structure during my own prep cycle. The BAR section was new enough that practice questions were sparse, and the simulation format was different from what I was used to in FAR and REG. The old BEC simulations had a certain rhythm where you mostly typed short answers or made journal entries. BAR simulations threw cases at you with massive exhibits, financial statements, and data sets you had to parse before answering anything. I wasted about three weeks using outdated BEC-style sim banks because I didn't want to face how thin the BAR material was. The workaround was straightforward but annoying: I stopped trying to force old materials to fit and instead built my own practice by taking publicly available AICPA sample questions, running them through a spreadsheet where I tracked time per simulation, and treating each one like a timed exam attempt rather than a study exercise. That cut my effective prep time for BAR from roughly six weeks down to about three. Here is a detail most people gloss over. The simulation questions are not all the same type. Within FAR and REG you will see tasks like preparing journal entries, reading a balance sheet and filling in a table, or selecting multiple correct options from a long list. In BAR the simulations lean heavily toward analyzing financial data, interpreting ratios, and writing brief memo responses based on provided facts. The BAR sims in particular reward candidates who can work efficiently with large datasets. There is no penalty for wrong answers within the simulations, so leaving something blank is strictly worse than making a guess, but spending forty-five minutes agonizing over one simulation at the expense of five others is a common way to tank a section score.
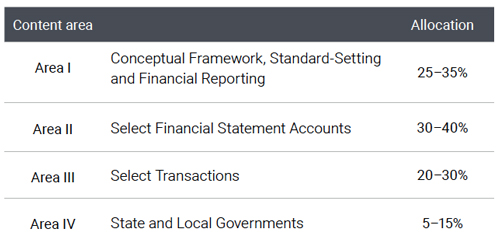
Another counter-intuitive thing about the scoring. You can answer multiple-choice questions in any order, and you can jump between simulation tasks within a section. The timer is cumulative across the entire section, not per question block. This means you can spend twelve minutes on one simulation and three minutes on another, and the system will not stop you. It also means weak test-takers often burn through their time on the questions they enjoy or feel confident about, leaving the harder or less familiar material for the end when there is not enough clock left. I started doing something unusual during my practice runs: I forced myself to do the simulations in the order I would most likely see them on exam day and flagged any that took longer than fifteen minutes, then went back and reviewed the process for those specific ones. This is awkward to simulate alone, but it mirrors the actual pacing pressure better than doing all the multiple-choice first and pretending you have unlimited sim time. The registration process itself adds a layer of friction that the AICPA does not make very visible. You apply through your state board, not directly through the AICPA. Some states require you to complete certain college credits before they even issue an eligibility letter. Others let you apply before finishing all credits and just wait until you graduate to sit the exam. New York and Texas handle this differently, and if you are in a non-standard situation like a foreign transcript evaluation or a credit transfer dispute, that processing delay can add months to your timeline. I learned this the hard way when my state board flagged a course equivalency issue that stalled my ATT by eleven weeks. There is no fast track for that kind of problem. You just wait and keep studying the material you can study in the meantime. One more thing worth mentioning bluntly. The CPA exam is not a perfectly balanced test. FAR has the largest content domain by far, covering financial accounting, government accounting, and not-for-profit topics. Candidates who treat FAR like every other section underestimate it significantly. The exam developers know this, and they weight the section accordingly. A candidate who scores 70 on FAR and 80 on REG might fail the exam overall if FAR drags the weighted average down, because FAR counts for a larger slice of the scoring than some people expect. There is no official weighting breakdown published, but the pattern is consistent enough across candidate reports that it is safe to assume FAR carries more relative impact than the other sections.
Get the Full Details
You can find the current exam content specifications on the AICPA website, and the sample questions are freely available there as well. Those are the most reliable reference for what the questions actually look like, because commercial review courses sometimes smooth out the difficulty or rearrange the order to make practice feel more pleasant than the real exam does. The AICPA materials are deliberately a little harsher because they are meant to calibrate your expectation of what you will face. If you are planning your study sequence, most people do FAR first because it is the biggest section and the foundation for several REG topics. REG covers tax, which overlaps with BAR's business analysis content in small ways but mostly stands alone. BAR is shortest but also the most unfamiliar, so doing it after you have built exam stamina through FAR and REG tends to work better than attacking it cold. AUD has a different style than the rest, with heavy emphasis on ethics, professional responsibilities, and audit procedures. It does not overlap much with anything else, which is both a blessing and a problem because you cannot piggyback your study time from another section. The exam does not require you to pass all four sections within a single testing window or even in a single year, depending on your state's rules. Most states give you eighteen to thirty months to complete all four, and some states have shorter windows. Check your specific state board. The rules changed slightly during and after the pandemic, and a few jurisdictions extended deadlines or made temporary allowances that have since reverted. Assuming your state is back to the standard window is the safest approach unless you have an official notice saying otherwise.
There is no single download link for the exam because it is not something you download. It is administered through Pearson VUE's testing platform, either at a physical center or via on-screen proctoring. What you can and should download are the AICPA exam blueprints, the sample questions for each section, and the candidate guides that explain the scoring methodology. Those documents are freely available and are more useful than any third-party summary. The structure of the CPA exam is functional but imperfect. It covers a lot of ground, it changes slowly enough that you do not have to start over every year, and it is rigorous in the way that matters for entry-level public accounting work. It is also not designed to test everything a practicing CPA would need to know on day one, and it definitely does not test software skills, client communication, or any of the practical abilities you develop in your first job. That is not a flaw in the exam structure so much as it is a limitation of any licensing exam. You pass the CPA exam, you get the credential, and then you learn the rest on the job. The exam tells you whether you can handle the technical baseline. It does not tell you whether you will be good at the work itself.