Writing a CPA Letter for Use of Business Funds
A CPA letter for use of business funds is a document your accountant signs to confirm that money you're withdrawing from a business account is legitimately for business purposes. Lenders, auditors, and sometimes the IRS want this when you need to prove transactions aren't personal withdrawals masquerading as business expenses. I've written dozens of these over the years and the process is straightforward if you know what's actually expected. Here's how to get it done without wasting your accountant's time or yours.
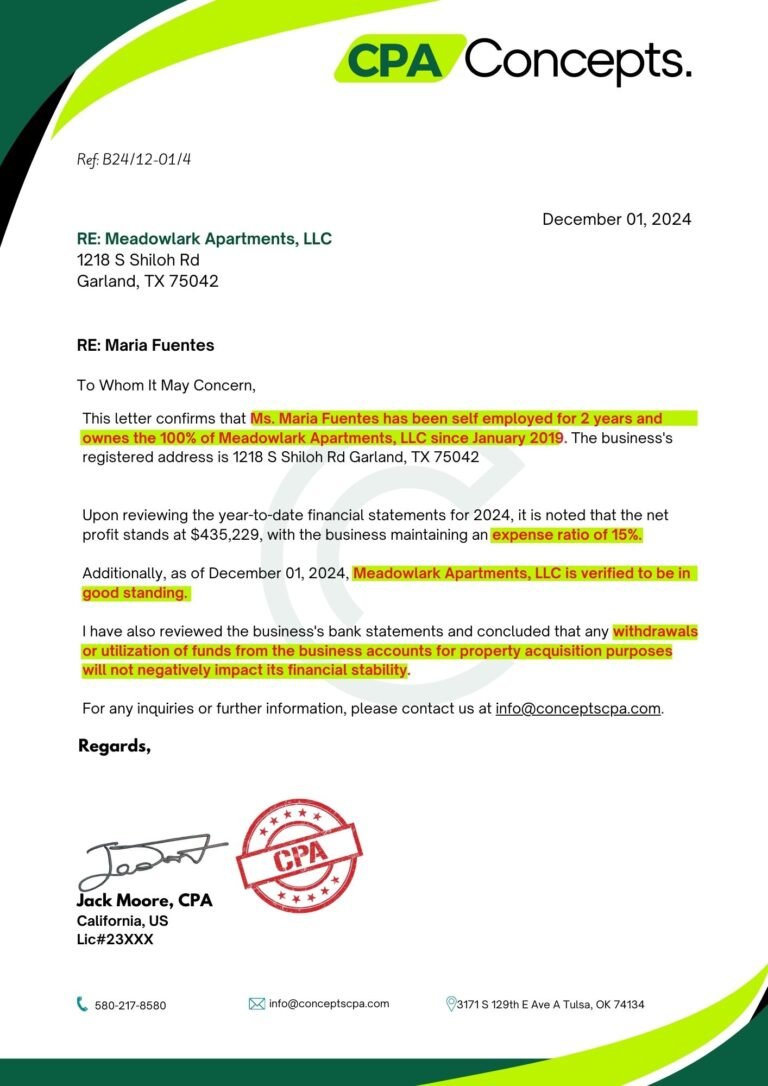
Cpa Letter For Use Of Business Funds Sample
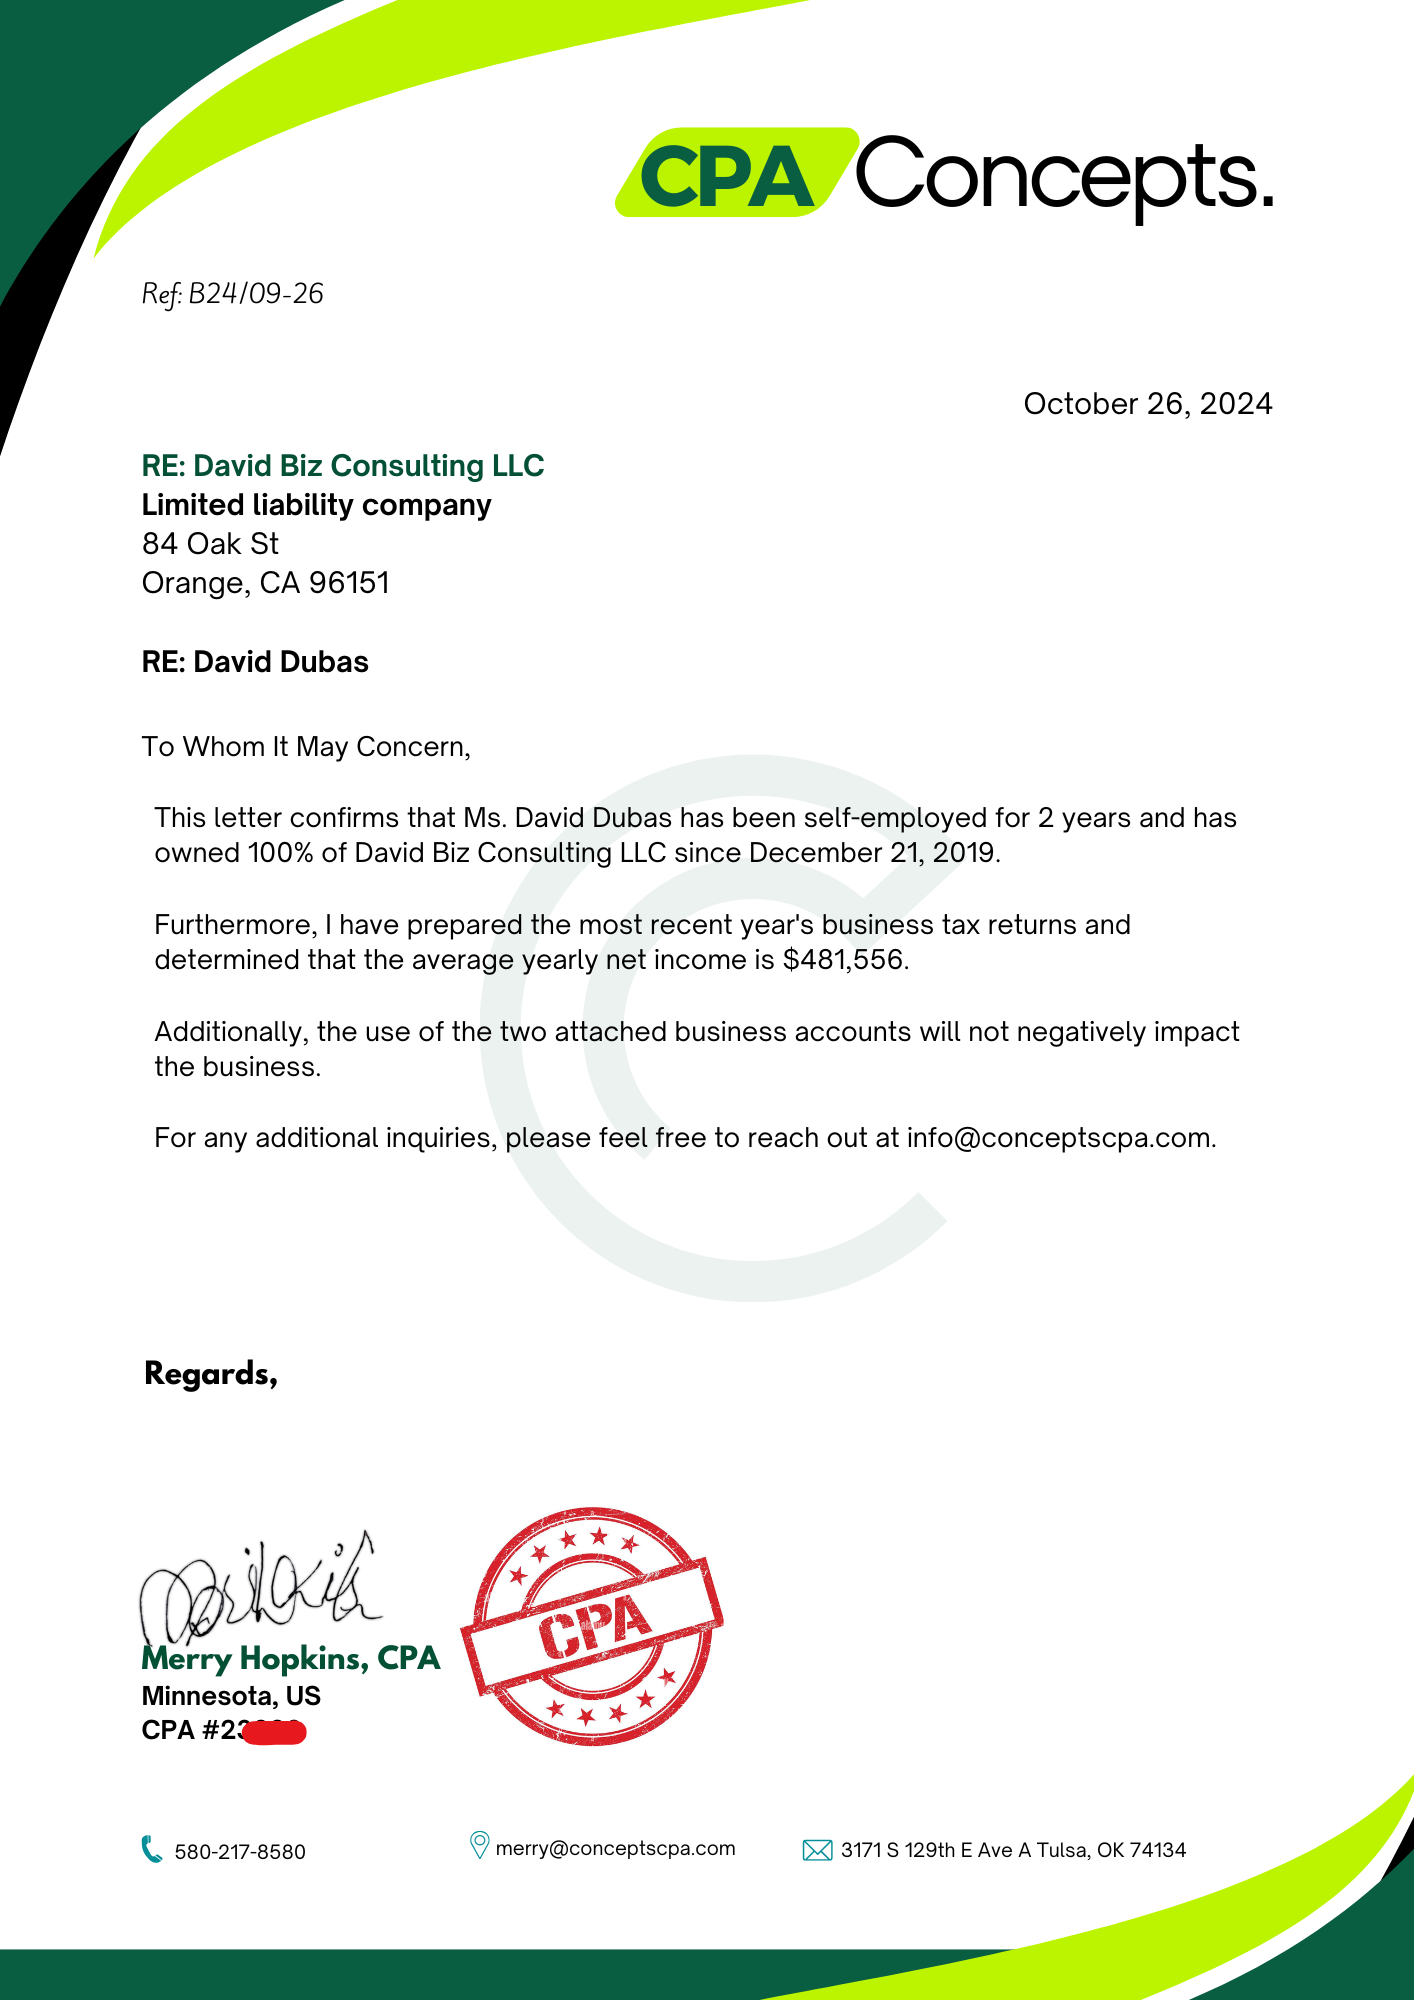
Most CPAs have a template they already use. Don't make them draft something from scratch. The standard letter includes your business name, your name as the owner or authorized signatory, the specific date or period of the transaction, the dollar amount being moved, a brief description of the business purpose, and a statement confirming the funds were used exclusively for business operations. Some lenders want it on the CPA's letterhead. Some don't care. Just ask before you send it off. I once had a situation where a lender rejected a perfectly valid letter because the CPA hadn't specified the exact account numbers involved in the transfer. The letter said "operating expenses" generally but the underwriter wanted line-level detail showing the money went from account ending 4471 to a vendor payment for equipment. It took three days and two follow-up emails to get a revised version. My workaround was simple: I started including the source account, destination account, and vendor payee name directly in the letter itself rather than letting the CPA fill in those blanks verbally. It cut revision cycles from average of two to zero on subsequent requests. The actual structure looks like this. You state the date of the withdrawal. You state the amount. You identify the business purpose with enough specificity that someone reading it five years later could understand what happened. You include a sentence where the CPA affirms they've reviewed supporting documentation. Then you sign it and have your CPA sign it with their license number and state of licensure included.
One thing beginners consistently mess up is the purpose description. Writing "business purposes" is too vague. The letter needs to say what those purposes actually are. "Payment for commercial insurance premium on policy number CI-2024-8841" is the kind of detail that prevents questions. "Office supplies" gets you a follow-up request. "Equipment purchase for fleet vehicle replacement" is better still. The more precise you are upfront, the faster the whole thing moves through review. There's a nuance that most people don't realize. A CPA letter for use of business funds is not the same thing as an audit opinion or a review engagement letter. Some businesses confuse the two and send the wrong document. An audit opinion covers financial statements as a whole. This letter covers a specific transaction or a defined set of transactions. Your CPA needs to know which one is being requested. If you send a sample that shows an audit letter format when what's needed is a transaction-specific confirmation, it'll get returned and you'll be starting over. Another practical detail: some CPAs will refuse to sign these letters if the underlying transaction isn't properly documented in your books. This isn't them being difficult. If the expense doesn't have an invoice, receipt, or board resolution backing it up, signing a letter that confirms business use could expose them to liability. Before you even ask your CPA, make sure the transaction has documentation. It saves everyone time and it keeps the relationship from getting strained over something that should have been caught earlier.
Get the Full Details
Turnaround time varies. A responsive CPA with your file organized can turn this around in one to two business days. If your books are messy and they have to spend time reconstructing what happened, expect three to five days and possibly an additional hour or two of billing at their standard rate. I'd recommend setting aside about $150 to $300 for the CPA's time on this, though rates vary by market and complexity. If you need this quickly and your current CPA is backed up, some firms offer expedited service for a higher fee. Worth it if a lender has a hard deadline. Not worth it if you can plan ahead. One edge case worth noting. If the business funds were used for a purpose that sits in a gray area between personal and business use, your CPA may decline to sign. I've seen this with things like vehicle usage where the car is registered to the business but personally driven most of the time, or home office expenses that don't meet the exclusive use requirement. In those situations, the letter either won't come through or it'll come through with qualifying language that undermines whatever you're trying to prove. The fix is usually to restructure the arrangement so the business use is clearly documented and defensible before you ask for the letter in the first place.
For a sample, the letter should be brief. One page is standard. Two pages max unless you're covering multiple transactions across a long period, in which case a summary schedule attached to the main letter works fine. Keep the language factual. Avoid words like "approximately" or "believed to be" unless the CPA actually lacks certainty about the amount. Precision matters here more than it does in most business correspondence. Here's a straightforward structure you can adapt: Date. To whom it may concern. I am writing to confirm that on [date], [business name] withdrew [amount] from [account description] for the purpose of [specific business purpose]. This transaction is supported by [invoice/receipt/documentation reference]. The funds were used exclusively for business operations. Please contact me if you require additional information. Sincerely, [CPA name], [license number], [state], [contact information].
That's it. Nothing fancy. The details you fill in are what determine whether the letter actually does its job. Make sure those details are accurate and complete before you send it anywhere. Some businesses also get asked for these letters when applying for loans, proving eligibility for certain programs, or defending transactions during an audit. The format doesn't change much between use cases. What changes is how strictly the receiving party scrutinizes the language. A bank underwriter will read it differently than an IRS agent. Adjust your level of detail based on who's on the other end. Keep a copy of every letter you send. Not just for your records. If the same lender asks for proof again six months later, having the original makes it easier to request a revised version quickly rather than starting from scratch.