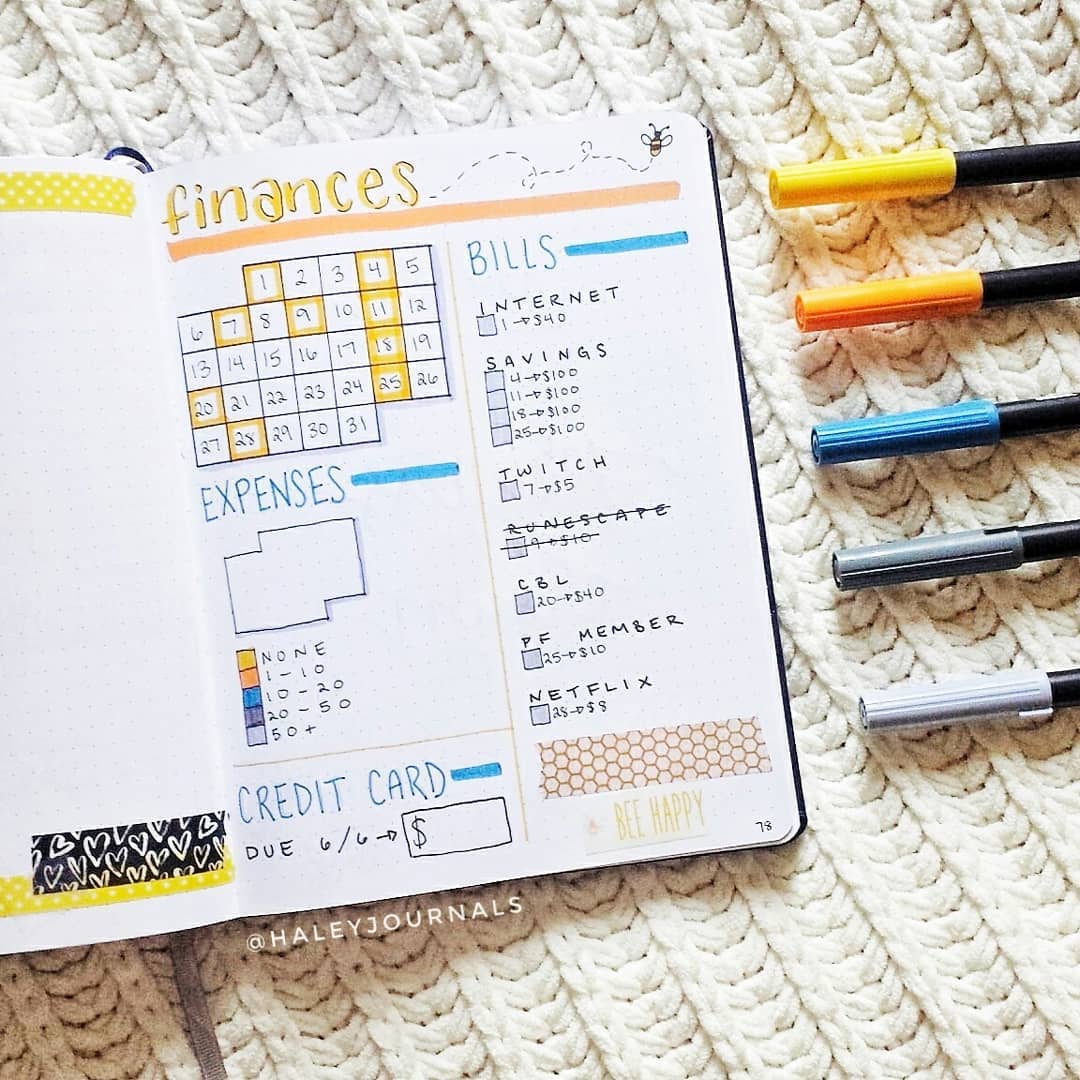
Setting Up a Finance Journal That Actually Sticks
A finance journal is just a place you write down money decisions before they happen and results after they happen. The reason most beginners fail isn't the system, it's the friction. If the journal takes more than thirty seconds to open and fill out, you won't use it. That's the first thing I learned when I tried to track my own spending across four different apps and three spreadsheets. Creative finance here means tracking non-traditional income streams, side hustles, debt payoff strategies, and unconventional savings methods alongside your regular budget. Most beginner journals only handle paycheck versus bills. That leaves half your money life untracked. I started with a simple spreadsheet because I wanted everything in one place. It took me fourteen minutes to log a single week of data. I switched to a pre-built template that uses dropdown menus and cut that down to about ninety seconds per entry. The structure I use has three sections. First is the weekly setup where I list expected income sources and fixed expenses. Second is daily transaction logging, which I do right after the purchase or deposit happens. Third is a monthly review where I compare actual numbers against projections. The monthly review is where the pattern recognition happens. You'll start seeing things like your Uber Eats spending correlates with late work nights, or that side hustle income dips every third month when client seasons shift.
I ran into a specific problem with this about eight months in. I was tracking a rental property as an income stream, but the expenses were messy. Repairs, vacancy costs, property management fees, mortgage interest. They didn't fit into standard expense categories. The workaround was creating a custom category called "miscellaneous property costs" and attaching receipts to each entry using a free file linking feature in Notion. Took me about ten minutes to set up, saves me hours during tax season.
What You Actually Need to Track
Income from all sources, not just your W-2. Side gigs, cash jobs, dividend deposits, gift money, crypto gains, anything that crosses your account gets logged. I used to skip small cash income. Then I realized over a year I'd missed roughly $4,200 in odd jobs and resale profits. That changed how I treated every dollar regardless of size. Fixed expenses first, then variable. Rent, car payment, insurance, subscriptions. Then everything else. This order matters because fixed costs anchor your baseline and you need to know what's locked in before you decide what's discretionary. Variable spending is where the creative part comes in. You're looking for patterns you can shift, not just categories to label. Debt progress on every obligation. Minimum payment, extra payment, remaining balance, interest rate. Tracking this monthly shows you which debts are actually moving versus which are barely changing. I had two cards at different rates that looked identical on paper. The journal revealed one was eating up twice as much of my available cash each month once I factored in compounding. That shifted my payoff order immediately.
Get the Full Details
Tools and Templates
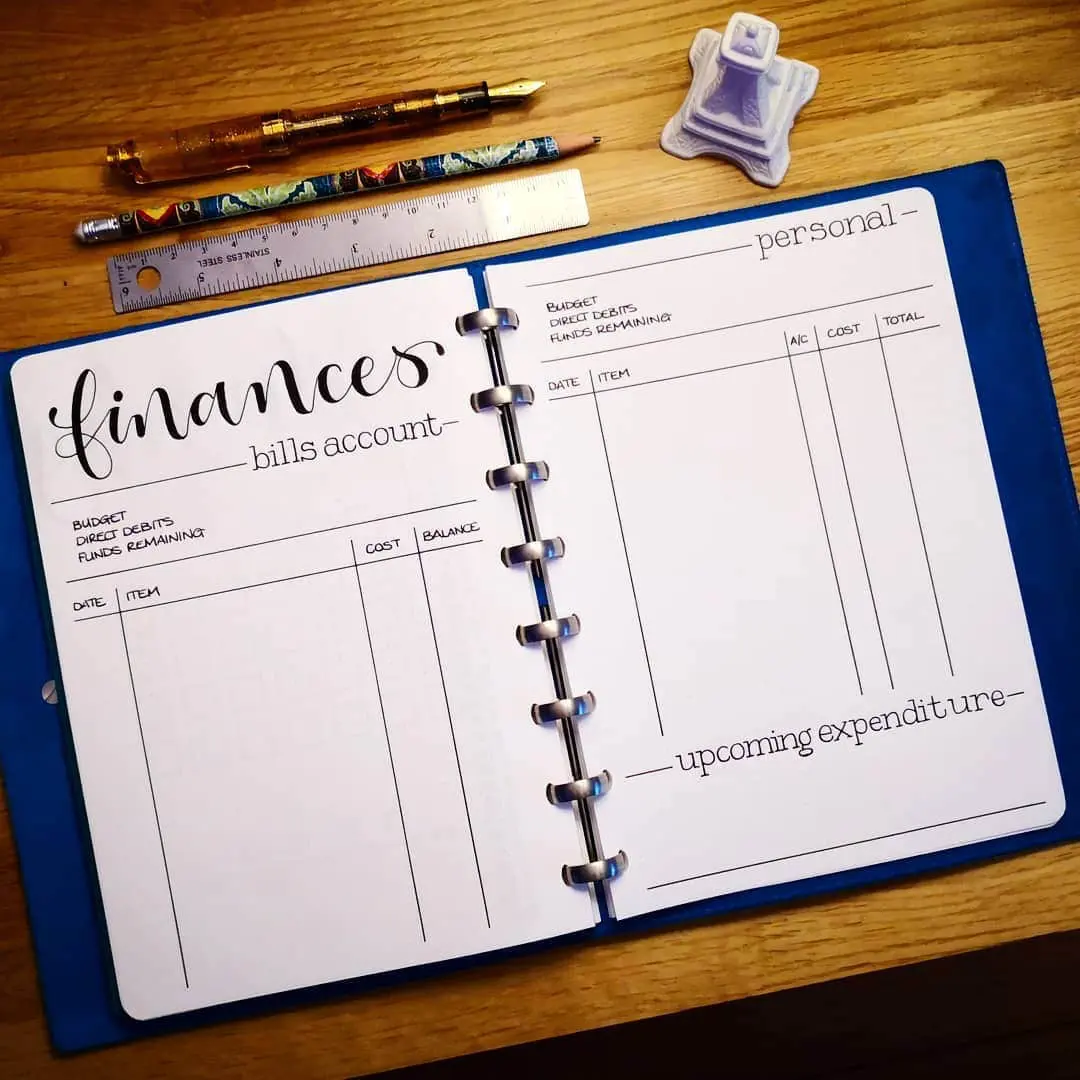
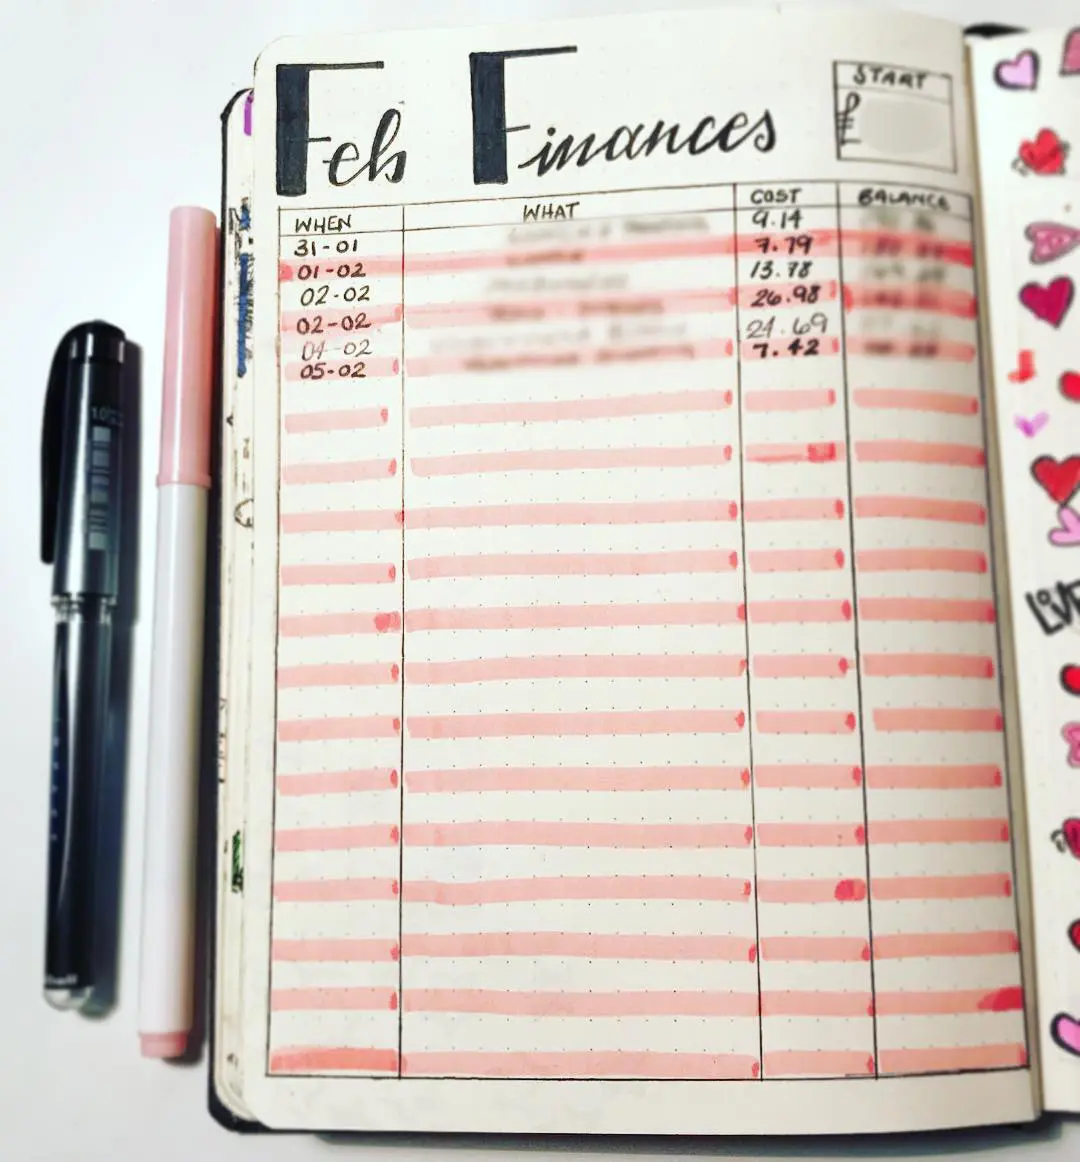
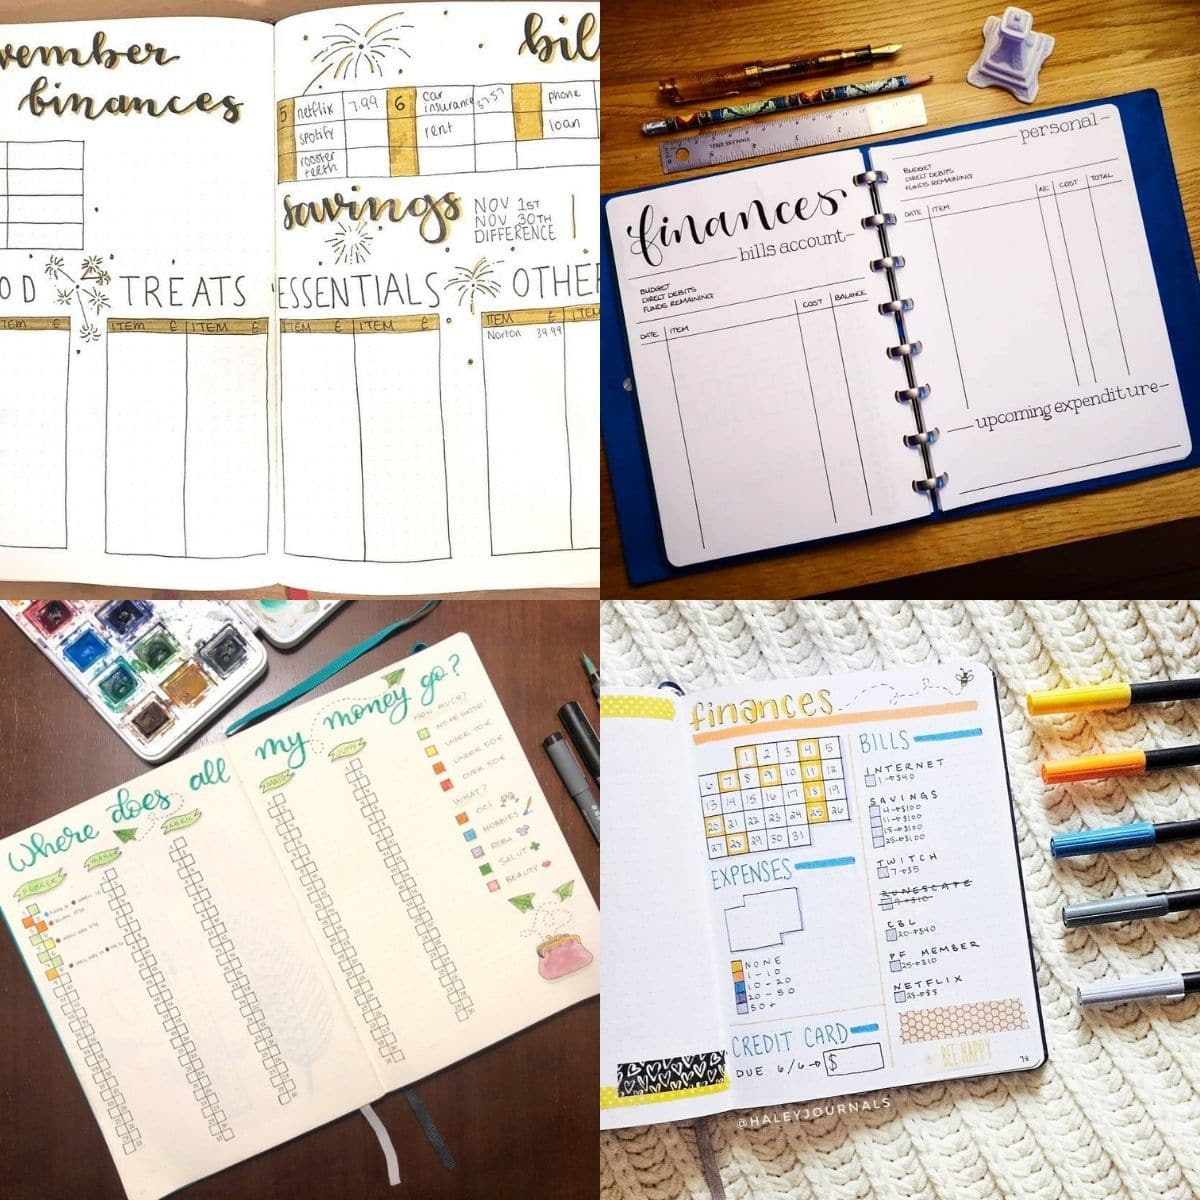
There are free templates available that handle most of this structure already. The ones worth using have conditional formatting so entries turn red when they exceed your target and green when under. That visual feedback alone keeps you honest without needing to calculate anything yourself. I've also seen people use Google Sheets with data validation to prevent typos from breaking formulas. Takes five minutes to set up and eliminates about eighty percent of correction work down the line. If you prefer physical notebooks, get one with pre-printed categories rather than blank pages. The time saved searching for the right section to write in adds up. My first notebook was completely blank and I spent more time deciding where to put things than actually tracking. That didn't last long. Apps exist too but they introduce their own problems. Subscription fatigue, data export limitations, and the temptation to automate everything until you stop actually reading what's happening. I've used both and found the sweet spot is a simple digital tool you control the data on, plus a monthly recap you write by hand to force engagement with the numbers.
Common Mistakes That Break the System
Starting with too many categories. Beginners often create twenty-five tracking buckets right away. By week three they're ignoring twelve of them because maintenance became unsustainable. Start with six to eight main categories and expand only when a pattern demands it. Your journal should grow organically, not all at once. Another mistake is tracking without reviewing. Logging transactions and never looking back is just expensive digital hoarding. The monthly review is non-negotiable. Even twenty minutes comparing actual versus planned spending will surface things you'd miss otherwise. I found out through this process that I was paying $38 monthly in banking fees I'd overlooked for eleven months because they were buried in transaction descriptions. Some systems fail completely when life gets complicated. If you're between jobs, dealing with medical bills, or running a business with irregular cash flow, rigid weekly budgets break down. In those cases switch to a rolling three-month average approach where you track net position changes rather than enforcing weekly limits. It's less precise but it survives reality better.
The honest limitation here is that a finance journal doesn't fix income problems. It reveals them faster than most other methods. If your numbers consistently show you can't cover expenses, the journal tells you that clearly instead of letting you pretend everything's fine through March. That clarity is uncomfortable sometimes but it's the only way to make real decisions about what comes next. There's also a point of diminishing returns where tracking becomes obsessive rather than useful. I knew someone who spent four hours every Sunday managing their budget spreadsheet instead of doing activities that would improve their actual financial situation. The journal became the job instead of the tool. That's worth watching for.