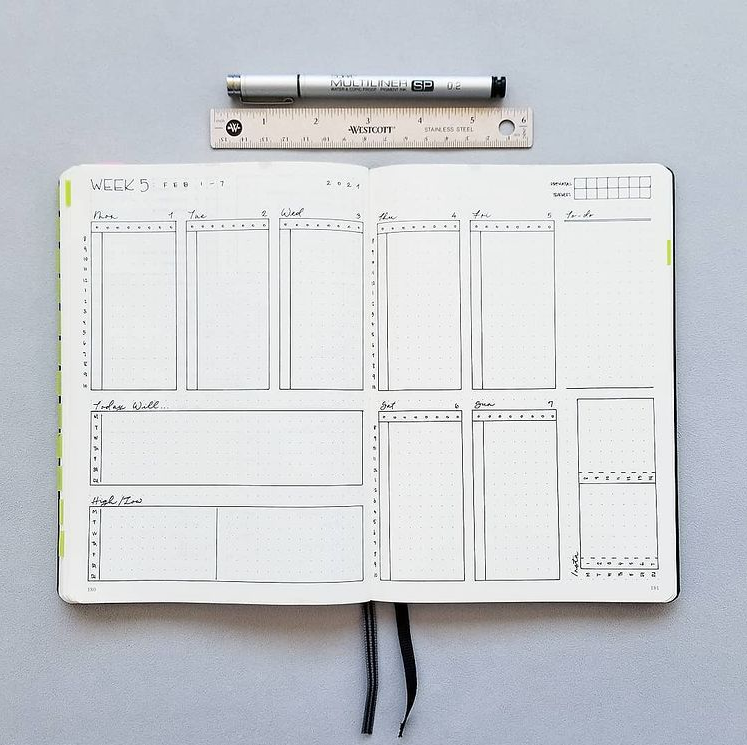
The Problem With Most Weekly Finance Spreads
Most people build weekly spreads that look nice and then abandon them within three weeks. The problem isn't the concept. It's that they copy a template that was designed for someone with a completely different income structure, expense load, or tracking habits. The Creative Finance Journal Weekly Spread that actually works for you needs to be broken down first by what you spend money on each week, not by some aesthetic standard. I spent about six months adjusting my own before it stuck. I tried bullet journals first, then Notion, then a spreadsheet. The version I ended up using sits in Google Sheets because it auto-updates from my bank export and doesn't require me to open a separate app every Sunday night.
What the Creative Finance Journal Weekly Spread Actually Is
It's a single-page layout that tracks your income against your outflows for one seven-day period, organized by category rather than by transaction. The difference from a standard budget is that it's built for a journal-style review where you write notes about what happened that week, not just number-crunching. You get a snapshot of cash flow, a spot for debt payoff tracking, and a section where you log decisions you made about money that week. The structure has five main blocks. The top block shows your projected income minus automatic fixed expenses. Below that is your variable spending tracker, broken into grocery, transportation, dining, subscriptions, and discretionary. Then there's a debt snowball or avalanche tracker so you can see which account is getting paid down. A small notes section at the bottom captures what you remember about the week, and finally a rolling savings goal bar so you can see progress in real time. I built mine in a 48-column grid. It sounds like a lot, but most of those columns are helper columns for SUMIF formulas. The visible part only uses about twelve columns. Everything else stays hidden so the page doesn't look cluttered when you open it each week.
How to Build One From Scratch
Start by listing every expense category that cost you more than fifty dollars last month. Those are your fixed buckets. Everything below that threshold goes into a catch-all line called miscellaneous until you notice a pattern. I usually leave about three lines between major categories so I can add subcategories later without rearranging the whole sheet. For the income section, put your net pay first, then any side income on a separate line so they don't get conflated. I learned that the hard way. I had a client payment that came in two weeks late and it threw off my entire week because I'd lumped it into my regular salary line. Once I separated them, my projections stayed accurate even when freelance work was unpredictable. The variable spending section should use data validation dropdowns for categories. This forces consistency. Without it, you'll write "groceries" one week and "food" the next and your pivot tables will break when you try to aggregate across weeks. I set the dropdown to a list of six categories and color-code each row so the sheet is readable at a glance without needing to read every label.
Get the Full Details
For the debt tracker, I use a simple formula that takes your minimum payment and divides it by your total balance to show a percentage paid off. This gives you a visual indicator that numbers alone don't provide. Seeing debt drop from twelve percent to eleven percent in a single cell is more motivating than looking at a raw dollar figure that hasn't changed much.
Where It Gets Complicated
The edge case that almost broke my system was biweekly pay versus weekly tracking. My paycheck comes every other Friday, but the sheet is set up for seven-day weeks. For three weeks out of every month, I had zero income flowing into the tracker while my fixed expenses kept generating outflow rows. I ended up with phantom deficits that looked alarming but were completely normal. The fix was a helper column that flags which weeks actually have income and multiplies the deficit by a ratio based on pay frequency. Instead of showing a negative balance during off-weeks, the sheet now shows a projected weekly burn rate that accounts for the pay gap. It took me about forty minutes to set up, and it eliminated the panic I used to feel every third Sunday evening. Another issue people hit is the subscription trap. When you track subscriptions in a weekly spread, you tend to miss annual charges because they don't appear every week. I solve this by adding a separate annual calendar column at the bottom of the sheet. It pulls dates from a master list and highlights anything due within the current tracking window. This catches things like car insurance renewals and software annual fees that would otherwise disappear until the bank statement forced a memory.
What This Approach Doesn't Do Well
A weekly spread is not going to help you with month-over-month trend analysis. The granularity is too fine and the categories shift as you add or remove things. If you need to compare September spending to August spending, you're better off with a monthly sheet that uses consistent categories and roll-forward logic. The weekly format sacrifices long-term comparability for short-term behavioral feedback, and that trade-off is worth understanding before you commit to it. It also requires actual discipline every Sunday. If you skip a week, the cascade effect makes the next two weeks harder to complete because you have to backfill data from your bank statement instead of just entering transactions as they happen. I've missed two consecutive weeks twice in the last year, and both times it took me roughly forty-five minutes to reconstruct the data instead of the usual fifteen. That delay is a real cost that most people don't plan for. For anyone with highly variable income like commission-based work or seasonal employment, a pure weekly spread will generate false signals about your financial health. In those cases, I'd recommend a rolling four-week moving average view layered on top of the weekly tracker. It smooths out the spikes and valleys without abandoning the weekly detail that keeps you accountable.
How to Get It Done This Week
Open a blank Google Sheet. Set column A through L as your visible area. Put your weekly date range in row one. Create the five sections I described above and fill them with placeholder formulas. Test it with one full week of real data before you try to make it pretty. The formatting can wait. Getting the logic right matters more. Once you've run two weeks through the system, review which categories had the most errors or needed reclassification. Adjust then. Don't redesign the whole thing again. The goal is a functional tool you can maintain, not a perfect template you abandon after the initial excitement fades. The Creative Finance Journal Weekly Spread works because it combines accountability with reflection. The numbers tell you what happened. The notes section tells you why. Together they give you information most spreadsheets never capture, and that gap is where real financial behavior change actually happens.


