What the CSS Profile Actually Is and Who Needs It
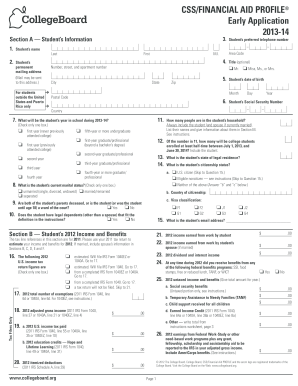
The CSS Profile is an alternative financial aid application that some colleges use instead of, or alongside, the FAFSA. It asks more detailed questions about your family's finances, including home equity, medical expenses, and unusual circumstances. About 250 institutions require it, mostly private universities with their own need-based aid budgets. You create an account at College Board, answer the questions, and pay a fee unless you qualify for a waiver. Most people who file both the FAFSA and CSS Profile find the overlap manageable. The CSS Profile goes deeper into asset information and asks about things the FAFSA ignores, like home equity and the financial situation of a non-custodial parent at certain schools.
How to Fill Out the Css Financial Aid Profile Worksheet Step by Step
First, create your account at studentaid.gov and the CSS Profile site simultaneously since they are separate systems. Have your tax returns, W-2s, and bank statements ready before you start. Going in blind and hunting for documents will add hours to the process. The profile uses your prior-prior year income, so if you are filing for the 2026-27 academic year, you will report 2024 tax information. Start with the student section, then move to parent information. If your parents are divorced or separated, most schools require data from both households. This is one area where students and families consistently get tripped up. The CSS Profile requires the non-custodial parent's information at schools like Harvard, MIT, and Yale, and the custodial parent often has to upload a verification letter explaining why that data cannot be provided. For the asset section, report bank accounts, investments, and business holdings. Do not estimate. If a number feels wrong, look it up. I have seen students round down to the nearest thousand and get flagged for a correction later, which delays everything. Home equity is reported but not counted toward your expected family contribution at most schools, though a handful of institutions do factor it in. Check each school's specific policy on their financial aid page.
Edge Cases and Problems That Come Up in Practice
One issue that comes up regularly involves self-employed parents with irregular income. The Profile asks for business income from Schedule C, but many small business owners have write-offs and depreciation that significantly lower their reported taxable income while their actual cash flow tells a different story. When I worked through this with a family last year, the father's Schedule C showed nearly zero net profit due to equipment depreciation, but he was pulling $6,000 a month in distributions. The workaround was filing a professional statement of circumstances through the CSS Profile's special circumstances section, attaching a year-to-date profit and loss statement and a letter from their CPA confirming the depreciation was non-cash. The financial aid office adjusted the EFC manually based on that documentation. Another frequent problem involves international families who do not have U.S. tax forms. The CSS Profile accepts foreign income documentation, but the conversion and formatting can be tricky. You need to translate documents and provide a currency conversion using the Federal Reserve's annual exchange rate for the applicable year. Some schools accept bank letters or government-issued income certificates in lieu of tax returns. Always check the specific requirements listed under each college's CSS Profile instructions in your account.
Get the Full Details

Common Pitfalls That Can Cost You Money
The biggest mistake families make is treating the CSS Profile like the FAFSA and rushing through it. The questions are more granular. A single unchecked box about whether your family has received unusual medical expenses can prevent the system from accounting for a $40,000 disability-related cost that would otherwise lower your aid eligibility. The special circumstances section is where you explain deviations from normal financial situations, and it is almost always underutilized. Another pitfall involves the non-custodial parent requirement. If you anticipate conflict or cannot obtain the required information, do not just skip it. Submit what you can and upload a statement of circumstances immediately. Some schools will accept a waiver request, but if you do not proactively address the missing data, your financial aid package may be held until the information is provided, which can push you past priority deadlines. The fee structure is another thing people do not plan for. The first school is free. Each additional school costs $16, and there is an annual renewal fee of $16. For a family applying to six colleges, that is $96 upfront. Income-based fee waivers are available, but they require you to meet specific criteria tied to FAFSA eligibility. If you qualify, the waiver is applied automatically when you create your profile, but double-check that it went through before you submit.
When the CSS Profile Is Not the Right Tool
If you are only applying to public universities in your home state, you likely do not need to complete the CSS Profile. Most public institutions rely solely on the FAFSA for need-based aid. Completing it unnecessarily wastes time and money. Verify on each college's financial aid website whether they require the CSS Profile before investing the three to five hours it typically takes to complete. The Profile also has a notable weakness: it does not always adapt well to rapidly changing financial situations. If your family lost a job or faced a major expense after the prior-prior year, the data you enter will reflect the older tax year. The special circumstances section is your outlet for this, but responses are not guaranteed and turnaround times vary widely by institution. Some schools take two weeks to review a circumstances request. Others take longer during peak season. If you are a student with extremely complex finances, such as multi-generational households, trust distributions, or significant international assets, consider working with a financial aid counselor or a college planning professional who understands the CSS Profile's nuances. The cost of that assistance is usually small compared to the difference a properly completed profile can make in your aid award. I have seen gaps of $8,000 to $15,000 per year between a rushed submission and a careful one on the same family's profile.
Practical Timeline and Submission Tips
Open the CSS Profile as soon as it becomes available, which is usually October 1 of the year before you start college. Many schools have priority deadlines between November and February, and completing the Profile early gives you time to resolve issues before those cutoffs. You can submit partial information initially and update it later, but any changes to income or asset figures may trigger a review that delays your aid package. Save your work frequently. The session can time out, and you will lose unsaved progress. Take screenshots of each section before you submit for your own records. Financial aid offices sometimes request clarification months after submission, and having your original answers on hand saves a lot of back-and-forth. After you submit, monitor your email and your CSS Profile account for requests for additional documentation. Some schools send verification letters within days. Others do not communicate anything until spring. If you have not heard back by mid-March, it is reasonable to contact the financial aid office directly and ask about the status of your application.

Alternatives and Complements
If a school requires both the FAFSA and the CSS Profile, treat them as separate but coordinated tasks. Enter the same core financial data into both, but pay attention to where the questions diverge. The FAFSA asks about family size and number in college. The CSS Profile asks about those same items plus additional detail on household composition and dependent care expenses. Inconsistencies between the two forms can raise red flags during verification, so keep your numbers aligned. For families who find the CSS Profile's requirements too burdensome, some states and institutions offer alternative documentation pathways, particularly for students from low-income backgrounds or those with non-traditional financial situations. Check with each school's financial aid office to see what options exist. There is no single universal alternative, but flexibility does exist at many institutions if you know to ask.


