Filing a Connecticut Nonresident Return When You Also Have Pennsylvania Withholding
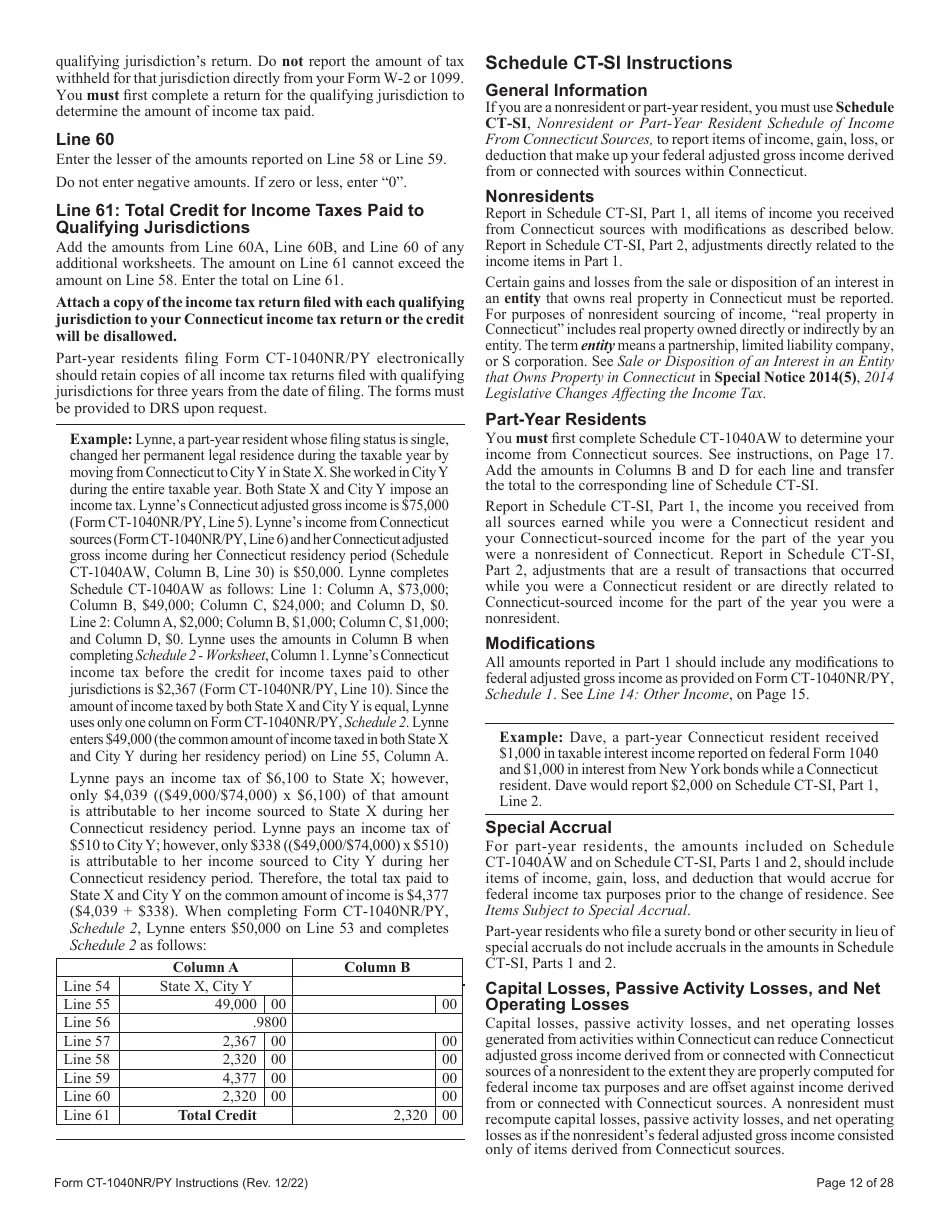
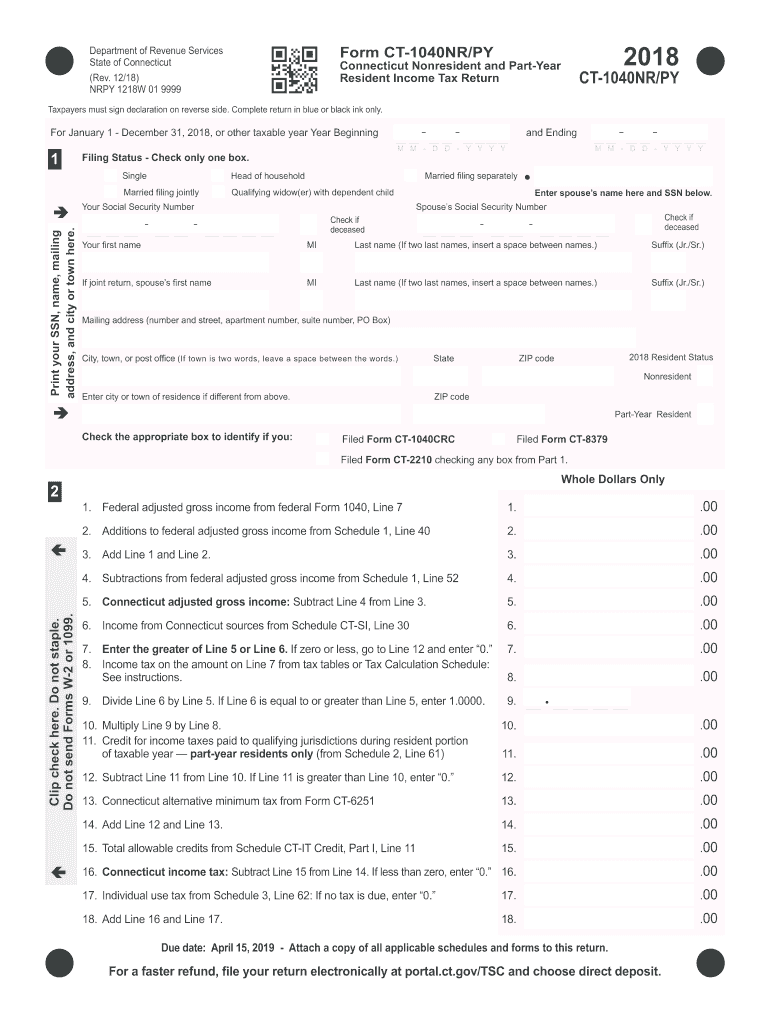
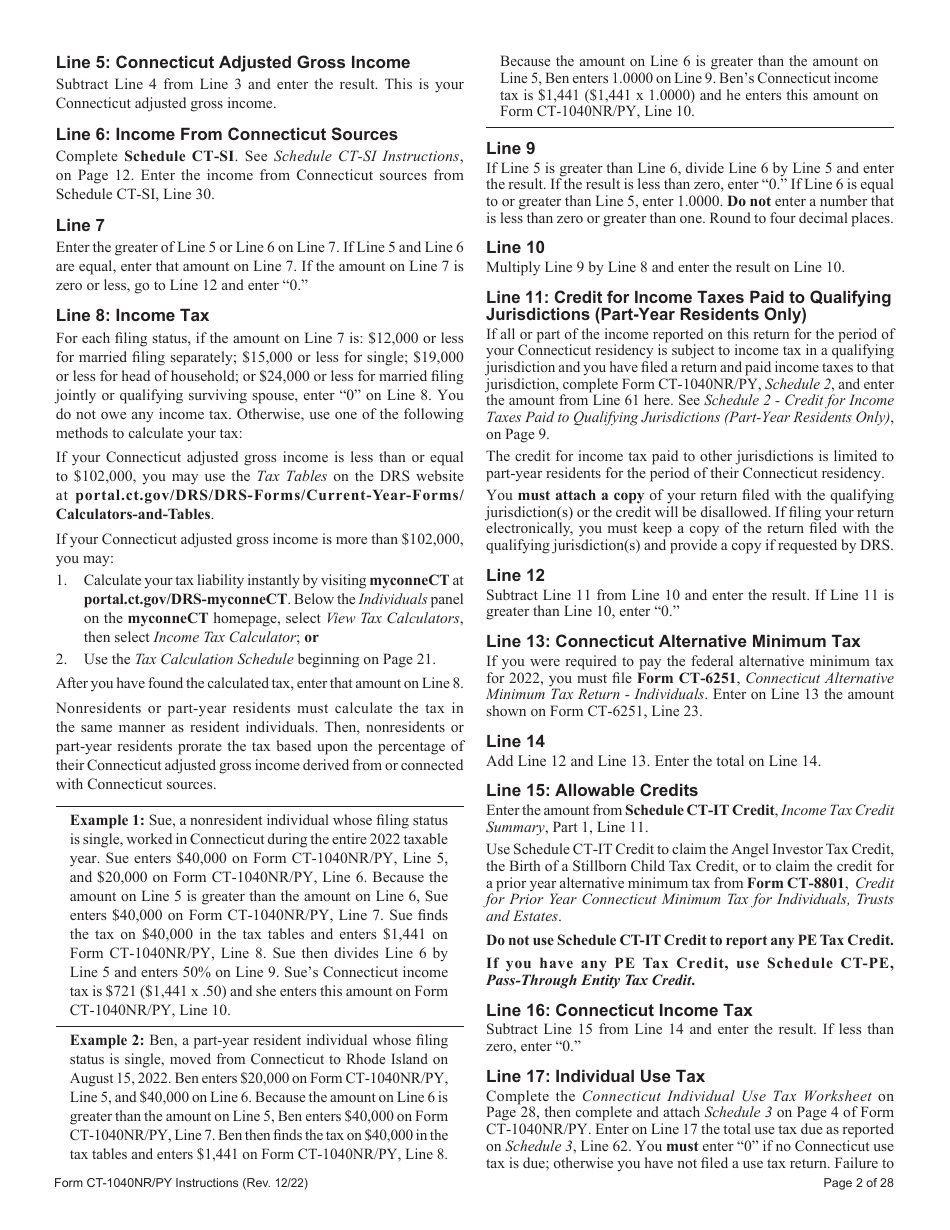
It is not uncommon to find yourself owing Connecticut because you worked there part of the year, only to also discover Pennsylvania took money out of your paycheck while you were living there. The two states handle this differently, and the instructions do not always line up the way you would expect them to. I have been doing this stuff for long enough that I can tell you where the pain points are before you hit them. The Connecticut 1040NR is the nonresident or part-year resident return. "Py" in the title usually shows up in correspondence or software menus referring to Pennsylvania tax credits or Pennsylvania-sourced income allocations. The instructions themselves live on the Connecticut Department of Revenue Services site, and they cover the same basic principle any nonresident form does: you only pay Connecticut tax on income connected to Connecticut, but you may get a credit for taxes paid to other states. Here is the thing most people miss when they first look at the form. The credit for taxes paid to another state is not a straight dollar-for-dollar refund of what Pennsylvania took out. It is limited to the portion of Connecticut taxable income that is also taxed by Pennsylvania. Run the numbers backwards and you will often find that the credit is smaller than the Pennsylvania withholding, which means you still owe something to Connecticut even though Pennsylvania already took money.
I learned this the hard way in 2022. I had split the year between Connecticut and Pennsylvania, with most of my income coming from a consulting contract that I thought was Pennsylvania-sourced because my client was based there. Connecticut disagreed and allocated roughly 60 percent of the income to them under their sourcing rules for services performed partly within the state. The Pennsylvania credit on my Connecticut return was limited by the Connecticut allocation, so I ended up owing about four thousand dollars. The workaround was not dramatic. I simply pulled my W-2s and 1099s, mapped each dollar to the state where the work was physically performed, and used that mapping to support the Connecticut schedule rather than relying on where the payer was located. That corrected allocation brought the Connecticut tax due down to a much more reasonable number.
The mechanics of the Connecticut nonresident credit
Connecticut uses Schedule REC, the Resident Credit form, to calculate the credit for taxes paid to other states. You fill it out after you have determined your Connecticut adjusted gross income and your Connecticut taxable income. The form requires you to enter the amount of income taxed by both states, then the tax paid to the other state, then applies a ratio based on Connecticut taxable income divided by total taxable income. The result caps the credit. Pennsylvania withholding shows up on your W-2 in box 17. Do not just copy that number onto Schedule REC without checking the underlying income allocation first. Withholding is what was taken out, not necessarily what was owed to Pennsylvania. If Pennsylvania itself would not have taxed that income, claiming a credit for it on your Connecticut return is wrong and could trigger a notice later. One detail that trips people up is the timing of the credit. Connecticut allows the credit in the year the tax was paid or accrued to the other state, which usually means the current filing year. If you filed an amended Pennsylvania return in a prior year and got a refund, Connecticut may require you to adjust the credit in the year of the amendment. It is a small compliance detail, but it shows up on audits.
Get the Full Details
Where the instructions fall short
The official instructions are thorough on paper, but they are not written for someone who is juggling two state returns at once. They do not explain how Connecticut views income that is exempt in another state. They do not spell out what happens when your Pennsylvania residency changes mid-year. And they do not warn you about the interaction between Connecticut's pass-through entity tax and the credit calculation, which can matter if you receive K-1 income from a partnership that paid the optional PTE tax. Another limitation worth stating plainly. The credit mechanism only works if the other state actually has a tax on the same income. Pennsylvania does, obviously, but if you are allocating income to a state with no income tax, you get zero credit there and full Connecticut tax on that slice. There is no workaround other than correct sourcing.
Practical steps to get it done right
Start by gathering every W-2, 1099, and K-1. Note the state codes in the withholding sections. Then determine your Connecticut gross income by pulling income sourced to Connecticut under Connecticut's rules, which generally follow the flow of the work, not the flow of the paycheck. Next, compute Pennsylvania taxable income using Pennsylvania's own rules, which may classify the same income differently, especially for remote work and sourcing of service income. Fill out the Connecticut 1040NR main form first. Then go to Schedule REC. Enter the Pennsylvania tax liability, not just the withholding, because the two can differ. If you itemized on your Pennsylvania return and claimed deductions that Connecticut does not allow, you may need to adjust the Pennsylvania tax figure accordingly. Keep a worksheet. Not because the process is complicated in theory, but because you will want documentation if either state asks why the credit is what it is. A simple spreadsheet showing income by state, the Connecticut allocation, the Pennsylvania allocation, the tax paid to each, and the resulting credit calculation is enough to satisfy a reviewer without turning into a novel.
Once you have that worksheet, compare the Connecticut tax liability after the credit to what you expect. If the number looks off, recheck the allocation before you file. It is easier to catch a sourcing error on your own time than to explain it to a revenue department months later.