Getting Started With Cta Commodity Trading Advisor
I have been running commodity trading systems since the early 2000s, back when most people still managed strategies by hand. The idea of a Cta Commodity Trading Advisor is simpler than most folks assume, but the practical execution trips people up constantly. This guide walks through what it actually is, how to get one operational, and where the real headaches show up once you are live. A Cta Commodity Trading Advisor is essentially an automated system designed to manage futures and options positions across commodity markets. The "CTA" part refers to Commodity Trading Advisor, which is a regulated designation in the United States. Before you can legally offer this service to clients, you need to register with the CFTC and become a member of the NFA. That is the compliance layer, separate from the actual trading logic. The software side handles signal generation, risk management, order routing, and position monitoring. Most modern platforms build these using Python or C++. The core logic typically involves trend following, mean reversion, or breakout strategies applied to markets like crude oil, natural gas, corn, wheat, copper, and gold.
Here is something most beginner guides skip: the difference between a backtested strategy and a live Cta Commodity Trading Advisor is rarely about the alpha. It is about slippage, latency, partial fills, and the psychological friction of watching a strategy draw down while it should be working fine. I learned this the hard way in 2014 when my first live system under natural gas futures kept getting stopped out on what looked like normal volatility. The issue was not the signal logic. It was the order book depth. The strategy assumed continuous fills at the quoted price, but during the European session overnight, the bid-ask spread on NG contracts widened to over thirty cents. My stop losses were triggering at worse prices than expected, eroding returns by roughly eight percent annually. The fix was implementing a dynamic spread filter that suspended trading when the spread exceeded twenty-five cents, combined with tiered order placement instead of market orders. This cut the problem to near zero without materially reducing opportunity.
Registration and Compliance Setup
If you want to run this professionally, start with the paperwork. Registering as a CTA requires filing Form CTA with the NFA, paying the applicable fees, and meeting ongoing reporting obligations. The cost runs several thousand dollars upfront and several hundred monthly for compliance filings. Most people start as a registered trader managing their own capital and only pursue formal registration once they have verifiable performance records and sufficient AUM to justify it. Key requirements include:
Get the Full Details
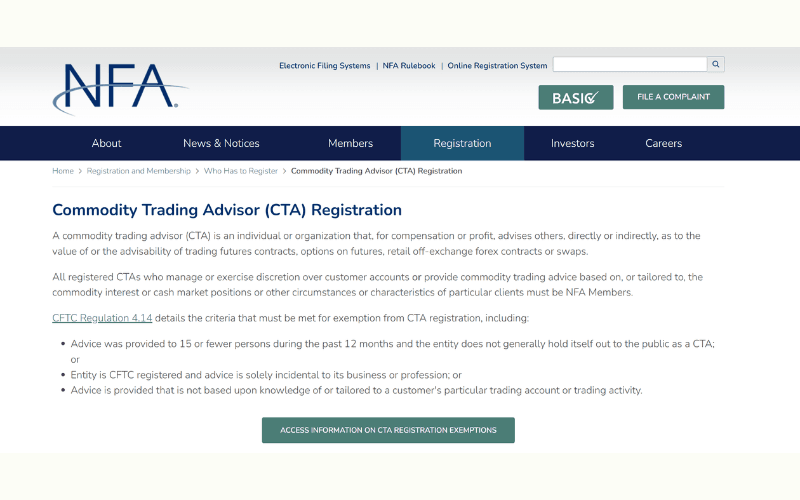
- NFA membership as a CTA
- CFTC registration
- Fingerprinted background check
- Fiduciary disclosure documents for clients
- Monthly NFA reporting (BR-AD, etc.)
A counter-intuitive point about compliance: most people think the hard part is the registration itself. It is not. The hard part is maintaining proper records. Every trade, every modification, every risk calculation needs to be logged in a way that survives an NFA audit. I have seen well-run strategies lose credibility because the operator could not produce clean trade logs from six months ago. Use an automated trade journaling system from day one. Something like a PostgreSQL database with every order event, execution result, and portfolio snapshot timestamped and immutable. A production Cta Commodity Trading Advisor needs several components working together reliably. Signal generation sits on top of market data feeds, which come from vendors like IQFeed, DTN, or Interactive Brokers. The engine processes these signals, runs risk checks, and sends orders to the broker API. The execution layer handles order lifecycle management: submission, acknowledgment, partial fills, cancellations, and replacements. For data storage, I recommend a time-series database like InfluxDB or QuestDB alongside a relational database for trade records. The time-series side handles OHLCV data for backtesting and monitoring. The relational side handles order status and position accounting.
Risk management deserves its own paragraph because this is where most systems fail in production. You need hard position limits, daily loss limits, and correlation checks across your commodity exposures. A Cta Commodity Trading Advisor that trades both crude and natural gas without recognizing their correlation will blow up faster than one that ignores it entirely. These two instruments move together with a correlation coefficient often above 0.7 during supply disruptions, and most retail operators do not account for this when sizing individual positions.
Building and Testing the System
Start with a clean Python environment. I use a virtualenv with pandas, numpy, and zipline or backtrader for backtesting, then move to a lighter execution framework for live trading. The backtesting phase should cover at least five years of data across multiple market regimes. A strategy that looks good only in a low-volatility period is not a strategy. It is a coincidence. Key testing steps: First, verify your backtest engine against known benchmark results. If your backtest shows a Sharpe ratio of 2.0 on a trend-following commodity strategy, something is wrong. Realistic Sharpe ratios for well-run CTA strategies fall between 0.8 and 1.4 after costs.
Second, run Monte Carlo simulations on your equity curve. Shuffle your trade sequence one thousand times. If fifty percent of the shuffled sequences blow up, your strategy has hidden fragility that peak performance metrics will hide from you. Third, test with realistic slippage and commission assumptions. Use half the spread as slippage for market orders and a quarter for limit orders. For commodity futures, factor in exchange fees and clearing costs. On the CME, this is usually around 0.25 to 0.50 per contract round turn depending on the product. Fourth, run a paper trading period of at least thirty days before going live. This exposes infrastructure issues that no backtest will show. I caught a recurring bug this way where my order cancellation logic created orphaned orders during network timeouts. The system thought orders were filled. They were not. The positions inflated silently for three days before I noticed the P&L mismatch.
Live Deployment Checklist
Before flipping the switch, confirm these items are in place: Connectivity redundancy. Run your system on a VPN with a backup internet connection, or host on a cloud instance with automatic failover. A five-minute network outage during a volatile session can cost you more than a full trading day of missed signals. Mutual fund or brokerage account with API access. Interactive Brokers, Trado, or Rithmic are common choices for commodity futures. Rithmic is the standard for professional proprietary trading firms because of its low-latency execution and advanced order types.
Failsafe circuit breakers. Set a hard daily loss limit, typically two to three percent of account value. When triggered, the system flat exits all positions and stops accepting new signals until the next session. I once watched a friend's Cta Commodity Trading Advisor run a full losing day because he forgot to set this. He lost fourteen percent in a single session on a gold strategy that had worked flawlessly for two years. Monitoring dashboard. A simple web interface showing current positions, open orders, daily P&L, and system health. If you cannot see what the system is doing in thirty seconds, you are flying blind.
Common Pitfalls to Avoid
Overfitting to historical data is the most destructive mistake. A Cta Commodity Trading Advisor tuned to fit the last three years of commodity price action will almost certainly underperform going forward. Markets adapt. What worked during the 2020 pandemic crash does not apply to the 2022 inflation surge. Keep your models simple. Three to five parameters is plenty. More parameters than that is usually curve-fitting in disguise. Ignoring regime changes is closely related. Commodity markets shift between trending, range-bound, and volatile regimes. A pure trend-following system will bleed money in ranging markets for months before the trend returns. Include a regime detection component, or accept that your strategy will have extended drawdown periods and manage your capital accordingly. Data quality issues surface constantly. Missing ticks, adjusted future contracts rolling at wrong times, and corporate action adjustments can silently corrupt your backtests. Always verify your data against a second source. I cross-check all commodity futures data against the CME group website for contract specifications and roll dates. This catches about three percent of data errors that would otherwise go unnoticed.
Position sizing errors are another common failure mode. Using fixed dollar amounts per trade ignores volatility differences between markets. Trading copper and trading coffee with the same dollar risk per position means you are effectively taking a much larger position in coffee relative to its average true range. Use volatility-adjusted position sizing based on the instrument's ATR or standard deviation of returns.
Operational Maintenance
A running Cta Commodity Trading Advisor requires weekly attention. Check your trade logs for execution anomalies. Review position limits versus actual exposure. Update any market data subscriptions that have expired. Run a quick regression test on your strategy logic to catch any bugs introduced by environment changes. Monthly tasks include formal performance review, recalibration of risk parameters if market conditions have shifted significantly, and compliance record review if you are a registered CTA. For registered advisors, the monthly NFA report FOCUS Part II must be filed accurately and on time. Late filings carry penalties that scale with the severity and duration of the delay. Quarterly, perform a deeper strategy review. Compare current performance against your backtested expectations. Analyze any drift in signal effectiveness. Decide whether to modify parameters or let the strategy continue as-is. Most strategies show gradual performance decay over twelve to eighteen months. This is normal. The question is whether the decay is within your tolerance band.
When a Cta Commodity Trading Advisor Is Not the Right Move
Automation makes sense when you have a strategy with clear, repeatable rules and sufficient capital to absorb the infrastructure costs. For a single trader with under fifty thousand dollars and a simple strategy, the engineering overhead of building and maintaining a Cta Commodity Trading Advisor may outweigh the benefits. In that case, using an existing retail platform like TradeStation, NinjaTrader, or Sierra Chart with their built-in scripting capabilities gets you most of the way there with far less setup work. For institutional-scale operations managing multiple strategies across dozens of commodity markets, the custom approach pays for itself quickly through better execution control, tighter risk management, and the ability to implement strategies that off-the-shelf platforms cannot support. The space sits somewhere between those extremes for most operators. A moderately sized fund or serious individual trader with fifteen to one hundred million in capital typically finds the custom Cta Commodity Trading Advisor path worthwhile, provided they treat it as an engineering discipline rather than a once-and-done project. The systems that last are the ones that get maintained, monitored, and honestly evaluated on their ongoing merits rather than their backtested promises.