Setting Up Finance Journal Spreads That Actually Work
I spent three years managing personal finance spreadsheets before I figured out what I was doing wrong. Most people start with something overengineered and abandon it within a month. The issue isn't the tool, it's the friction between how you want to track money and how much work the system actually requires from you daily. Cute Finance Journal Spreads refers to a category of personal finance tracking layouts that prioritize visual appeal alongside functionality. These are typically spreadsheet-based or digital journal templates where the aesthetic matters as much as the data. I use them because if the system looks pleasant, I'm more likely to actually maintain it. That sounds trivial until you realize most people give up on finance tracking within six weeks because it feels like a chore.
Cute Finance Journal Spreads
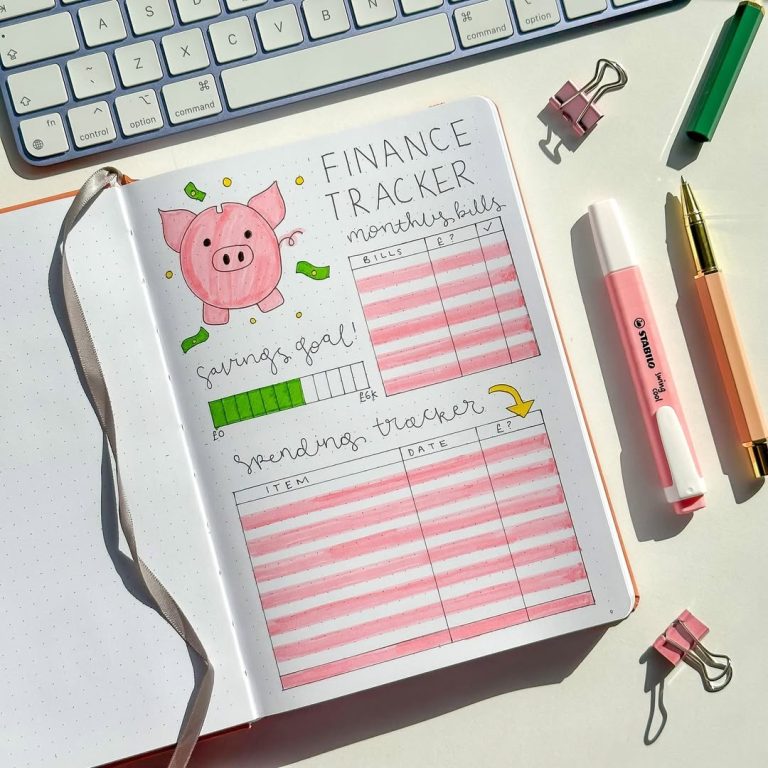
Here's the practical breakdown of how to set one up properly. You need three sheets minimum. One for transaction logging, one for monthly summaries, and one for annual review. The cute stuff—color coding, icons, themed headers—goes in the transaction log. That's the sheet you'll interact with daily, so make it look nice. The other two sheets can be as ugly as you want because you only open them occasionally. Start with your transaction sheet. Columns I recommend: date, description, category, amount, payment method, and a notes field. That's it. Don't add seventeen more columns "for later." You won't use them. The notes field handles the exceptions.
For the monthly summary sheet, use a pivot table or SUMIF formulas pulling from your transaction log. This is where most people overcomplicate things. You don't need complex financial modeling. You need to know how much you spent per category each month. A simple pivot table refresh takes eight seconds. The annual review sheet is basically a summary dashboard. Total income, total expenses, net savings by month. You can use a simple INDEX-MATCH formula or just copy-paste monthly totals. I went with copy-paste initially because it was faster to set up and harder to break when I changed the transaction sheet structure. Now, the aesthetic layer. This is where the "cute" part comes in. Use data validation dropdowns for categories so you're not typing them repeatedly. Create a color-coding system where each category has a consistent color across all sheets. I use a soft palette—muted pastels, nothing neon. It reduces eye strain during daily entry. Add icons using Wingdings or standard emoji characters if you're working in Google Sheets. Things like dollar signs, calendar icons, or arrows next to section headers. Small touches that make the sheet feel less sterile.
Get the Full Details
I had a specific problem with recurring transactions that threw off my monthly totals. Subscriptions and automatic payments would sometimes register on different days depending on the bank, which made month-over-month comparisons unreliable. My workaround was adding a "normalized date" column that always logged recurring transactions on the first of the month regardless of when they actually posted. This let my summary sheets show consistent monthly comparisons without constant manual adjustment. Here's something counter-intuitive that took me a while to learn: fewer categories beats more categories every time. I started with forty-seven spending categories. I was entering data for twenty minutes a day and still wasn't consistent. I consolidated down to twelve broad categories and my daily entry time dropped to under two minutes. Consistency matters more than granularity when you're trying to build a habit. Another thing beginners miss: conditional formatting should serve a purpose, not just decorate. I used to go overboard with rainbow-colored cells and gradient fills. It looked great but created visual noise that made scanning for errors harder. Now I use conditional formatting strictly for alerts—red highlights for transactions over a certain threshold, orange for categories exceeding monthly budgets, green for months meeting savings goals. Everything else stays neutral. This actually helps you spot problems faster instead of drowning in colors.
The honest downsides: these spreadsheets require daily maintenance. If you skip two days, you'll spend an hour catching up and the whole system loses value. They also don't integrate with your bank automatically unless you set up a complicated connection or pay for a third-party service. The cute aspect can become a distraction if you spend more time customizing colors than actually tracking your money. I've seen people redesign their spreadsheets weekly for months without ever reviewing their actual spending patterns. If you have irregular income, variable expenses, or multiple accounts to reconcile, a traditional finance journal spreadsheet might not be the right tool. You'd be better served by a simple ledger or an app with automated bank feeds. The friction of manual entry becomes unbearable at that scale. For the template itself, I typically build mine in Google Sheets because of the collaboration and backup features. I start with a blank sheet, set up the three-tab structure, then apply a clean grid layout with generous row heights for easy reading. The conditional formatting rules go in last because they depend on your data structure being locked in. Color palette comes from a simple swatch I save somewhere—I use hex codes like #E8DCC4 for backgrounds, #7C9099 for headers, and #A8C5B8 for alternating rows. Those exact colors don't matter. Pick something that doesn't hurt your eyes and stick with it.
Export your final version as a template so you can duplicate it for new months without recreating formulas. Name it something identifiable. Keep an archive of previous months in a separate folder. I learned that one the hard way after accidentally deleting a cell reference and losing three months of historical data. The system works if you use it. The cuteness factor is genuinely useful for adoption because it removes the clinical dread most people feel about looking at their finances. But if you find yourself spending more time designing than tracking, you've crossed into hobby territory and the tool is no longer serving you.