What a Cycle Loan Calculator Actually Does for You
A cycle loan is a revolving credit facility where you can draw, repay, and redraw funds up to a set limit. It is not a standard installment loan. The payment structure changes depending on how much you have drawn and for how long. A Cycle Loan Calculator helps you model those shifting numbers without manually crunching Excel every time you adjust your assumptions. I spent years working with small business lenders who kept mixing up how to present cycle loan costs. The standard amortization table does not apply here. Interest compounds on your drawn balance, not the total facility limit. Repayments are often interest-only during the draw period, then shift to principal and interest during the amortization phase. A basic loan calculator will give you wrong numbers if it assumes fixed monthly payments from day one.
How to Use a Cycle Loan Calculator
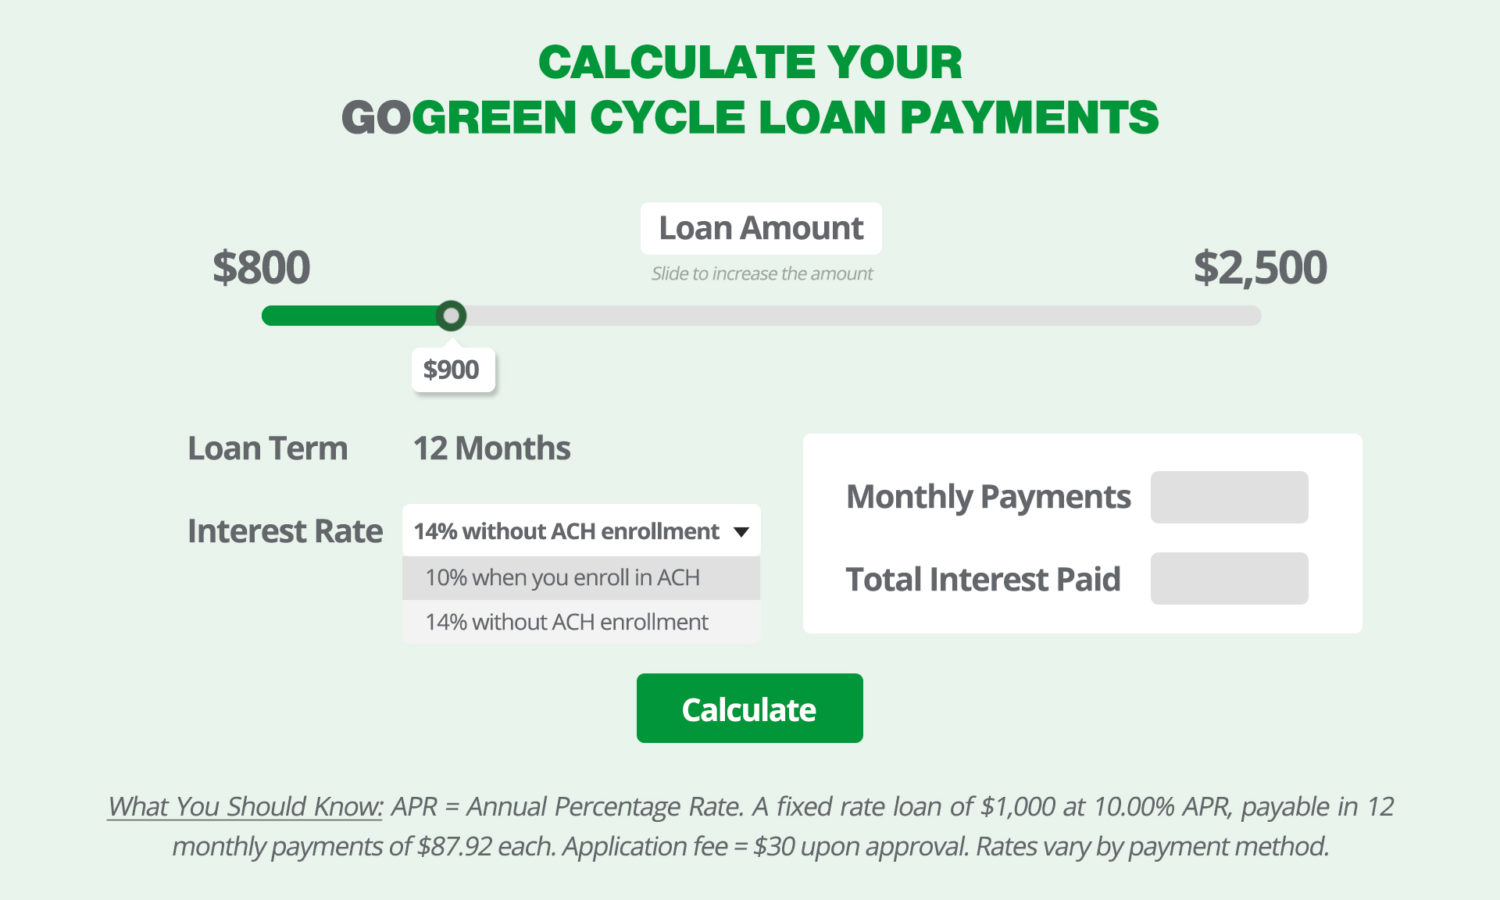
Most cycle loan calculators require you to input the credit facility limit, the annual interest rate, the draw period length, and the repayment period length. Some also let you specify how much you plan to draw upfront and whether draws happen all at once or in tranches over time. Here is the practical workflow I use: Enter the facility amount, say $500,000. Set the interest rate at the current prime plus spread. A typical commercial cycle loan runs prime plus 1 to 3 percent. If prime is 6 percent, your rate is around 7 to 9 percent. Enter the draw period, usually 1 to 3 years. Enter the amortization or repayment period, often 5 to 10 years. Then enter your expected draw amount. This last step is where most people get tripped up because they leave it blank and the calculator assumes full draw from day one, which is rarely accurate.
Run the calculation. The output should show you the interest-only payments during the draw period, the balloon or transition payment when the draw period ends, and the fully amortized payment schedule after that. I had a client once who was modeling a $200,000 cycle loan for seasonal inventory financing. They entered the full $200,000 as the expected draw, but in reality they only needed about $80,000 drawn at peak season. The calculator spit out interest payments based on $200,000, making the loan look far more expensive than it actually was. I adjusted the expected draw field to reflect the realistic utilization rate and recalculated. The true monthly interest cost dropped by nearly 60 percent. That gap between facility limit and actual draw amount is something nobody warns you about until you see it in the numbers.
Get the Full Details
What the Numbers Tell You
During the draw period, your payments are typically just interest on the outstanding balance. That means a $100,000 draw at 8 percent annual interest costs you roughly $667 per month in interest alone. Your principal stays untouched. This keeps cash flow flexible during periods of high utilization. When the draw period closes, the loan usually converts to a standard amortizing structure. The remaining balance gets paid down over the agreed term. The calculator will show you the new payment amount, which jumps significantly because you are now paying both principal and interest on the full outstanding balance. One detail that trips people up: some cycle loans include a commitment fee on the undrawn portion of the facility. This is a small percentage charged on the unused credit line, typically 0.25 to 0.50 percent annually. A good Cycle Loan Calculator will account for this, but not all do. Check the output carefully. If the fee is not included, you are looking at a hidden cost that can add up fast on a large undrawn facility.
When a Cycle Loan Calculator Falls Short
These tools work well for straightforward scenarios. They break down when your loan has variable draw dates, partial repayments mid-cycle, or tiered interest rates based on utilization. I encountered a case where a business drew down 30 percent of their facility in month one, then another 25 percent in month four, then repaid 15 percent in month seven before drawing again. Standard calculators assume a flat draw amount. They cannot handle lumpy, unpredictable cash flows the way a real cycle loan operates. In that situation, I built a custom spreadsheet with month-by-month tracking of draws, repayments, and interest accrual. It took about two hours to set up but saved the client from mispricing a $1.2 million facility by thousands of dollars over the life of the loan. If your borrowing pattern is irregular, a generic calculator will mislead you. You need a tool that tracks the running balance month by month rather than assuming a static draw amount. Another limitation: most online calculators do not factor in the administrative costs that come with commercial cycle loans. Document fees, annual review fees, and legal costs are rarely included in the output. Budget an additional 0.5 to 1.5 percent of the facility amount in upfront costs. On a $500,000 line, that is $2,500 to $7,500 you need to account for separately.
Realistic Expectations
A cycle loan calculator gives you a framework, not a final answer. The numbers it produces are based on assumptions you enter. Garbage in, garbage out. Be honest about your draw patterns, your repayment timeline, and your fee structure. If you can, run two or three scenarios: conservative, moderate, and aggressive draw assumptions. The range between them tells you how sensitive your payments are to utilization changes. Commercial lenders also vary in how they calculate interest. Some use a 360-day year, others a 365-day year. The difference is small but measurable. A $100,000 balance at 8 percent over a 30-day billing cycle comes to $666.67 with a 360-day basis versus $657.53 with a 365-day basis. Over a year, that is about $35 in extra interest. Not dramatic, but worth knowing when you are comparing offers from multiple lenders. There is no single downloadable tool I can point you to that handles every edge case. Most free online calculators are too simplistic for commercial cycle loans. The ones built by banks and credit unions tend to be more accurate because they reflect actual product structures. If you are evaluating a specific facility, ask the lender for their payment projection. It will match their exact terms, including any fees and day-count conventions you might otherwise miss.