What Actually Happens When You Do Daily Accounting
Most people treat daily accounting like a checklist you tick off so you don't get penalized later. That's why it feels like busywork. It's not. The real purpose is catching mistakes while they're still cheap to fix. A rounding discrepancy from last Tuesday costs you about twelve minutes to track down today. Next month when the books close, that same discrepancy could eat an entire afternoon and still leave you unsure which column was wrong. Start with the reconciliation step, not the entry step. I used to record first and reconcile second. Wasted about three weeks before I realized I was spending more time hunting for matched entries than I ever would have spent matching them upfront. The shift was small but it cut my evening routine from roughly forty-five minutes down to maybe twenty, sometimes less depending on how many transactions came through the payment processor that day. Here's the part nobody tells you: daily accounting only works if your chart of accounts doesn't change mid-month. I learned this the hard way when a client added a new expense category halfway through October. By November 1st, the prior month was already closed and I had to go back and reclassify fourteen transactions manually. Never add accounts between the 25th and the end of the month unless you want to live with the consequences.
Reconcile against the bank feed before you worry about anything else. Your bank balance is the ground truth. If that doesn't match, nothing downstream matters. I once spent two hours investigating a missing expense before realizing the bank feed itself was lagging by one business day because of a weekend deposit. Refreshed it and everything fell into place in about three clicks. Check your feed freshness first. Always. The trick most beginners miss is that you don't need to reconcile every single account every day. Focus on checking accounts and credit cards. Savings accounts, fixed assets, and balance sheet items can wait until the weekly batch. This alone removes about half the work without leaving anything exposed.
Where the Process Breaks Down
Daily accounting fails fast when your receipt capture is loose. I handled a situation last spring where someone had photos of paper receipts scattered across four different cloud drives and another dozen in their email attachments. Trying to tie those to daily entries took me about an hour per transaction. The fix was brutal but simple: a single shared folder with a naming convention. Photo name followed by date and vendor. That alone reduced receipt matching from an hour to roughly four minutes per item. Another breakdown point is multi-currency transactions. If your business operates in more than one currency and you're doing daily entries, the exchange rate issue will find you. I once booked a €3,200 invoice at 1.0842 when the actual rate on the statement was 1.0917. The variance looked tiny in dollars, maybe forty, but it cascaded through three other reconciliations and I spent an entire Friday morning untangling it. Use your software's automated rate lookup or set a daily rate check before you touch anything. There's also a ceiling on how much this approach helps. If you're processing more than roughly two hundred transactions per day, daily accounting becomes more burden than benefit. The time cost outweighs the error detection advantage at that volume. At that point you're better off switching to a weekly deep-dive with daily exception reporting instead. Catch the outliers in real time and do the full reconciliation once a week.
Get the Full Details
The Actual Workflow
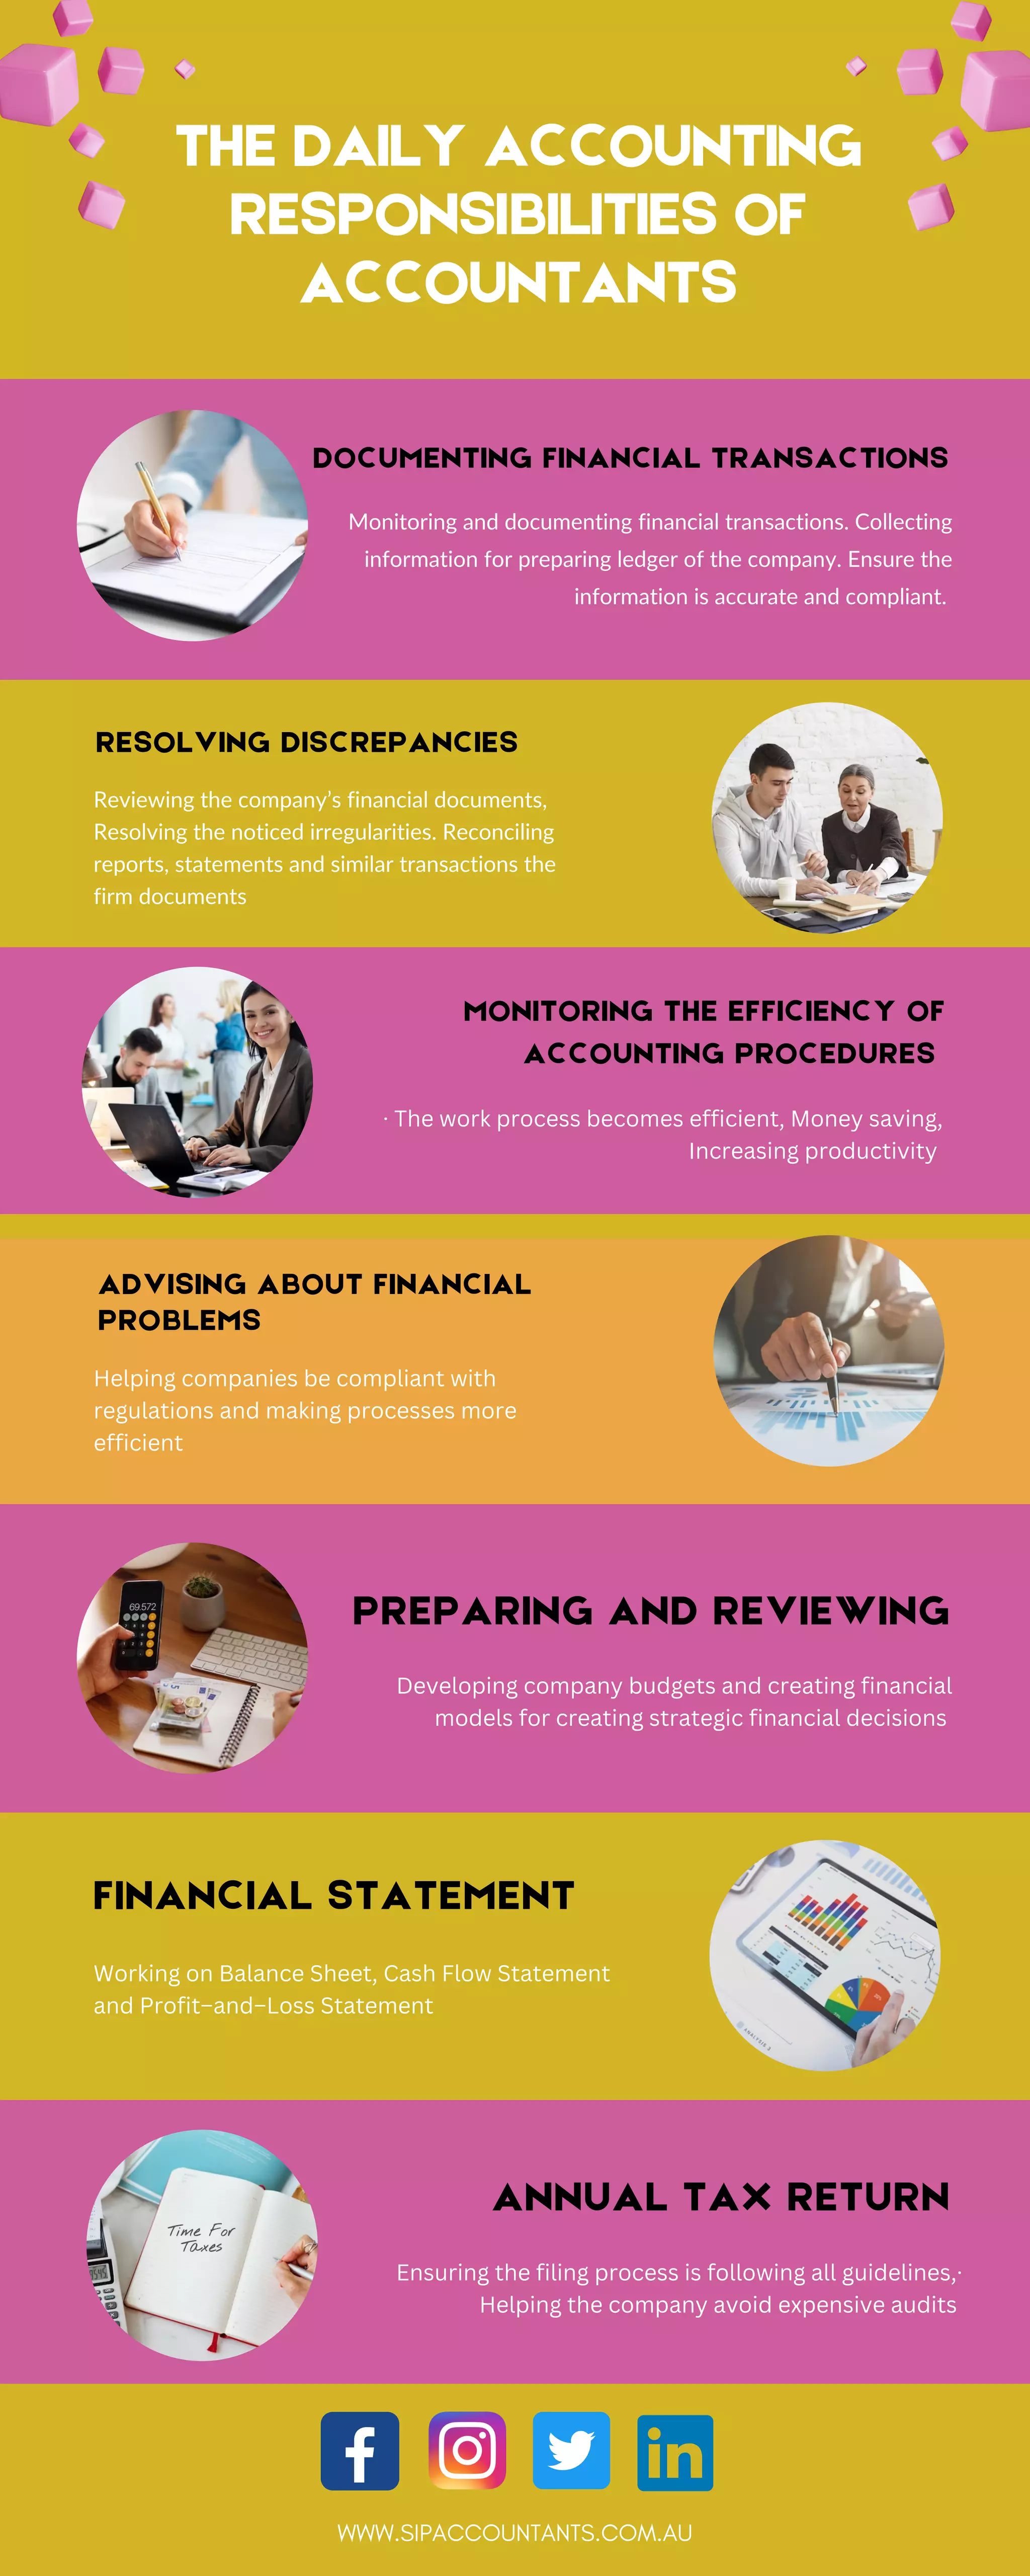
Log in to your accounting platform. Pull the bank and credit card feeds. Match transactions. Flag anything that doesn't auto-clear. Review the profit and loss for the day and compare it to the previous working day. If the variance is more than five percent, dig into it right then. Don't bookmark it. Don't say you'll look at it tomorrow. Tomorrow you won't remember what was normal. Enter any unrecorded transactions. Receipts, manual adjustments, payroll splits. Keep it flat. Don't create complex journals at end of day. That's a closing exercise, not a daily one. Cross-check your accounts payable. Open invoices past due, upcoming payments due within the next forty-eight hours, anything sitting in the draft queue. Missed a vendor deadline because it was sitting in drafts once. Cost us a two percent early payment discount we'd been claiming for three years straight. Never happened again.
Export a quick trial balance. Not for analysis. Just to verify debits equal credits and the numbers haven't drifted. If they have, you've just saved yourself a close-of-month crisis. This routine, done consistently, keeps your books within about a two-day lag from reality. That lag is enough buffer to catch almost everything that matters without turning bookkeeping into a full-time job. Beyond that, you're either over-processing or your transaction volume has outgrown the daily model.