Getting Your Daily Accounting Right Without Losing Your Mind
The first thing people get wrong about daily accounting is they treat it like an end state. It's not. It's a capture mechanism. You're recording transactions close to the moment they happen so that when month-end arrives, you aren't starting from zero every time. A daily approach where you actually close the books at 5 PM each evening is fundamentally different from one where you "try to catch up on transactions." The difference shows up in reconciliation effort. Daily accounting tutorial content online usually covers the workflow in a vacuum. It talks about entering invoices, recording payments, and reconciling bank feeds. That's accurate. It's also incomplete because nobody mentions the part that makes or breaks the system: timing discipline. Here's how the actual process works. Start each morning by pulling yesterday's bank and credit card feeds into your system. Match anything that posted overnight. Process any expense receipts that came in through email or a scanning app. Record invoices you sent the day before if you haven't already. Do this before you open anything else. You do not open your inbox until the daily books are closed. This one habit alone prevents the cascade of forgotten entries that makes monthly closes painful.
I learned this the hard way in 2019. My firm was using QuickBooks Online for about forty small business clients. One client, a landscaping company, had every invoice sent through an SMS platform and payments collected on job completion via check. Their field guys never brought receipts back the same day. We'd get a pile of thirty to fifty paper receipts every Friday, and I'd spend my entire weekend trying to sort through mud-stained job tickets with names written in pencil. The workaround was simple but required changing their behavior, not just their software. We set up a free Dropbox account they called "Receipts," and I made it a condition of our engagement that someone in the office had to snap a photo of every receipt before the truck left the yard. I started a weekly Friday call at 3 PM to walk through the week's entries. That cut our month-end reconciliation from three days down to about four hours. The system didn't change. Their discipline did.
The Mechanics of Daily Entry
Most modern platforms handle the heavy lifting through bank feeds. Transactions auto-import as they post. Your job is matching, not re-entering data. When you see a $847.32 withdrawal from "USPS" and you have a pending shipping expense for $847.32, you match them. When the amount doesn't line up, you investigate. That investigation is where people waste time. A common mistake is creating new transactions instead of editing existing ones. If your chart of accounts has a generic "Office Supplies" line and you receive a $200 delivery from Staples, don't just match it blindly. Click through to verify it belongs there. I once spent two hours reconciling a client's credit card only to discover a $4,200 purchase classified as office supplies that was actually a piece of equipment purchase requiring depreciation. The match looked clean. The classification was wrong. Bank feed matching is not a substitute for review. It's a filter. For businesses using cash basis accounting, daily entry is simpler but requires more vigilance on receivables. Revenue recognition matters even if you aren't accrual. Recording an invoice the same day you send it means you actually track who owes you money instead of discovering gap months later when you need cash flow information. This is the practical reason daily entry exists beyond compliance.
Get the Full Details

Software Choices and Their Friction Points
The big three in North America are QuickBooks Online, Xero, and FreshBooks. QuickBooks dominates market share but its interface has gotten more cluttered with each update. Xero handles bank reconciliation slightly better for multi-account setups. FreshBooks is oriented toward service businesses and invoice-first workflows. None of them are bad. They all have different blind spots. QuickBooks Online has a specific issue with inventory items that nobody warns you about. If you add an inventory item and then switch its value affecting setting after you've already recorded sales, the system does not retroactively adjust cost of goods sold. You end up with revenue that doesn't match your actual COGS and a reconciliation that refuses to balance. I spent an entire afternoon fixing this on a client's books and had to reverse six months of sales entries to reset the inventory valuation. The workaround was to set up inventory items correctly from the start and never modify their settings after transactions exist. Xero's reconciliation interface is cleaner but its reporting leaves something to be desired. The profit and loss report defaults to cash basis for new setups even if you selected accrual during configuration. You have to manually switch each report type. This costs about twenty minutes on setup but it matters if you're preparing financials for a lender who expects accrual statements. One missed setting change means you're presenting incorrect financial data.
Reconciliation as a Daily Habit
Monthly reconciliation is the traditional model. Daily reconciliation is the better one. When you reconcile every day, discrepancies are small, fresh, and contained. A $12.50 mismatch between your records and a credit card feed is easy to track down on a Tuesday when you remember what that purchase was for. Finding that same $12.50 error three weeks later during a month-end close requires digging through memory, email threads, and possibly calling vendors. The actual process takes most businesses between fifteen and forty-five minutes per day depending on transaction volume. A restaurant with hundreds of daily card transactions will take longer than a consulting firm sending five invoices a week. Set a timer. Work within it. If you can't reconcile in your time budget, you have a data entry problem, not a reconciliation problem. The fix is upstream. I should mention that daily reconciliation doesn't solve everything. There are scenarios where it simply cannot work. A business processing over five hundred transactions per day will find daily reconciliation impractical. The time investment exceeds the benefit. In those cases, weekly reconciliation with a strict cutoff policy is the reasonable alternative. You batch your entries, reconcile every Friday, and maintain a running suspense account that gets cleared before the weekly close. This is not ideal but it is realistic for high-volume operations.
Another limitation nobody talks about is the human factor. Daily accounting requires a consistent person or team. If three different employees handle entries on different days with different standards, reconciliation becomes a puzzle where the pieces don't fit. Document your entry standards. Write them down. A three-paragraph document titled "How We Record Things" posted in your shared drive is worth more than any software feature.
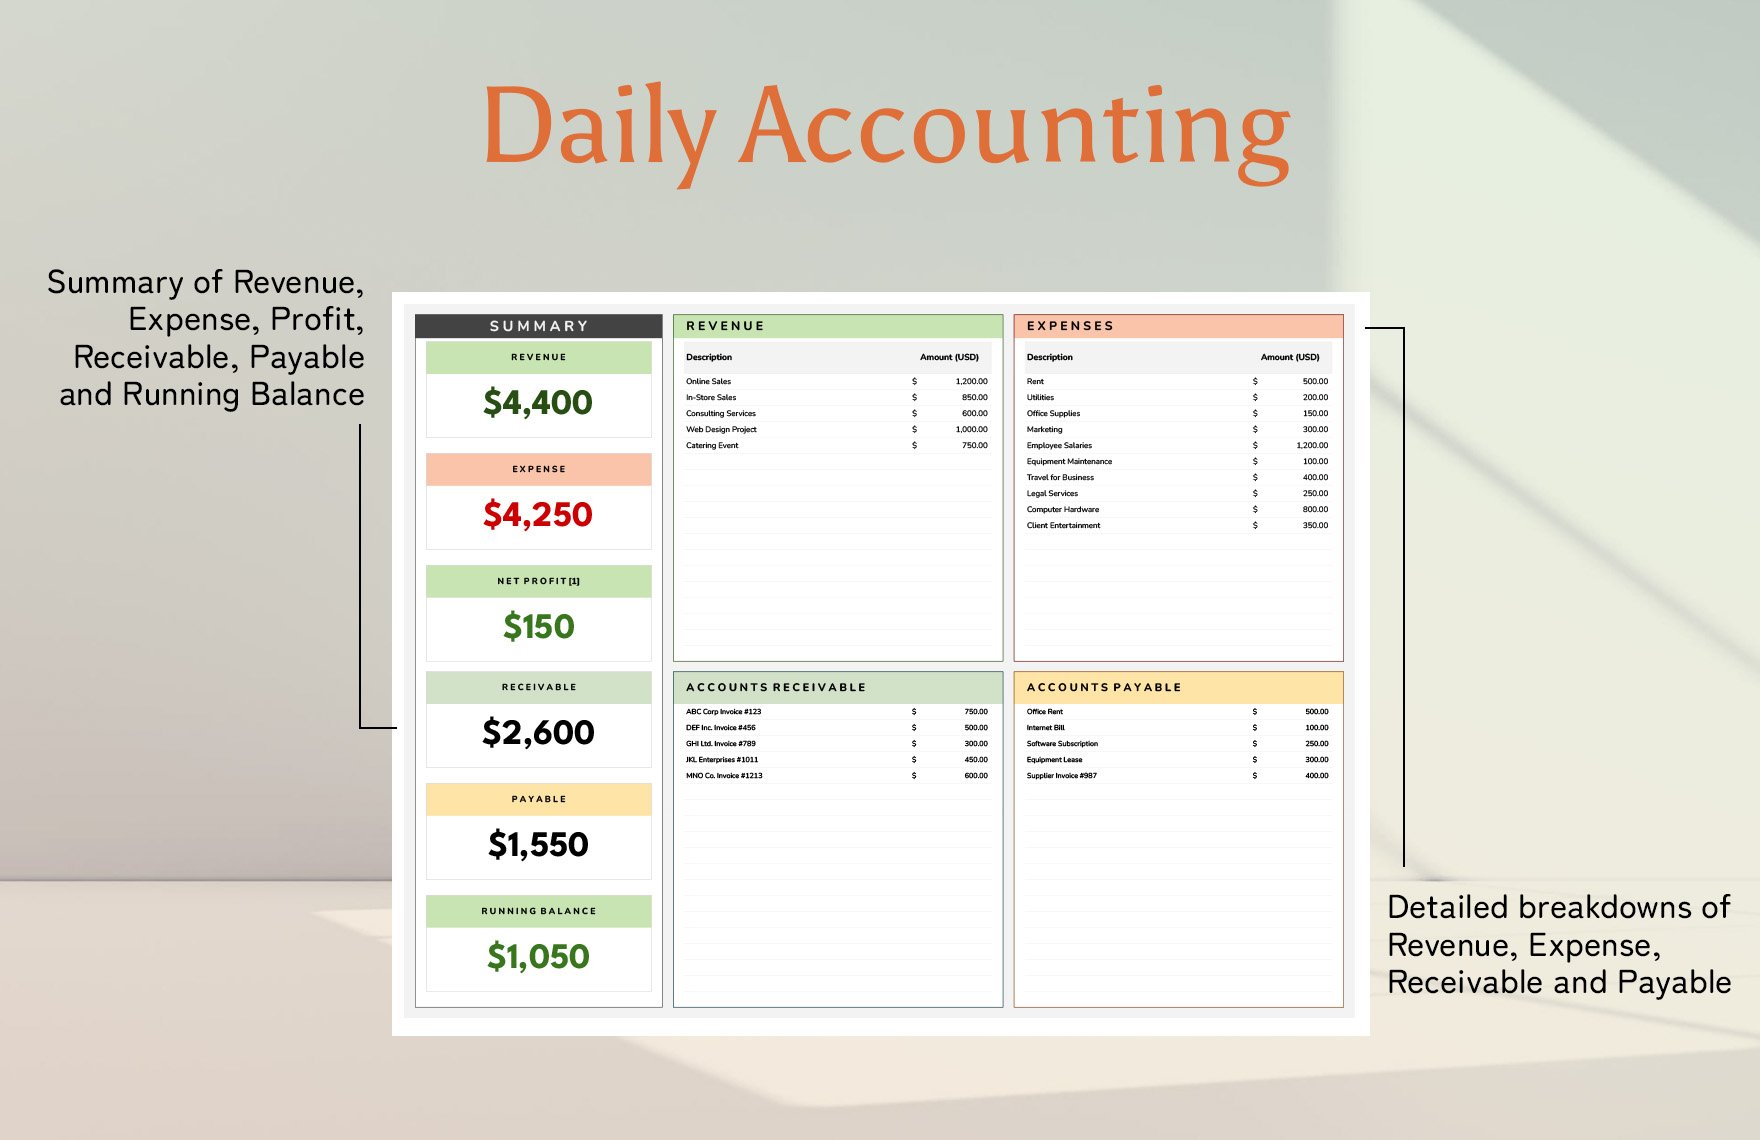
Advanced Nuances for Smaller Businesses
Most small business owners think they don't need daily accounting because they have few transactions. This is backwards reasoning. Fewer transactions means you should be doing daily accounting, not less. The low volume makes the practice sustainable. The real risk with low-volume businesses is infrequency. If you only touch your books once a month, you lose context about individual transactions quickly. A $300 software subscription purchase in November looks completely different in April than it did in November. Daily logging preserves that context automatically. Another counter-intuitive point: using a dedicated business credit card for all expenses actually makes daily accounting harder, not easier, if you're not careful. Every purchase hits the feed and needs matching. Multiple purchases at the same merchant in a single day often appear as a single batched transaction on the statement but multiple entries in your system. Matching one feed item to ten receipts is frustrating and error-prone. The solution is to keep a daily log of card purchases in a separate spreadsheet and reconcile that against the bank feed before entering anything into your accounting system. It adds fifteen minutes to your routine but prevents the duplicate entry problem that ruins quarterly reviews. And a final practical note: automating everything sounds great until it breaks. When your bank feed integration fails or your expense management tool stops syncing, you have no backup. Keep manual export options available. Download your bank statements weekly as PDFs and store them alongside your accounting records. Three years from now when the automated feed has a gap you can't explain, those PDFs will save you.