What Actually Happens When You Track Daily Expenses
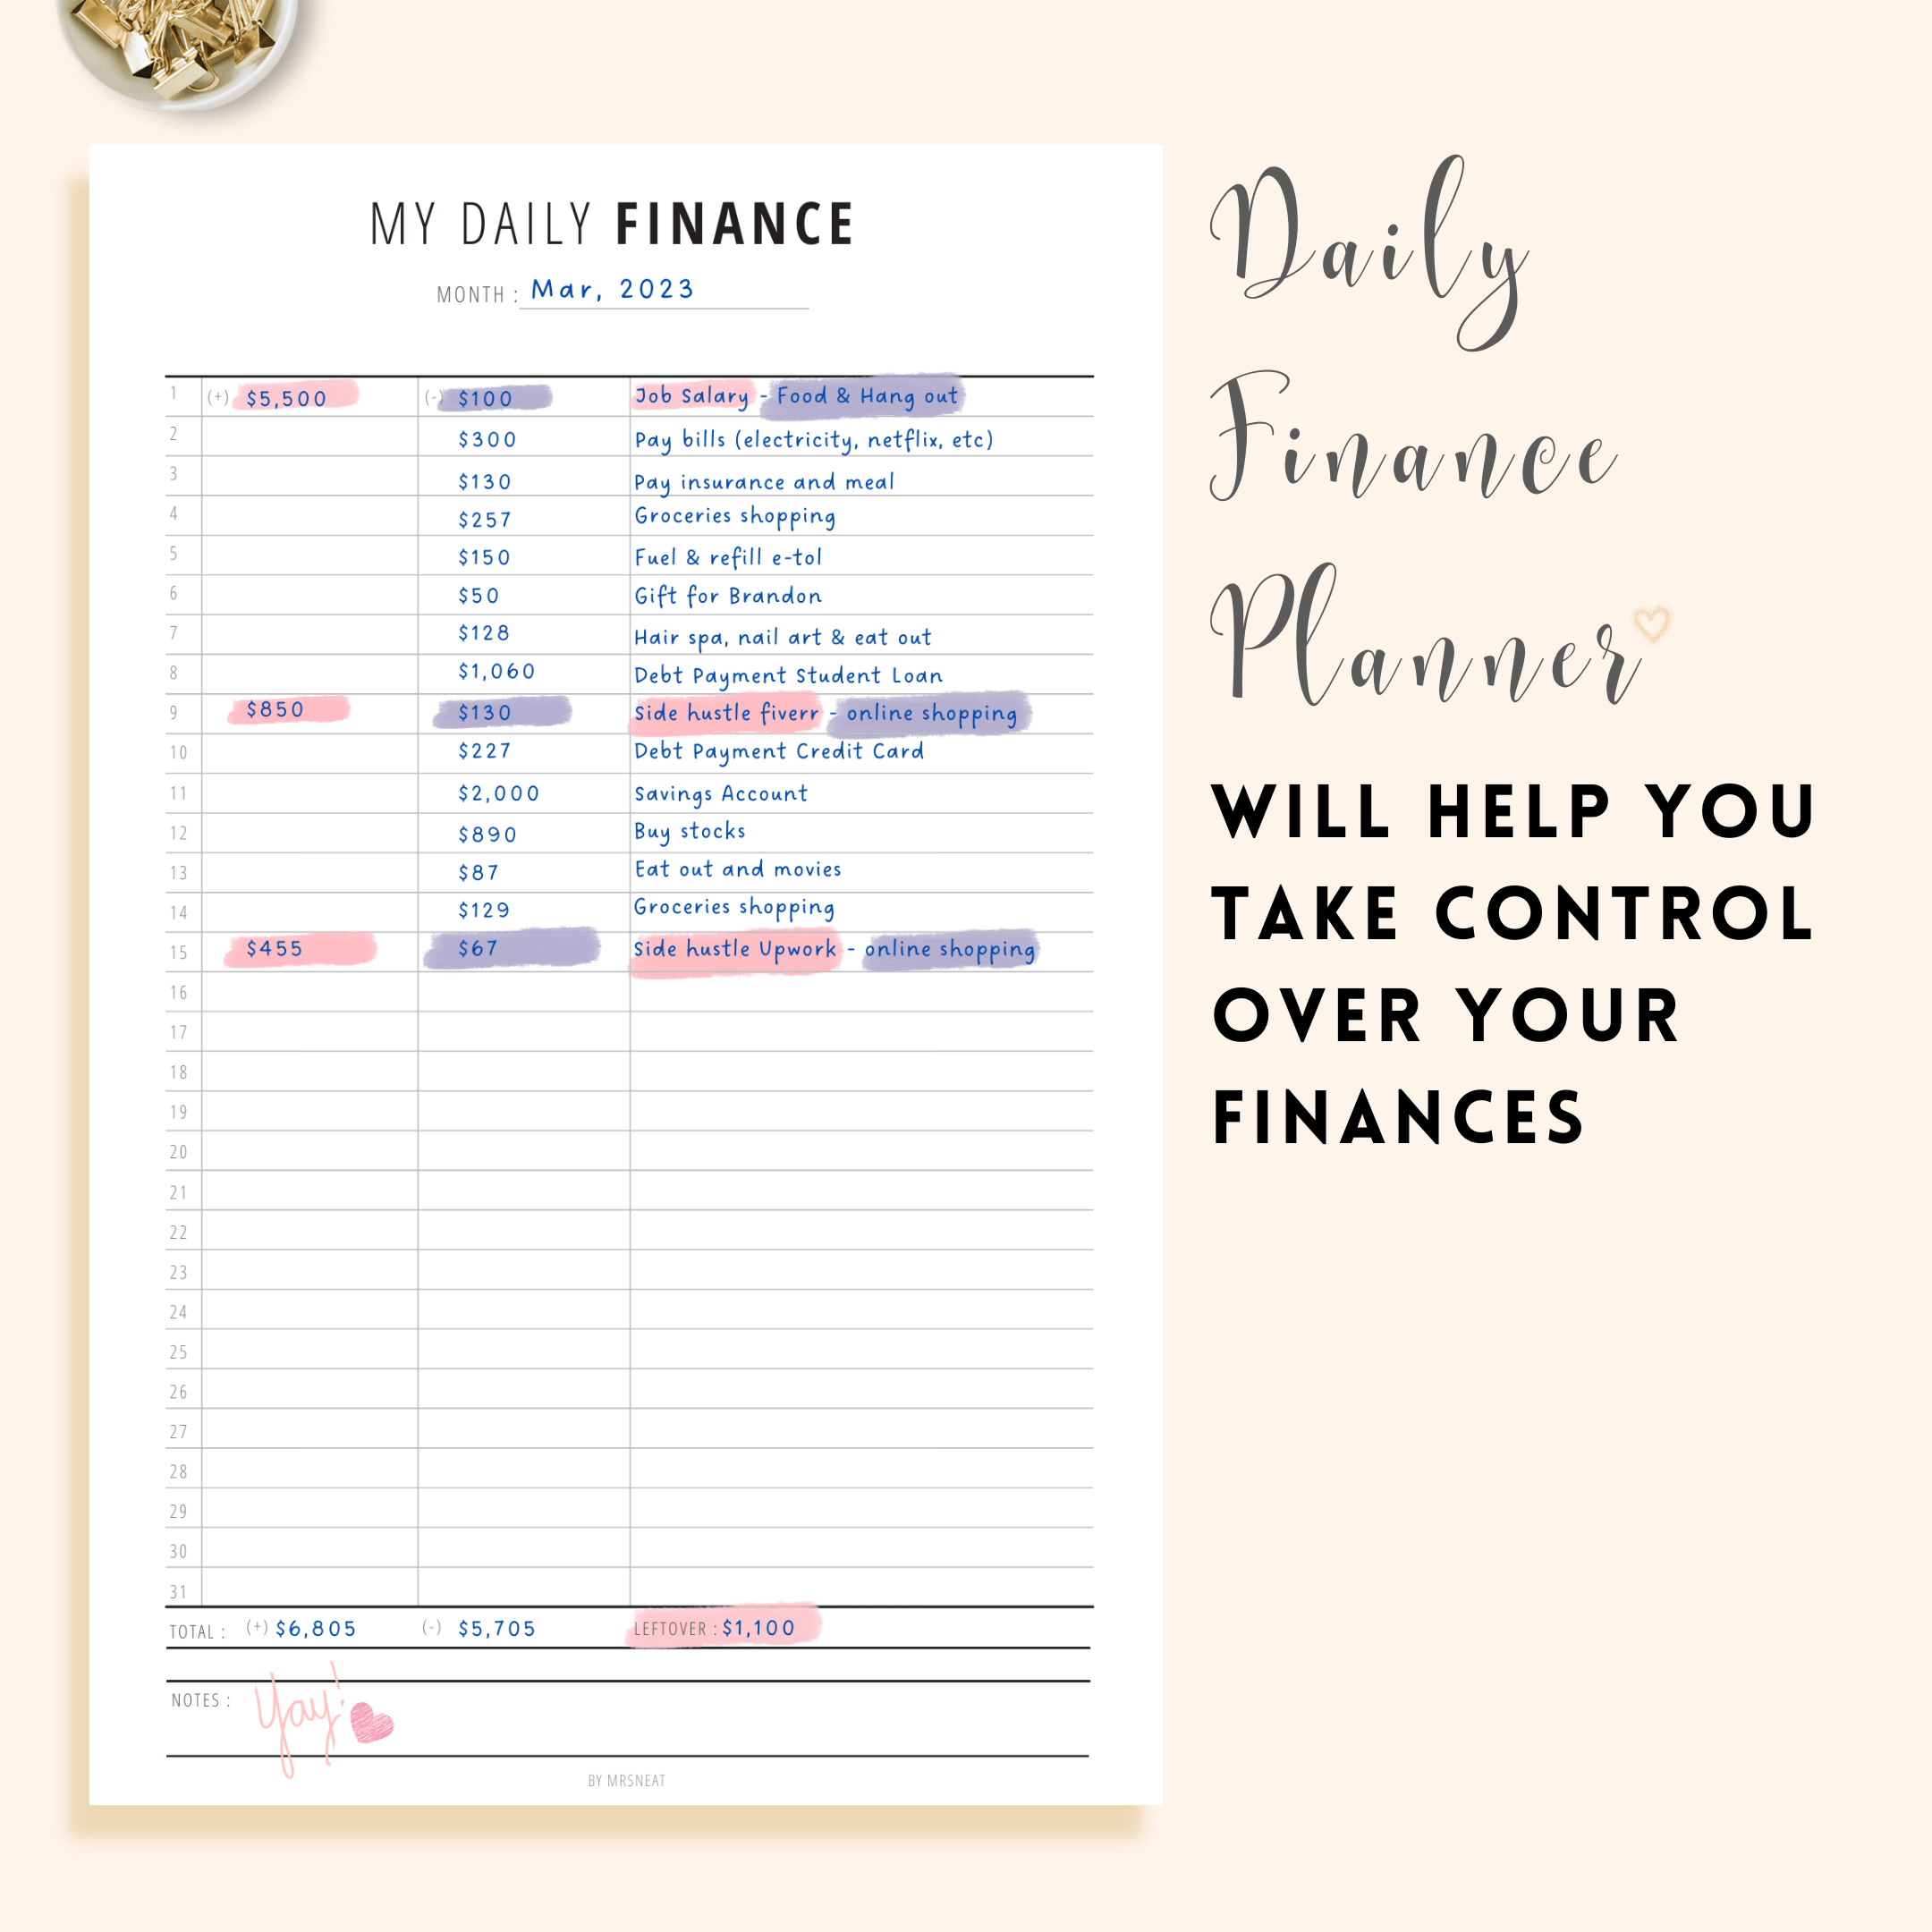
I spent about three years running a spreadsheet that automatically categorized every transaction from my checking account. It looked impressive on paper, but the reality was that I was spending more time fixing its breaks than actually thinking about my money. The core problem most people hit isn't complexity, it's that they treat budgeting like a tax form instead of a planning tool. A Daily Economics Planner is just a structured way to record where money goes and decide before the day starts what it should be doing instead. The first version I built had forty-four columns because I thought granularity meant accuracy. By week two I was entering data for seventeen minutes every morning and still didn't know if I could afford dinner with friends. The actual setup takes maybe twenty minutes total and needs far fewer categories than you expect. Start with three columns minimum: date, amount, and category. That's it. Add a fourth column for payment method if you use multiple cards, and a fifth for a note. Everything else is optional debt or luxury. I learned this the hard way when I tried to create subcategories for grocery spending like produce, dairy, meat, and pantry items. Within a month I had three thousand rows and couldn't distinguish between "groceries" and "restaurant food" because my categorization was inconsistent. The workaround was simple: I merged all five subcategories back into one line item and just made a habit of checking the receipt before logging. Accuracy improved immediately because I was actually reading receipts instead of guessing from memory.
Here's the template most people should use on day one.
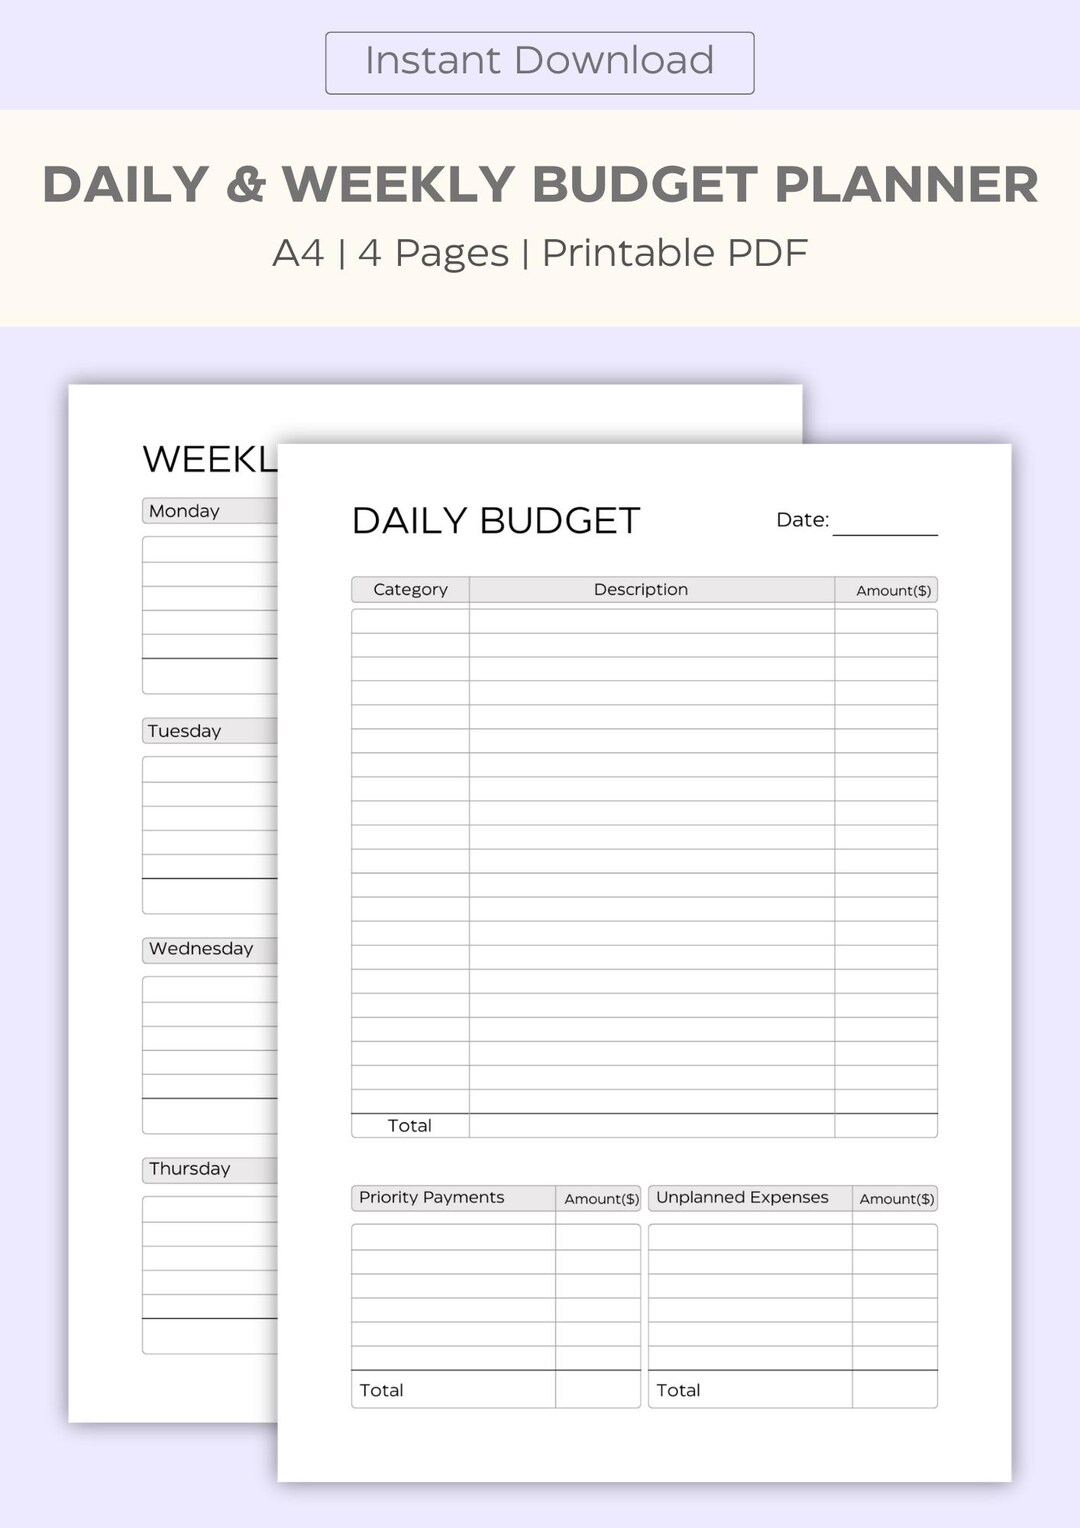
| Date | Amount | Category | Payment Method | Note |
|---|---|---|---|---|
| 2025-01-15 | $47.32 | Groceries | Debit Card | Weekly shop |
| 2025-01-15 | $14.50 | Transport | Cash | Bus pass top-up |
That's forty-two characters of structure doing what a fifty-thousand-dollar financial planning service claims to do. The difference is consistency, not sophistication. I tracked my spending faithfully for exactly forty-seven days before burning out. Not because the system was broken, but because I was treating it like a surveillance tool rather than a forecasting one. Every expense felt like a failure instead of data. The turning point came when I shifted from recording past behavior to planning tomorrow's boundaries. Instead of asking what I spent, I asked what I planned to spend before I opened my wallet. This inversion is the single most counter-intuitive thing beginners miss. Most guides tell you to track everything perfectly first, then analyze patterns later. The analysis never comes. The habit dies in the tracking phase. The people who stick with it for years, and I include myself now after nearly four years of continuous daily logging, do it by making tomorrow's plan before today's spending happens.
Get the Full Details
The practical workflow looks like this: each evening, review the next day's commitments, assign dollar amounts to each category, and lock it in. When a purchase happens, check it against the plan, not against some vague ideal of frugality. This takes about ninety seconds per day once you're fluent. The first week feels slower, closer to two or three minutes, because your brain is still learning to estimate. That's normal. It plateaus within ten days.
Common Pitfalls That Ruin Everything
The biggest trap is the rounding error. I started using exact cent precision because I thought it mattered. It doesn't. A twelve-dollar discrepancy over a year is meaningless noise. Round to the nearest dollar and save yourself thirty seconds per entry. Your annual summary will be more accurate, not less, because you'll actually do it. Another failure mode is the emergency fund loophole. I built a category called "unexpected" and used it as a catch-all for anything I didn't want to admit was discretionary spending. Coffee shops, streaming subscriptions, impulse Amazon orders. It went straight there and my real spending habits stayed invisible. I fixed this by renaming the category to "miscellaneous" and forcing a hard rule: anything under eight dollars goes into a spending category, not an escape hatch. The discipline felt uncomfortable for about three weeks, then became automatic.
When a Daily Economics Planner Fails You
These systems don't work for every income structure. If your earnings vary by more than forty percent month to month, like commission-based sales or seasonal gig work, a flat daily budget becomes a source of anxiety instead of clarity. The planner keeps telling you to spend less than you earned, but last month you earned nothing and this month you earned twice your average. The math breaks emotionally even if it stays technically correct. In that case, switch to a percentage-based model instead of fixed amounts. Allocate fifteen percent to housing, twenty-five to necessities, fifteen to savings, and leave the rest unstructured. This usually cuts the planning time in half and reduces the mental load enough that people actually maintain it past the first quarter. I recommended this shift to a client who was a freelance graphic designer with wildly inconsistent income. She went from quitting after six weeks to running a continuous system for eighteen months, and she credited the percentage approach with removing the shame cycle that killed her first attempt. There's also a hard ceiling on what this tool can do. A Daily Economics Planner will show you that you spent two hundred and thirty dollars on dining out last month. It will not tell you whether that spending was wise, whether you should cut back, or whether your real problem is stress eating at midnight. For those questions you need a different conversation, usually with a person who isn't a spreadsheet.

What to Actually Export for Year-End Review
Most people never look at their data again after entering it. The export function is where the value lives. At minimum, pull a quarterly summary by category. This usually takes about twelve minutes in any reasonable spreadsheet program. Filter by date range, pivot by category, and sum the amounts. The output tells you whether your grocery spending climbed seven percent year-over-year while your entertainment budget stayed flat. That single number, seven percent, is worth more than the entire three hundred and sixty-five days of raw entries. For a deeper look, calculate your cost per earning hour. Take your total non-essential spending and divide by your approximate hourly wage. If you make twenty-two dollars an hour and spent one thousand eight hundred dollars on things that weren't bills or groceries, that's eighty-one hours of work. Eighty-one hours is a tangible number your brain understands better than a dollar figure. It turns abstract waste into concrete sacrifice, which is usually enough motivation to adjust without needing guilt.
The Bare Minimum Version That Actually Works
If the full system still feels like too much, do this instead. Open a blank document. Write today's date. Below it, list five dollar amounts for your categories: housing, food, transport, debt, and fun. That's five numbers, nothing more. At the end of the day, write what you actually spent under each line. Compare the two sets of numbers. If the actual exceeds the planned, note the reason in one sentence. That's it. I've seen people run this exact stripped-down version for years and accumulate enough data to retire early. The system isn't the spreadsheet. The system is the daily act of checking your plan against reality before you close your eyes. Everything else is decoration. Download the template if you want something pre-formatted, but honestly you don't need it. A grid with five columns and twenty rows fits on a napkin and does the same job. The only thing worth downloading is the habit itself, and that one costs you nothing but eleven minutes tonight.