Why your grocery receipts are lying to you
The average household throws away between $1,500 and $2,500 a year without realizing it. I tracked my own spending for three months using a spreadsheet that looked nothing like the fancy budgeting apps everyone recommends. What I found was that most people understand basic supply and demand in theory but have no practical system for applying it to their actual purchases. Daily Economics Tricks isn't a product or an app. It is a set of mental models and habits for making better financial decisions with the money you already have. At its core, this approach focuses on marginal analysis in everyday decisions. Marginal cost and marginal benefit. You stop buying coffee at the shop when the enjoyment of that third cup is less than the $6 you would save instead. Sounds obvious until you realize most people don't actually do this calculation. They just spend. The trick is making the calculation automatic. I started applying this to something as simple as phone plans. My provider was charging me for data I wasn't using because I had bundled it into a family plan years ago without reassessing. I switched to a standalone plan and cut my bill from $140 to $78 monthly. That's $408 a year back in my pocket. Nobody told me to do this. I just looked at the marginal cost of each additional line and decided whether the convenience was worth the premium.
How I actually track this stuff
Here is the practical part. I use a simple four-question framework I wrote down on a sticky note and put above my monitor. Every time I consider a non-routine purchase over $50, I ask: What is the marginal cost? What is the marginal benefit? What am I giving up if I buy this? Is there a cheaper substitute that delivers 90% of the same benefit? The last question is where most people lose money. Substitutes are not always obvious. I spent years buying name-brand cleaning supplies because the store layout made the generic aisle feel secondary. One day I just walked to the back and compared ingredient lists. Bleach is bleach. The markup on the branded version was around 340%. I switched everything and noticed zero difference except in my bank account. For recurring expenses I do a quarterly audit. I pull every subscription, every auto-draft, every membership and list them with the date I signed up and the original reason I signed up. Half of them no longer match my current situation. My gym membership was something I joined during a New Year resolution period in 2019. I went maybe four times total that year. I canceled it the next day and haven't looked back. The mental gymnastics people do to justify keeping things they never use is genuinely surprising.
The sunk cost trap nobody talks about
This is the thing that trips people up most. Sunk cost fallacy. You keep doing something because you already invested in it, even though continuing makes no financial sense. I see this constantly with software subscriptions, extended warranties, and gym memberships. The money is already gone. The only question that matters is whether spending more will improve your situation. I had a streaming service subscription for two years that I barely used. Not because I hated it. Because I was too tired after work to watch anything. But I kept paying because "I already paid for the year." That is irrational. I cancelled and refunded the remaining months. It took about eight minutes and I got my money back.
Get the Full Details

Opportunity cost in daily life
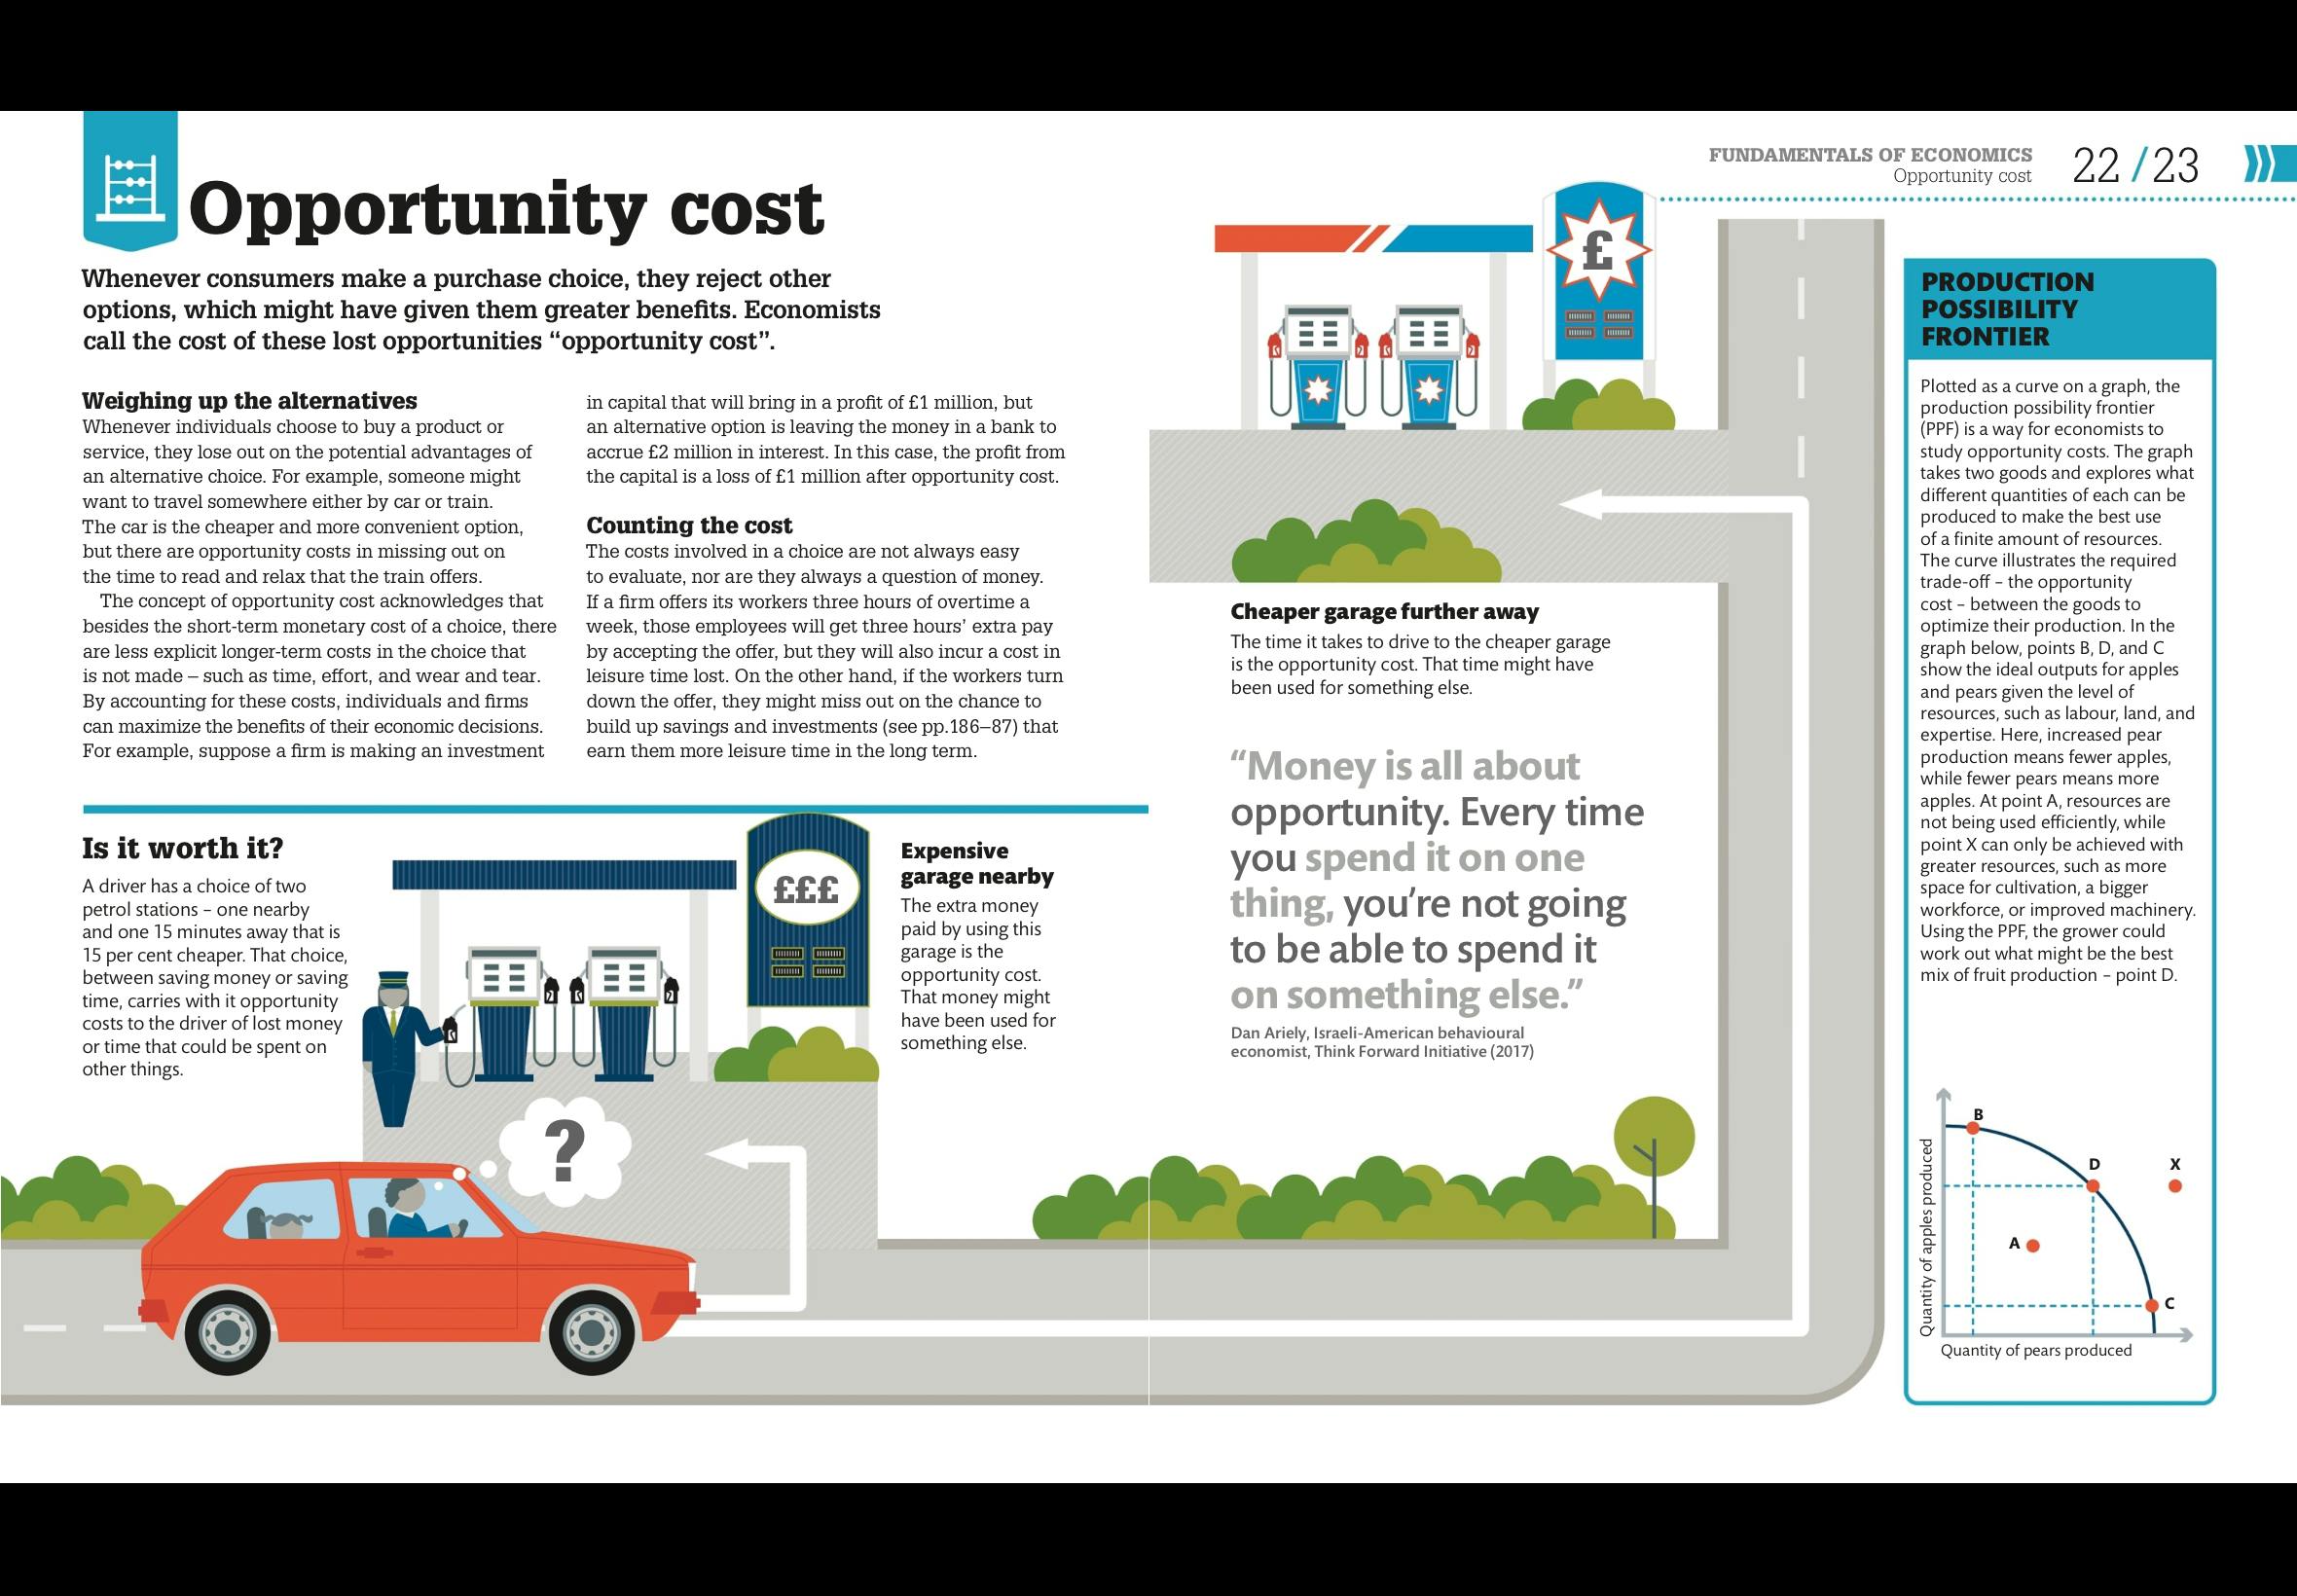
Every dollar has an alternative use. When you spend $12 on a lunch that you could make at home for $3, you are not just out $12. You are out $12 plus whatever that $12 could have earned if it stayed invested. Over a year, that adds up to significantly more than $108. Compound returns matter even on small amounts. I started calculating the annual investment value of my daily habits and it changed how I view routine spending. One edge case I ran into was with bulk purchasing. Buying in bulk sounds like a Daily Economics Tricks win, but it only works if you actually use everything before it expires. I bought a 24-pack of olive oil because it was 40% cheaper per ounce. I used about six bottles in two years. The rest went rancid. I lost money on the bulk deal. The rule is: bulk savings only count if your usage rate exceeds the expiration rate. Otherwise you are just prepaying for waste.
Advanced moves most people skip
Once you have the basics down, you can start looking at price elasticity and timing. Certain goods drop in price predictably. Electronics after January. Winter clothing in February. Airfare on Tuesday afternoons. I track these cycles in a notes app and set reminders. It is not glamorous but it works consistently. I also stopped buying things on Friday evenings. Bad habit from years ago. Late night shopping is real and it is expensive. My spending dropped about 22% after I simply committed to no non-essential purchases after 8 PM or on weekends. The impulse factor is huge and completely unnecessary.
When Daily Economics Tricks does not work
Let me be clear about the limitations. This system requires time and attention. If you are working two jobs or managing a household with serious logistical demands, the four-question framework might add friction rather than value. In those cases, automating decisions is better than optimizing them. Set up automatic transfers to savings. Use price tracking tools. Let the system handle the repetitive choices so you can focus on the ones that actually matter. There is also a point of diminishing returns. Spending an hour comparing seven different brands of pasta sauce to save $1.50 is not rational. The Daily Economics Tricks approach works best on purchases over $50, recurring subscriptions, and major decisions. For small daily items, use heuristic rules instead of full analysis. If it costs less than your hourly wage divided by ten, buy the convenient option and move on. I also should mention that some situations resist this framework entirely. Medical expenses, emergencies, and legal obligations do not respond to marginal analysis in useful ways. Do not try to optimize your way out of a crisis. These models are for everyday spending, not for emergencies where speed and access matter more than price.

The real takeaway is that awareness beats sophistication. You do not need a perfect system. You need to notice where your money goes and question whether each expense still serves you. Start with the sticky note. Track one category for a month. See what changes. Then add the next layer when you are ready.