
Why You Should Be Tracking Every Dollar Without Thinking About It
I started keeping a daily finance logbook about four years ago, mostly because my bank statements were a mess and I couldn't figure out where my money was going between paychecks. The actual process of setting one up takes about twenty minutes. You grab a notebook or a spreadsheet template, pick a category structure that matches your actual spending habits, and commit to writing one line per transaction every single day. The categories I settled on weren't theoretical either. I went through my last six months of bank exports, grouped my most frequent transactions by hand, and built the logbook around those groupings. That meant groceries, dining out, transport, subscriptions, utilities, and a wildcard category for anything that didn't fit neatly elsewhere. Having too many categories just leads to abandonment. That's something I learned after three weeks of filling in twelve different headers and giving up because it felt like homework.
How to Actually Build a Daily Finance Logbook
Start with whatever tool already exists in your life. If you live in Google Sheets or Excel, open a blank file. If you prefer paper, get a small ruled notebook that fits in your coat pocket. The medium doesn't matter nearly as much as the consistency of the entry habit. Set up columns for date, description, category, amount, and running balance. That's five columns. Anything more than that and you'll start skipping days. I had a friend who added seven columns including a notes field, a payment method field, a tag field, and a recurring flag. He made entries for eleven days and then stopped. Simplicity wins here. Always. Every time you spend money or receive income, write it down immediately. Not at the end of the day. Not when you remember. Immediately. The gap between the transaction and the entry is where most people lose the data. Cash purchases are the worst offenders because there's no digital trail to fall back on later. I started snapping a photo of every receipt I received for the first month while I was still building the habit, just as insurance. That photo stash came in handy exactly once, six weeks in, when I had to dispute a card charge that didn't match anything in my log.
At the end of each week, add up the totals by category and compare them against your budget if you have one. This isn't supposed to be punitive. It's just a weekly check-in, like looking under the hood of your car. Takes about ten minutes. The insight you get from seeing that you spent four hundred dollars on food in a single week is the kind of thing that changes behavior faster than any app notification ever will. I ran into a specific edge case about two years into using this system. I travel frequently for work and would buy meals, tips, and small purchases on a personal card that I also used for regular spending. At the end of the month, I'd have to sort through forty or fifty entries just to separate business expenses from personal ones for expense reports and tax purposes. It took me roughly forty-five minutes each time. The workaround was straightforward but something I wish I'd thought of sooner: I added a simple flag column. An F for personal and a B for business. Now the same process takes me about five minutes because I'm filtering rather than reading every line.
Get the Full Details
Common Mistakes That Kill This Habit
The biggest mistake I see people make is trying to use a logbook as a budget enforcement tool instead of a tracking tool. Those are different things. A budget tells you what you should spend. A logbook tells you what you actually spent. When you try to force the logbook to do both at the same time, it becomes stressful and you quit. Just track. Let the numbers speak for themselves. You'll naturally adjust your spending when you see the actual numbers staring back at you every Sunday evening. Another mistake is importing old transaction history and filling it all in upfront. I did this once. Filled in about three months of bank data across two weekends. By Monday I was already behind because real life didn't stop while I was catching up on historical entries. The backlog felt overwhelming and I just stopped. Start from today. Right now. Old data is noise. The pattern you need to catch is what happens going forward, not what happened six months ago when your rent was different and you had a different job. There's also the spreadsheet bloat problem. People add more and more fields over time. A notes section here. A recurring payments column there. Tags, priorities, savings goals per transaction, even a mood field once. I saw a Notion setup online where someone tracked their daily spending alongside their meditation streaks and workout calories. That's not a finance logbook. That's a life dashboard. It's impressive until it isn't used. Keep it narrow and boring.
What This System Actually Does and Doesn't Do
A Daily Finance Logbook will make you aware of spending patterns you didn't know you had. I discovered through one month of entries that I was spending approximately two hundred dollars per month on convenience store snacks and drinks. Not because I was hungry. Because I walked past the same store twice a day on my commute and bought something without thinking. That awareness alone cut that expense down to under sixty dollars the following month without any major lifestyle change. The logbook just made the invisible visible. It will also surface subscription drift. I had seven different streaming services and hadn't opened half of them in weeks. The logbook made that obvious when the monthly debits stacked up on the same date each month. Canceling three of them freed up about eighty dollars a month that I redirected into a savings account. What it won't do is optimize your investments or negotiate your bills. If you're looking for someone to automatically find better rates or move your money around, this isn't it. It's a mirror, not an advisor. The value is in the clarity, not the automation.
There are also clear limitations. Cash-based economies, tip-heavy service industries, and gift exchanges don't always map cleanly onto a spreadsheet row. I once spent about three weekends untangling a tangle of cash gifts, shared household expenses with my partner, and split dinners with friends just to get my monthly numbers right. Some categories resist neat categorization and that's okay. The wildcard column exists for that reason. Don't force a square peg into a round hole just because you want your totals to look clean. Another limitation is that a logbook doesn't prevent overspending. It only records it. If you're looking for friction between the decision to buy and the act of buying, this won't give you that. Apps with pre-authorization limits or envelope budgeting systems do that differently. A logbook is retrospective by nature. The power is in the pattern recognition that comes from consistent recording, not in real-time enforcement. The best approach combines the logbook with one other system. Pair it with a simple monthly budget that sets soft caps on your top three spending categories. Or pair it with an automatic savings transfer that happens on payday before you see the money. The logbook tells you where things stand. The other system makes sure you're moving toward what matters. Using both together covers more ground than either one alone.
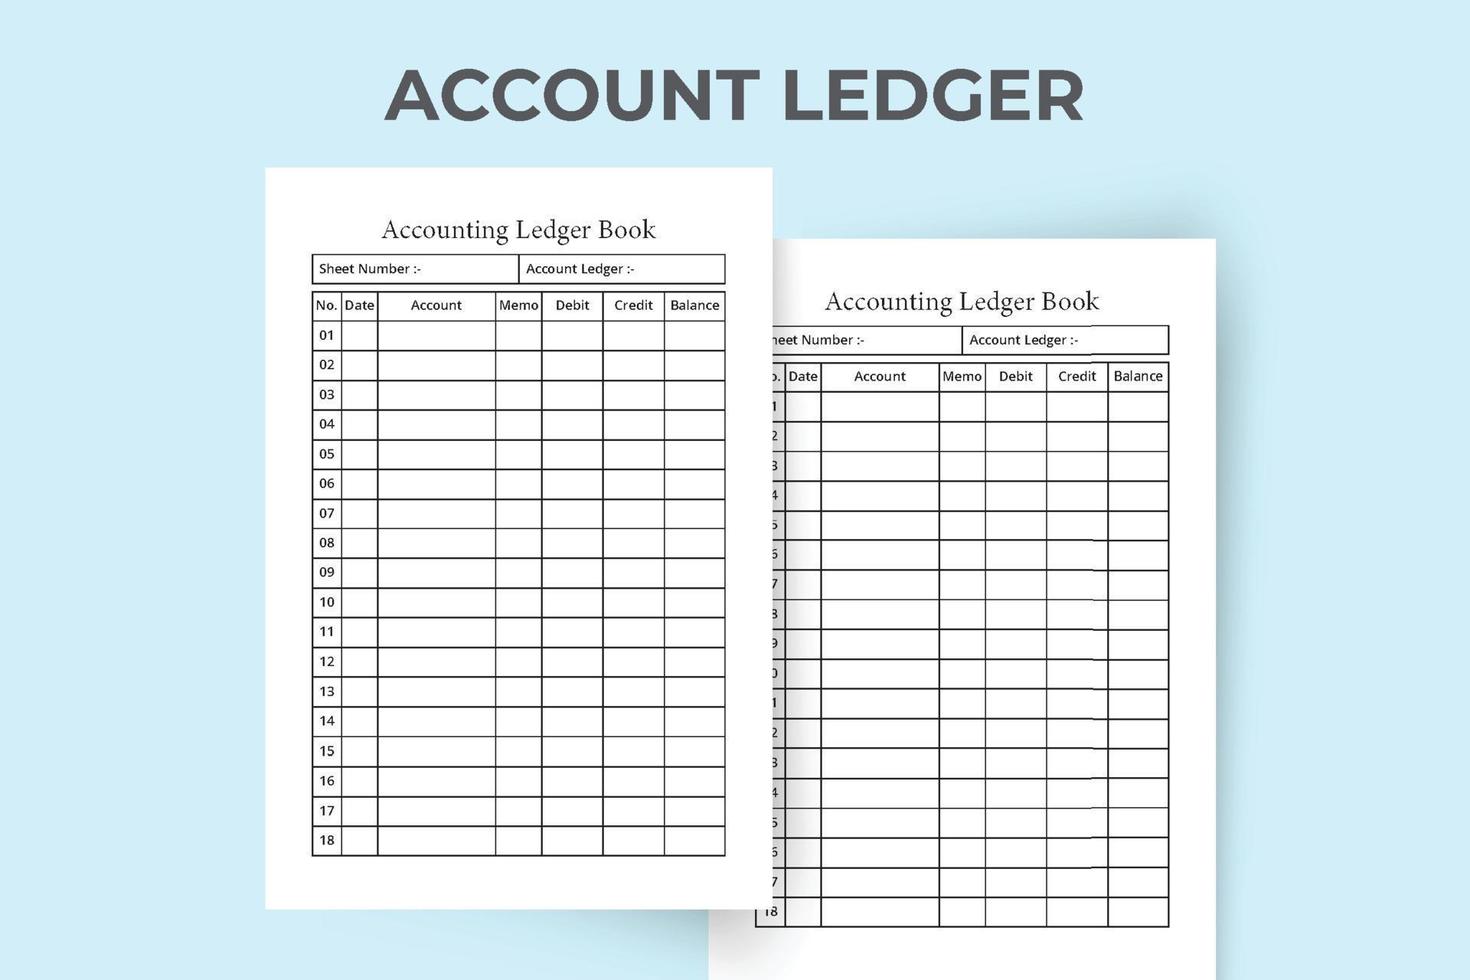
If you want a starting template, I can share a basic Google Sheets structure with the five-column layout and auto-sum formulas already set up. It's nothing fancy but it took me about fifteen minutes to build and it's been working for years without a single modification request. The point isn't the template. It's the daily habit. Everything else is just formatting.


