How I actually use a Daily Finance Planner without burning out
I used to think the problem with personal budgeting was that I didn't have enough information. It wasn't. The problem was the gap between wanting to track everything and actually doing the data entry before going to sleep. A Daily Finance Planner is a tracking system—spreadsheet, app, or notebook—where you log every dollar that goes out and comes in each day, ideally within twenty-four hours of the transaction. The difference between a weekly budget and a daily one is friction. Weekly means five days of spending pass before you look at anything. Daily means you see it before it compounds into a weekend you can't explain. The way I set mine up was through a combination of a shared Google Sheet and an app I already had. I imported my bank CSV exports directly into a master tab, then built a separate Daily Finance Planner view that only pulled uncategorized transactions and showed me what I had left to spend for the rest of the month. That last part is what most people miss. A budget that doesn't answer "how much can I spend today?" is just a history report. It tells you what happened. It doesn't help you make decisions. I've hit a specific wall with Daily Finance Planner setups that I think deserves its own mention. A few months ago I tried to automate recurring subscription charges by marking them as fixed expenses and letting the sheet deduct them automatically each day. It looked clean for two weeks. Then I realized the system was double-counting them because the subscription also appeared as a raw bank transaction every billing cycle, and my automation didn't know the difference between a recurring fixed expense and a new charge. The fix was simple but tedious: I stopped treating subscriptions as automatic deductions and started flagging them in a separate column with their next billing date. When the bank transaction came through, I matched it to the flagged entry and zeroed it out instead of letting it sit as a new spend. That took about an hour to restructure and about three minutes per month to maintain.
Why Daily Finance Planner Fails for Most People
It isn't the method. It's the data entry. If your workflow requires you to open your banking app, find a transaction, open your planner, and type it in manually, you will quit. The window between a purchase happening and you feeling motivated to log it is somewhere between four hours and three days, and the further out you push it, the less likely you are to remember the context. The correct fix isn't discipline. It's reducing the number of steps between the transaction and the planner. For me that meant turning my bank export into a single click. I scheduled my credit card and checking accounts to email CSV files every morning, then dropped them into a folder on Google Drive. A Power Query connection in my Daily Finance Planner sheet pulled them automatically. I then used a match function against my merchant list so 80 percent of entries categorized themselves. The remaining 20 percent I handled in a single sitting while my coffee was still hot. Total time: roughly four minutes per day.
The Part Nobody Warns You About
Daily tracking doesn't stop overspending. It makes overspending visible. That's different. When you're tracking weekly, you can absorb a bad Thursday through Saturday by assuming Friday will balance it out. When you're tracking daily, you see that Thursday was $47 over budget and you already spent Friday's and Saturday's allowance. You feel it immediately. That's the actual benefit of a Daily Finance Planner. It's not a prevention tool. It's a detection tool with a short feedback loop. Here's a nuance that seems small but breaks most beginners' systems: categorizing by spend type instead of by account. I set up my first planner with separate tabs for checking, credit card, and savings. That was backwards. Those are source accounts. What matters is where the money goes. Grocery, dining out, transit, entertainment, subscriptions, healthcare. When you group by spend type, you can compare apples to apples across all your accounts. When you group by account, you end up wondering why your checking account looks fine while your credit card balance is spiraling, because you're not seeing the aggregate picture. Another thing that catches people off guard: the carry-over day count. A month has 28, 29, 30, or 31 days. If your Daily Finance Planner divides your monthly budget by 30 and assumes every month has 30 days, you'll underbudget by roughly 3 to 7 percent depending on the month. I learned this the hard way in February. My planner told me I had $89 left for the month. I spent $61 and then hit a $40 grocery run on the 28th that pushed me into overdraft territory. The fix was a simple formula that divides your remaining budget by the number of days left in the actual month, recalculated every morning. It sounds like overkill until you see the numbers.
Get the Full Details

I also want to be blunt about where this approach breaks down. If you're paid irregularly—freelance work, tips, commission, seasonal income—a daily budget is almost impossible to calibrate without constant manual adjustment. The system will tell you you have money to spend one week and zero the next, which makes it feel unreliable even when it's just reflecting reality. In those cases, a weekly or biweekly tracker is more honest. A Daily Finance Planner isn't the right tool for variable income. It's a tool for steady income where the daily variance is noise, not signal. There's also a data-quality issue that most planners ignore. Bank feeds delay transactions. A purchase you made on Tuesday night might not appear until Wednesday afternoon. If you're closing out your day on Tuesday and a transaction is missing, your balance looks fine when it isn't. You need a buffer rule in your planner. I keep a rolling three-day buffer, meaning I don't treat any transaction as confirmed until it's been on my bank statement for 48 hours. It adds a small delay to your awareness, but it prevents the false-positive balance that makes people overconfident mid-month.
Practical Walkthrough
Here's what my actual morning routine looks like, because I think it's easier to understand than theory: First, I check my email for CSV exports from my bank and credit card. If they arrived, I drop them into the Drive folder. The sheet updates automatically. I open the Daily Finance Planner tab, filter for uncategorized transactions, and assign merchants where the automated categorization failed. Usually five to twelve entries. Second, I check the running balance for each budget bucket against the remaining days in the month. If dining out is $32 over with 12 days left, I know I need to pull back or accept that the bucket will need a top-up from another category. Third, I set my spending limit for the day using the remaining-balance-per-day formula. The planner shows me a number. I either approve it or I don't spend until tomorrow. This takes about four minutes. Four minutes a day, every day. Over a year that's roughly 24 hours. Most people spend more than that on a single tax filing. The question isn't whether it's worth the time. It's whether knowing exactly where your money goes every single day is worth more to you than whatever else you'd do with those 24 hours.
What to Look for in a Daily Finance Planner Template
If you're building your own, these are the structural elements that actually matter, not the decorative ones: Your planner needs an automatic recalculation engine. If you change your monthly budget, every day's remaining balance should update instantly. Manual formulas that don't cascade are useless. Second, you need a buffer line item for pending transactions—bank delays, holds, and pending authorizations. Third, you need a monthly view that isn't just a sum of daily rows. Sums don't tell you trends. You need a moving average of daily spend so you can spot acceleration before it becomes a problem. A $75 average over ten days feels fine. A $75 average that went from $45 to $75 to $110 over the same period is a warning sign, and the flat sum won't show it. Fourth, the planner should let you override categories without breaking the math. Sometimes a transaction genuinely doesn't fit. Food at a conference is business, not dining. Medical supplies from a pharmacy are healthcare, not groceries. If your system forces a category and you skip the transaction, you've lost data. If it lets you flag and reclassify later, you keep integrity.
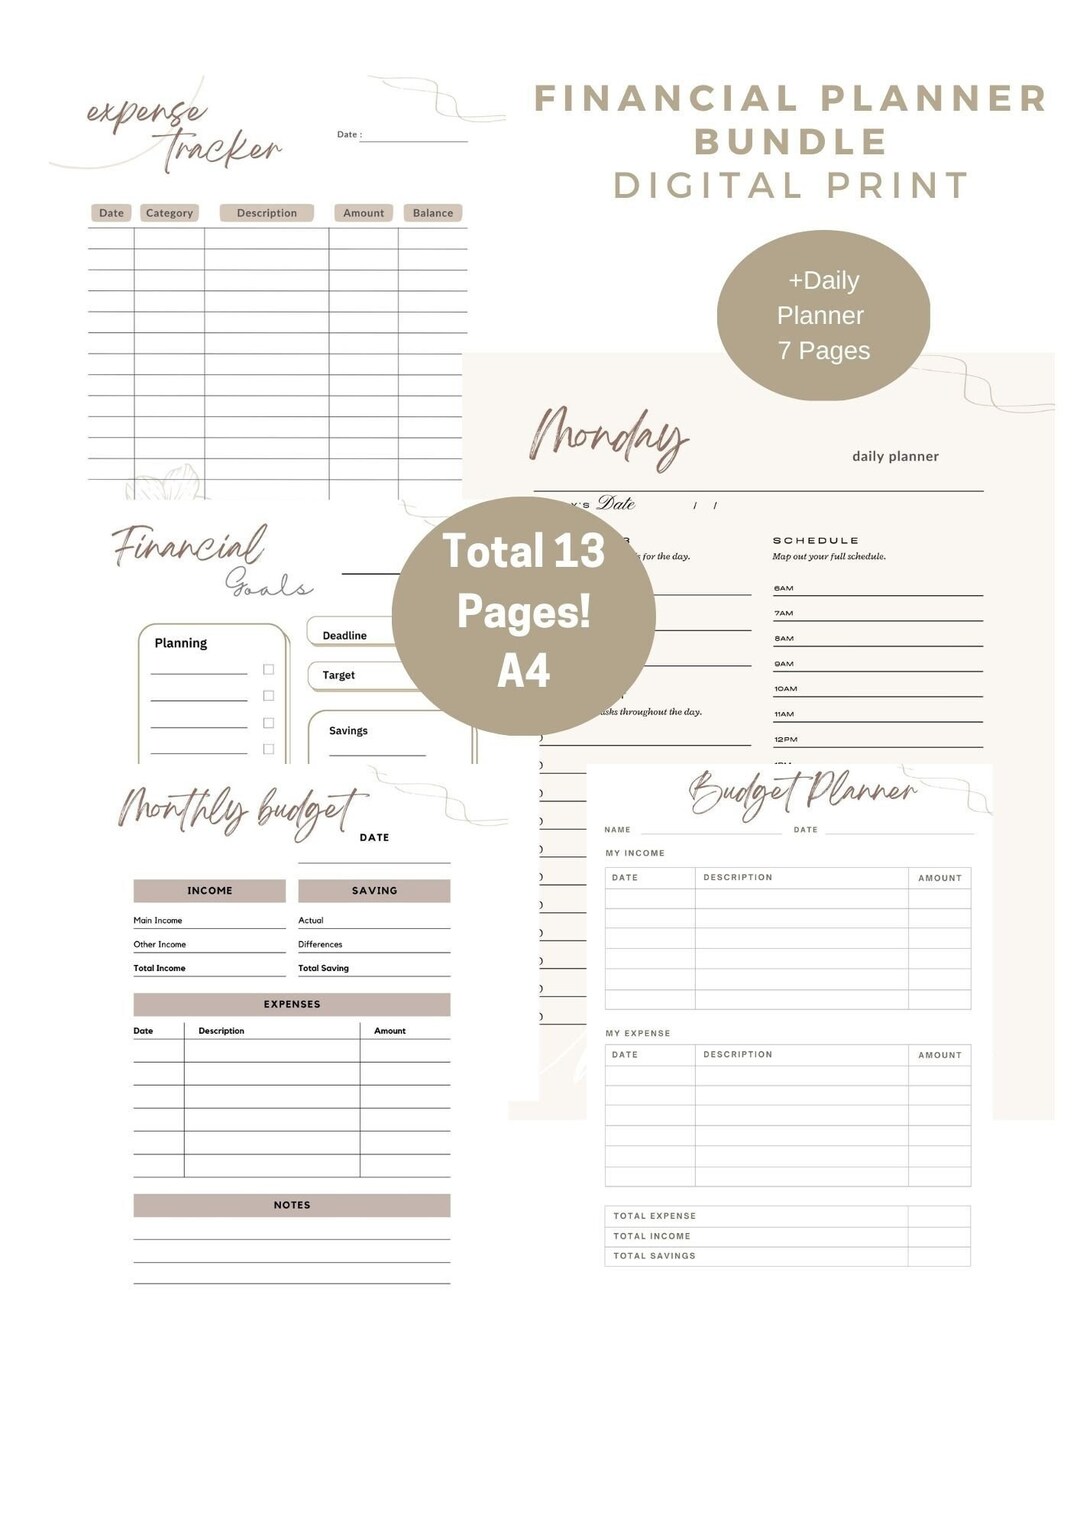
I don't have a direct download link for my personal version because it's tied to my specific bank formats and the way I handle joint-account splitting, which wouldn't generalize well. What I can point you toward is a solid starting template. Google Sheets has a community template called Monthly Budget with Spending Tracker that's close enough to build on. YNAB has a free trial that runs the same daily methodology but handles the aggregation for you. If you want something you can download and modify without a subscription, search for a Daily Budget Spreadsheet Google Sheets Community version and look for one that includes a remainder-per-day formula and a pending-transactions buffer. Anything simpler than that is a ledger, not a planner. One final practical note that probably sounds obvious but people skip it anyway: connect your Daily Finance Planner to your calendar. If you have a dentist appointment on Thursday that you know will cost $200 out of pocket, log that as a projected expense on Wednesday. It sounds like future-tripping, but it's just better data. A budget that only reflects past transactions is blind to known future costs. The system only gets smarter when you feed it forward-looking information, not just backward-looking receipts. The reason this works long-term isn't because it's elegant. It's because the feedback loop is short enough that mistakes don't compound into disasters. You catch a $40 lunch that shouldn't have happened on Tuesday instead of discovering it on the 30th when your rent payment is about to bounce. That's the actual value proposition. Everything else—automations, formulas, color-coded sheets—is just decoration on top of that core mechanism.