What Actually Happens When You Try to Follow Daily Finance Tips
Most of the advice floating around online about personal finance is either too generic to implement or written by people who haven't actually budgeted through a month with real expenses. The term Daily Finance Tips gets thrown around a lot on social media, YouTube, and content farms. It usually refers to small, actionable money habits you can check off every single day—tracking spending, automating savings, reviewing subscriptions, or adjusting your allocation by small increments. The concept isn't new. What's interesting is how it performs when you actually try to live it. I spent about fourteen months running a strict daily finance check every morning. I used a notes app at first, then moved to a spreadsheet, then tried three different budgeting apps before settling on something simple. Here's what the process looks like when it's not filtered through a wellness mindset. At its core, the method works on a feedback loop. You record money going out each day, compare it against a pre-set limit, and adjust tomorrow's behavior based on what you saw today. The psychology behind it is straightforward—people spend less when they're watching. That's the entire premise. But the execution is where things get messy.
You need a system that takes less than five minutes per session. If logging your daily expenses takes twenty minutes, you won't keep doing it. I learned this after about six weeks of burning out on a detailed spreadsheet where I categorized every transaction into sub-sub-categories. Nobody needs "miscellaneous dining" as a category. Just use broad buckets and move on.
Setting Up a Working System
Here's the setup I ended up using and still use occasionally. First, pick one app or tool you'll actually open every day. Not the most feature-rich one. The one with the least friction. For me, that was a plain note on my phone with five lines: spending today, total spent this month, remaining budget, any automatic charges coming up, and one thing I want to stop doing financially. The five-line format forces brevity. It also prevents the common trap of turning tracking into a second job. I watch a lot of people treat their budget like a full-time occupation, reorganizing categories, color-coding charts, building dashboards. That's not daily finance. That's a side project you'll abandon when it stops being fun.
Get the Full Details

What Beginners Miss About Daily Finance Habits
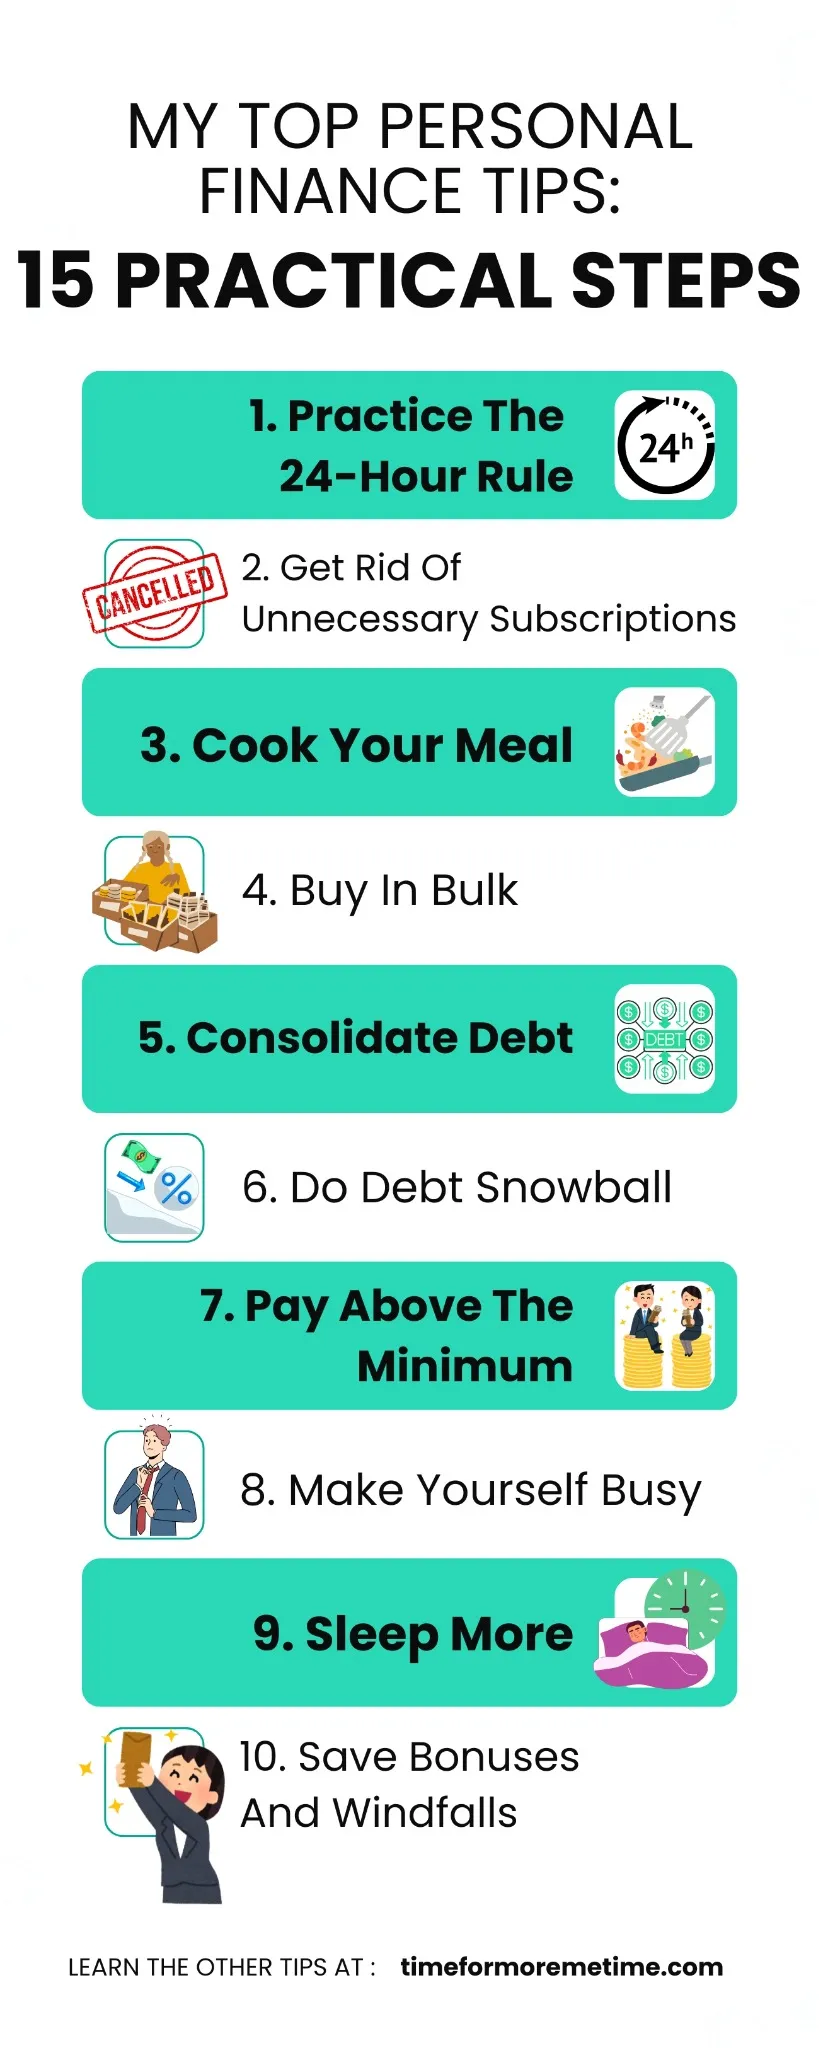
The biggest misconception is that consistency alone produces results. It doesn't. Consistency without adjustment is just repetitive documentation of the same mistakes. The actual value comes from the review-and-correct step. You have to catch patterns and interrupt them. I noticed a pattern after about eight weeks that I'd never seen in my monthly reviews. I was spending roughly forty percent of my discretionary income between Wednesday and Friday. Not Monday through Wednesday, not the whole week evenly. Just the mid-week stretch. When I dug into the data, it turned out to be a combination of lunch out with coworkers and impulse online purchases after work. Both correctable. The fix wasn't dramatic. I started packing lunch two days a week and installed a twenty-four-hour delay on all non-essential purchases over fifty dollars. The Wednesday-to-Friday bleed dropped to about twelve percent of discretionary spending within three weeks. Another counter-intuitive thing: the smaller the daily limit, the harder it is to sustain. I tried a daily spending cap of thirty dollars for a month and failed because it ignored reality. Some days I had to spend sixty. Some days ten. The average mattered more than the daily number. What I switched to was a weekly envelope system with a daily check-in. That removed the guilt of overspending on one day because the weekly total absorbed the variance. If you're setting daily limits, set them loose enough to breathe and tight enough to matter.
When Daily Finance Tracking Breaks Completely
There are scenarios where this approach fails outright, and you should know about them before committing to it. Irregular income is the biggest one. If you're a freelancer, commission-based worker, or run a business with seasonal revenue, daily budgeting becomes an exercise in guesswork. You can't meaningfully track daily spending when your daily income varies by three hundred percent from week to week. In those cases, monthly or project-based tracking works better. Don't force a daily routine onto an irregular cash flow. Another failure mode is financial crisis. If you're dealing with debt collection, unexpected medical bills, or a major income disruption, daily tracking is noise. You need triage, not habit formation. Prioritize stabilization first, then rebuild tracking habits once the emergency passes. I saw this play out with a friend who lost her job and kept up her daily finance routine for three weeks while simultaneously facing eviction. The routine gave her a false sense of control. She needed a debt negotiation call, not a spending log.
Tools That Actually Help Instead of Hurting
Most budgeting apps add complexity without adding insight. I tested YNAB, Mint's replacement options, Goodbudget, and a handful of others before landing on something unglamorous that works. The key features you actually need are: automatic transaction import, the ability to set a daily or weekly cap, a simple dashboard that shows remaining budget without digging, and export capability for tax season. Anything beyond that is entertainment. Rules engines, investment tracking, net worth dashboards, goal trackers that send you emails—these are nice to have. They're not daily finance essentials. They're also the features that slow you down and create friction. Every additional setting, every tutorial you need to watch, every notification you have to disable is one less reason to actually use the tool consistently.

A Practical Walkthrough
Here's what a real daily session looks like for me now, and it takes about four minutes. I open my app first thing, usually with coffee. I review yesterday's transactions and flag anything that looks wrong or missing. That's maybe ninety seconds. Then I look at today's projected spending based on automatic charges and planned purchases. Another minute. I check my remaining budget against the daily pace—if I'm on track, fine. If I'm behind, I adjust. That's the rest of the four minutes. I don't re-categorize. I don't analyze trends. I don't write notes unless something genuinely unusual happened. The trend analysis happens once a month, not daily. Daily review is for course correction. Monthly review is for pattern recognition. Mixing the two purposes is a common mistake that makes the daily habit feel heavier than it needs to be.
Why This Doesn't Replace Professional Advice
Daily finance tracking is a behavior tool. It changes how you interact with money moment to moment. It does not optimize your tax situation. It does not advise you on investment allocation. It does not help you negotiate with creditors or plan for retirement. Those require different frameworks and, in many cases, professional input. The daily habit is foundational, not comprehensive. It keeps you from setting fire to the floor while someone else works on the blueprint for the rest of the house. I've watched people use daily tracking as an excuse to avoid having hard conversations about money—avoiding discussions with partners about shared expenses, skipping annual financial reviews, pretending that consistent logging replaces actual planning. It doesn't. It's a maintenance habit. Maintenance keeps things running. It doesn't upgrade the system.
Building a Sustainable Version
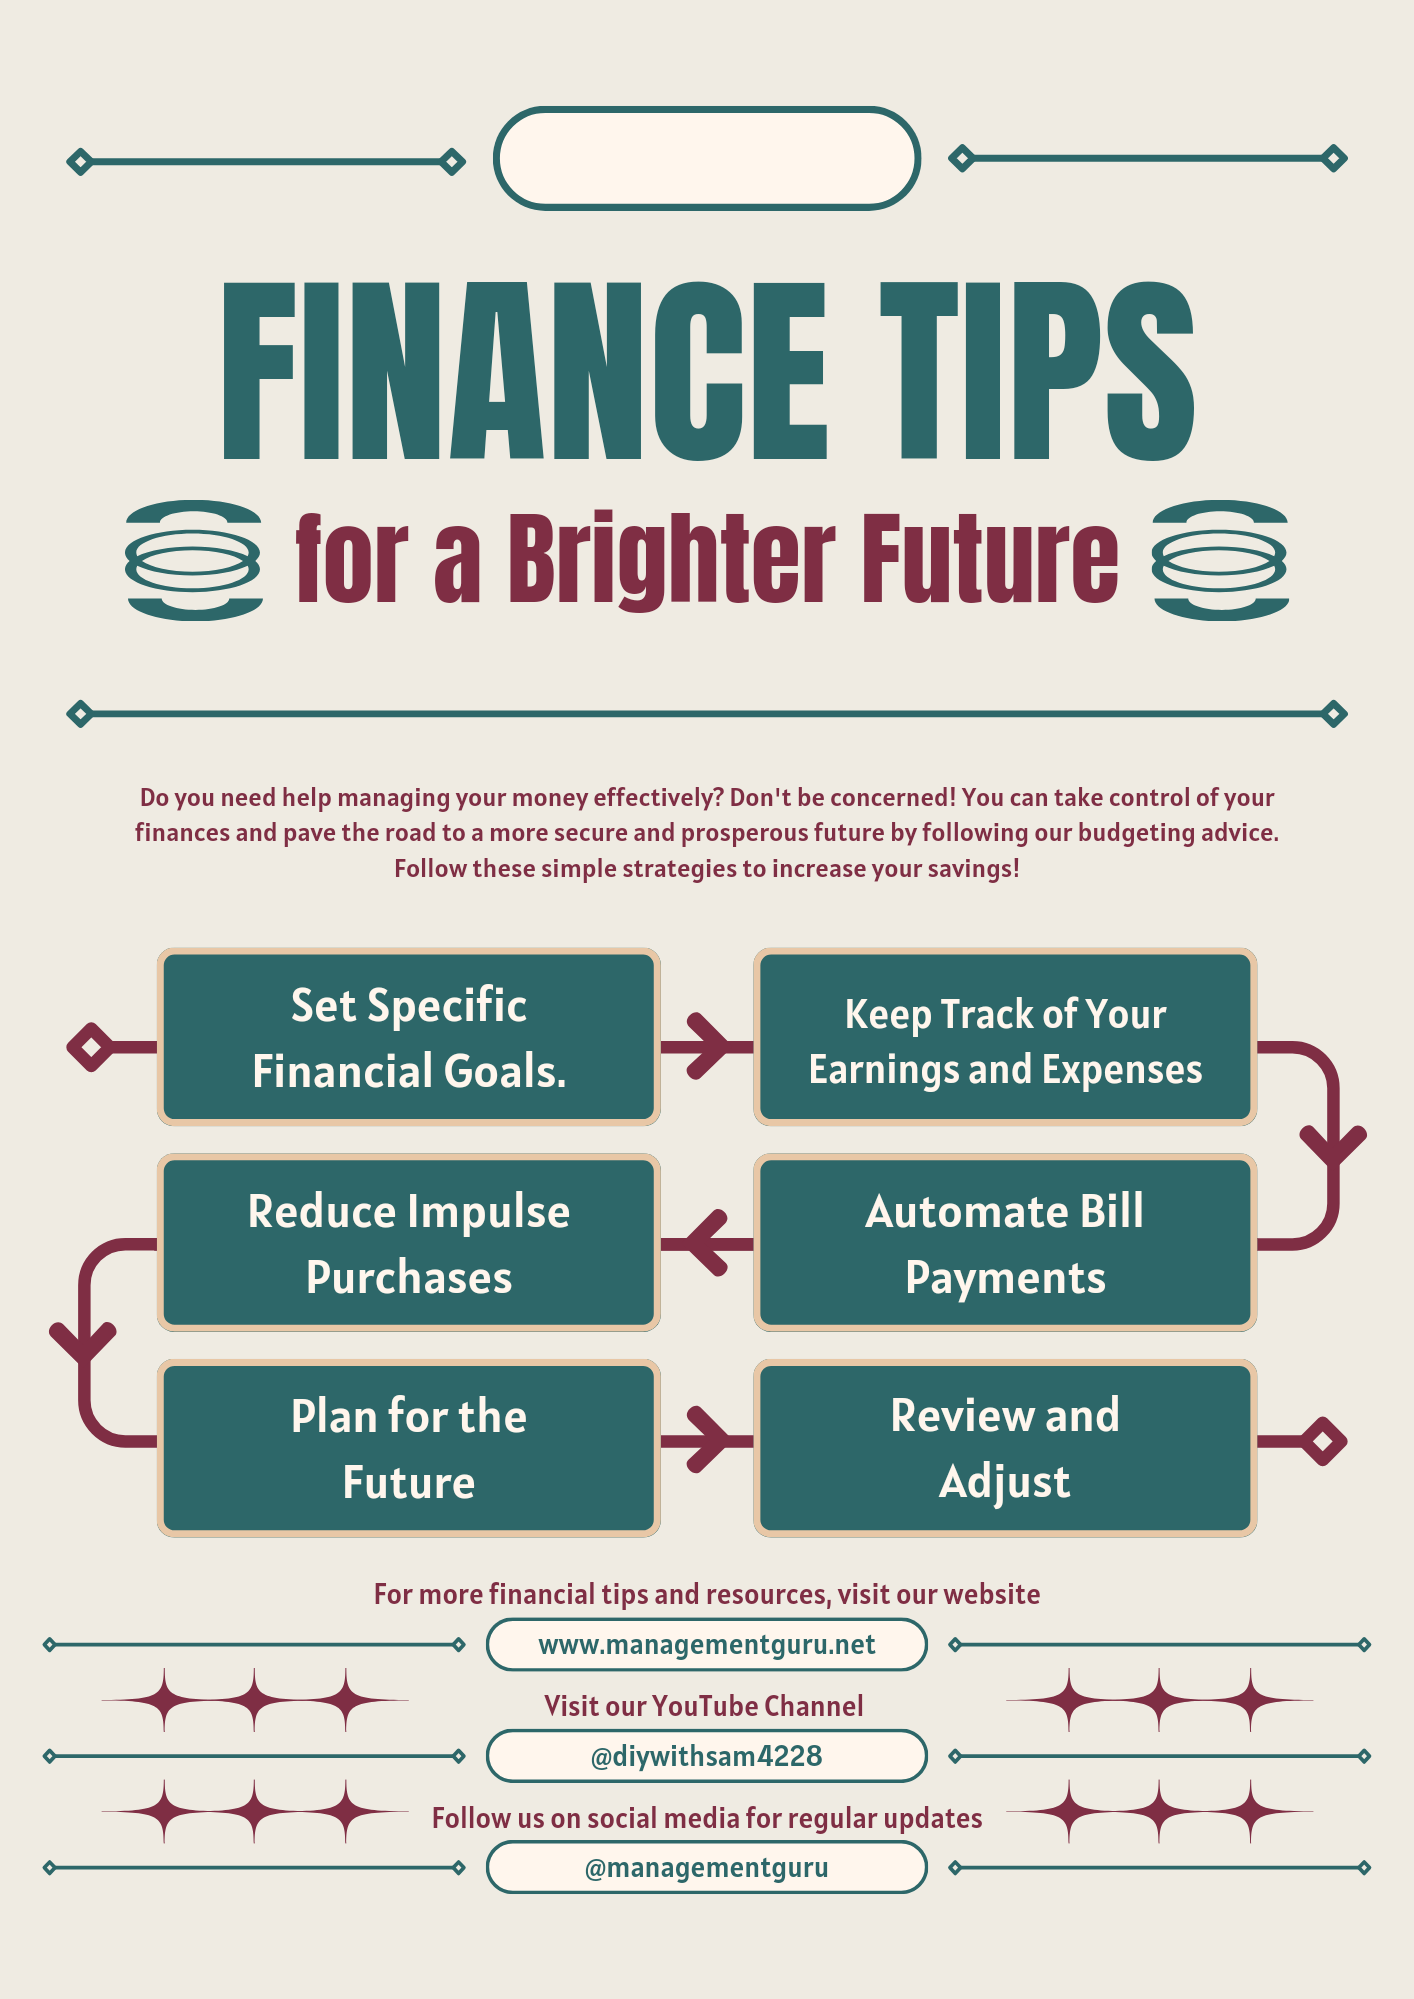
If you want to start, don't aim for perfection. Aim for continuation. Pick one day to begin, use the simplest tool available, and accept that you'll miss days. The people who succeed with daily finance tracking aren't the ones who never skip. They're the ones who skip three days and then come back without treating it like a failure. Guilt is the fastest way to kill a habit. Data is the slowest way to improve one. Start with the five-line check-in. Track your spending. Watch for the mid-week pattern. Set a weekly buffer instead of a rigid daily cap. Review monthly, not daily. And when life gets complicated, drop the daily habit temporarily and pick it back up when it makes sense again. That's the actual practice, stripped of the productivity theater that usually surrounds it.