How to Build a Working Daily Finance Tutorial Without Wasting Three Weeks
I spent about three weeks last year trying to assemble a usable Daily Finance Tutorial from scattered YouTube videos, Reddit threads, and a couple of paid courses I picked up on sale. It turned into a mess. The core problem isn't that the information doesn't exist — it's that nobody puts it in the same order, and the gaps between topics will eat you alive if you don't bridge them yourself. Here's what I ended up with and how it actually works in practice.
What a Daily Finance Tutorial Should Cover
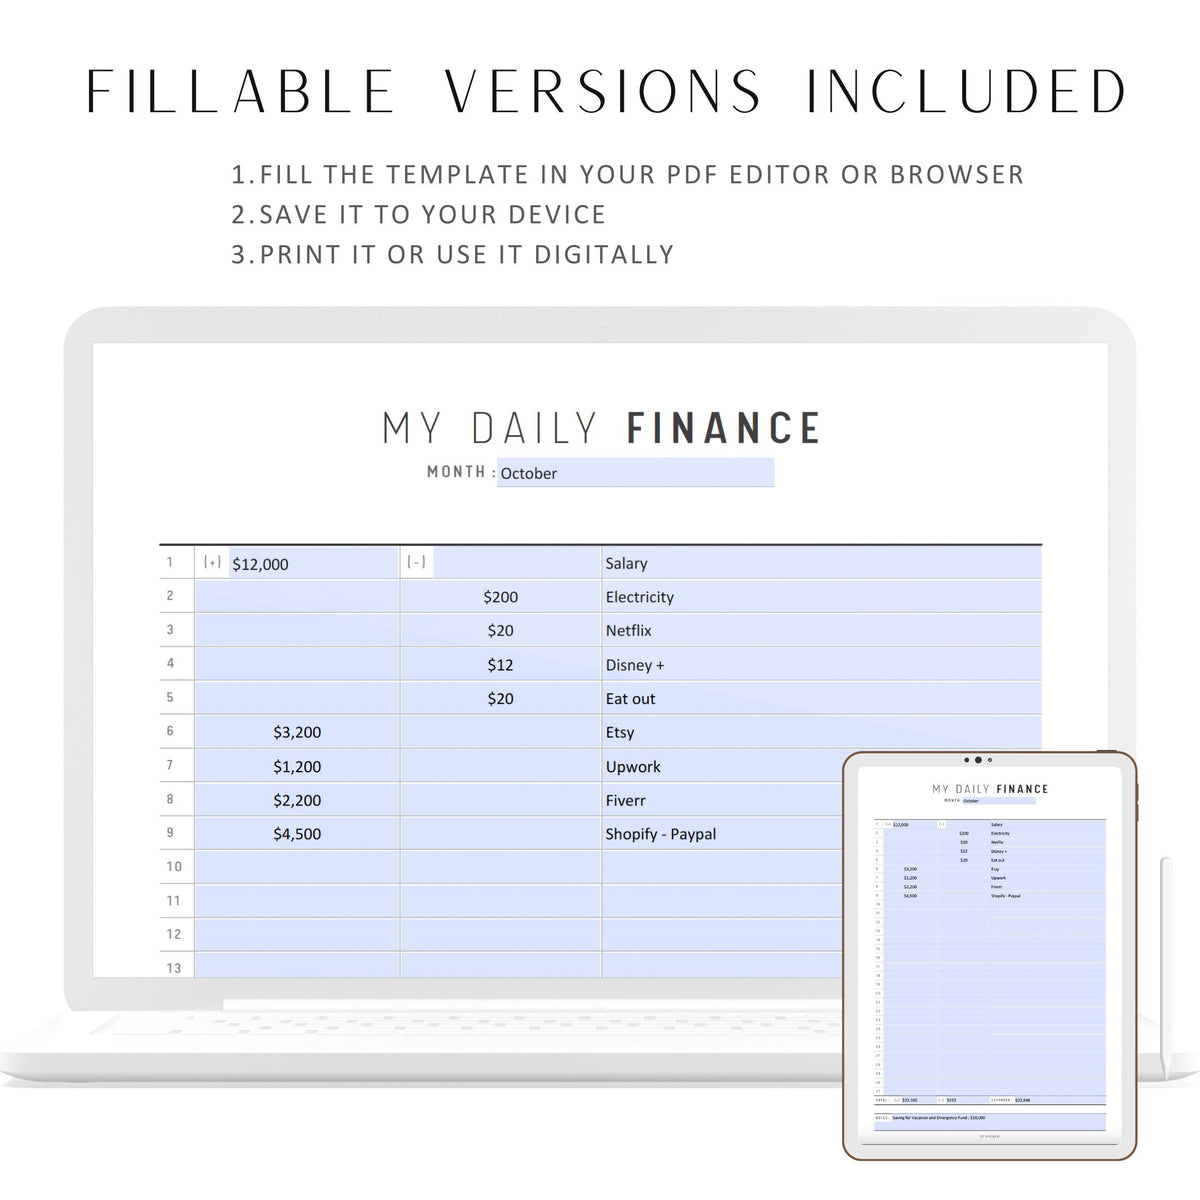
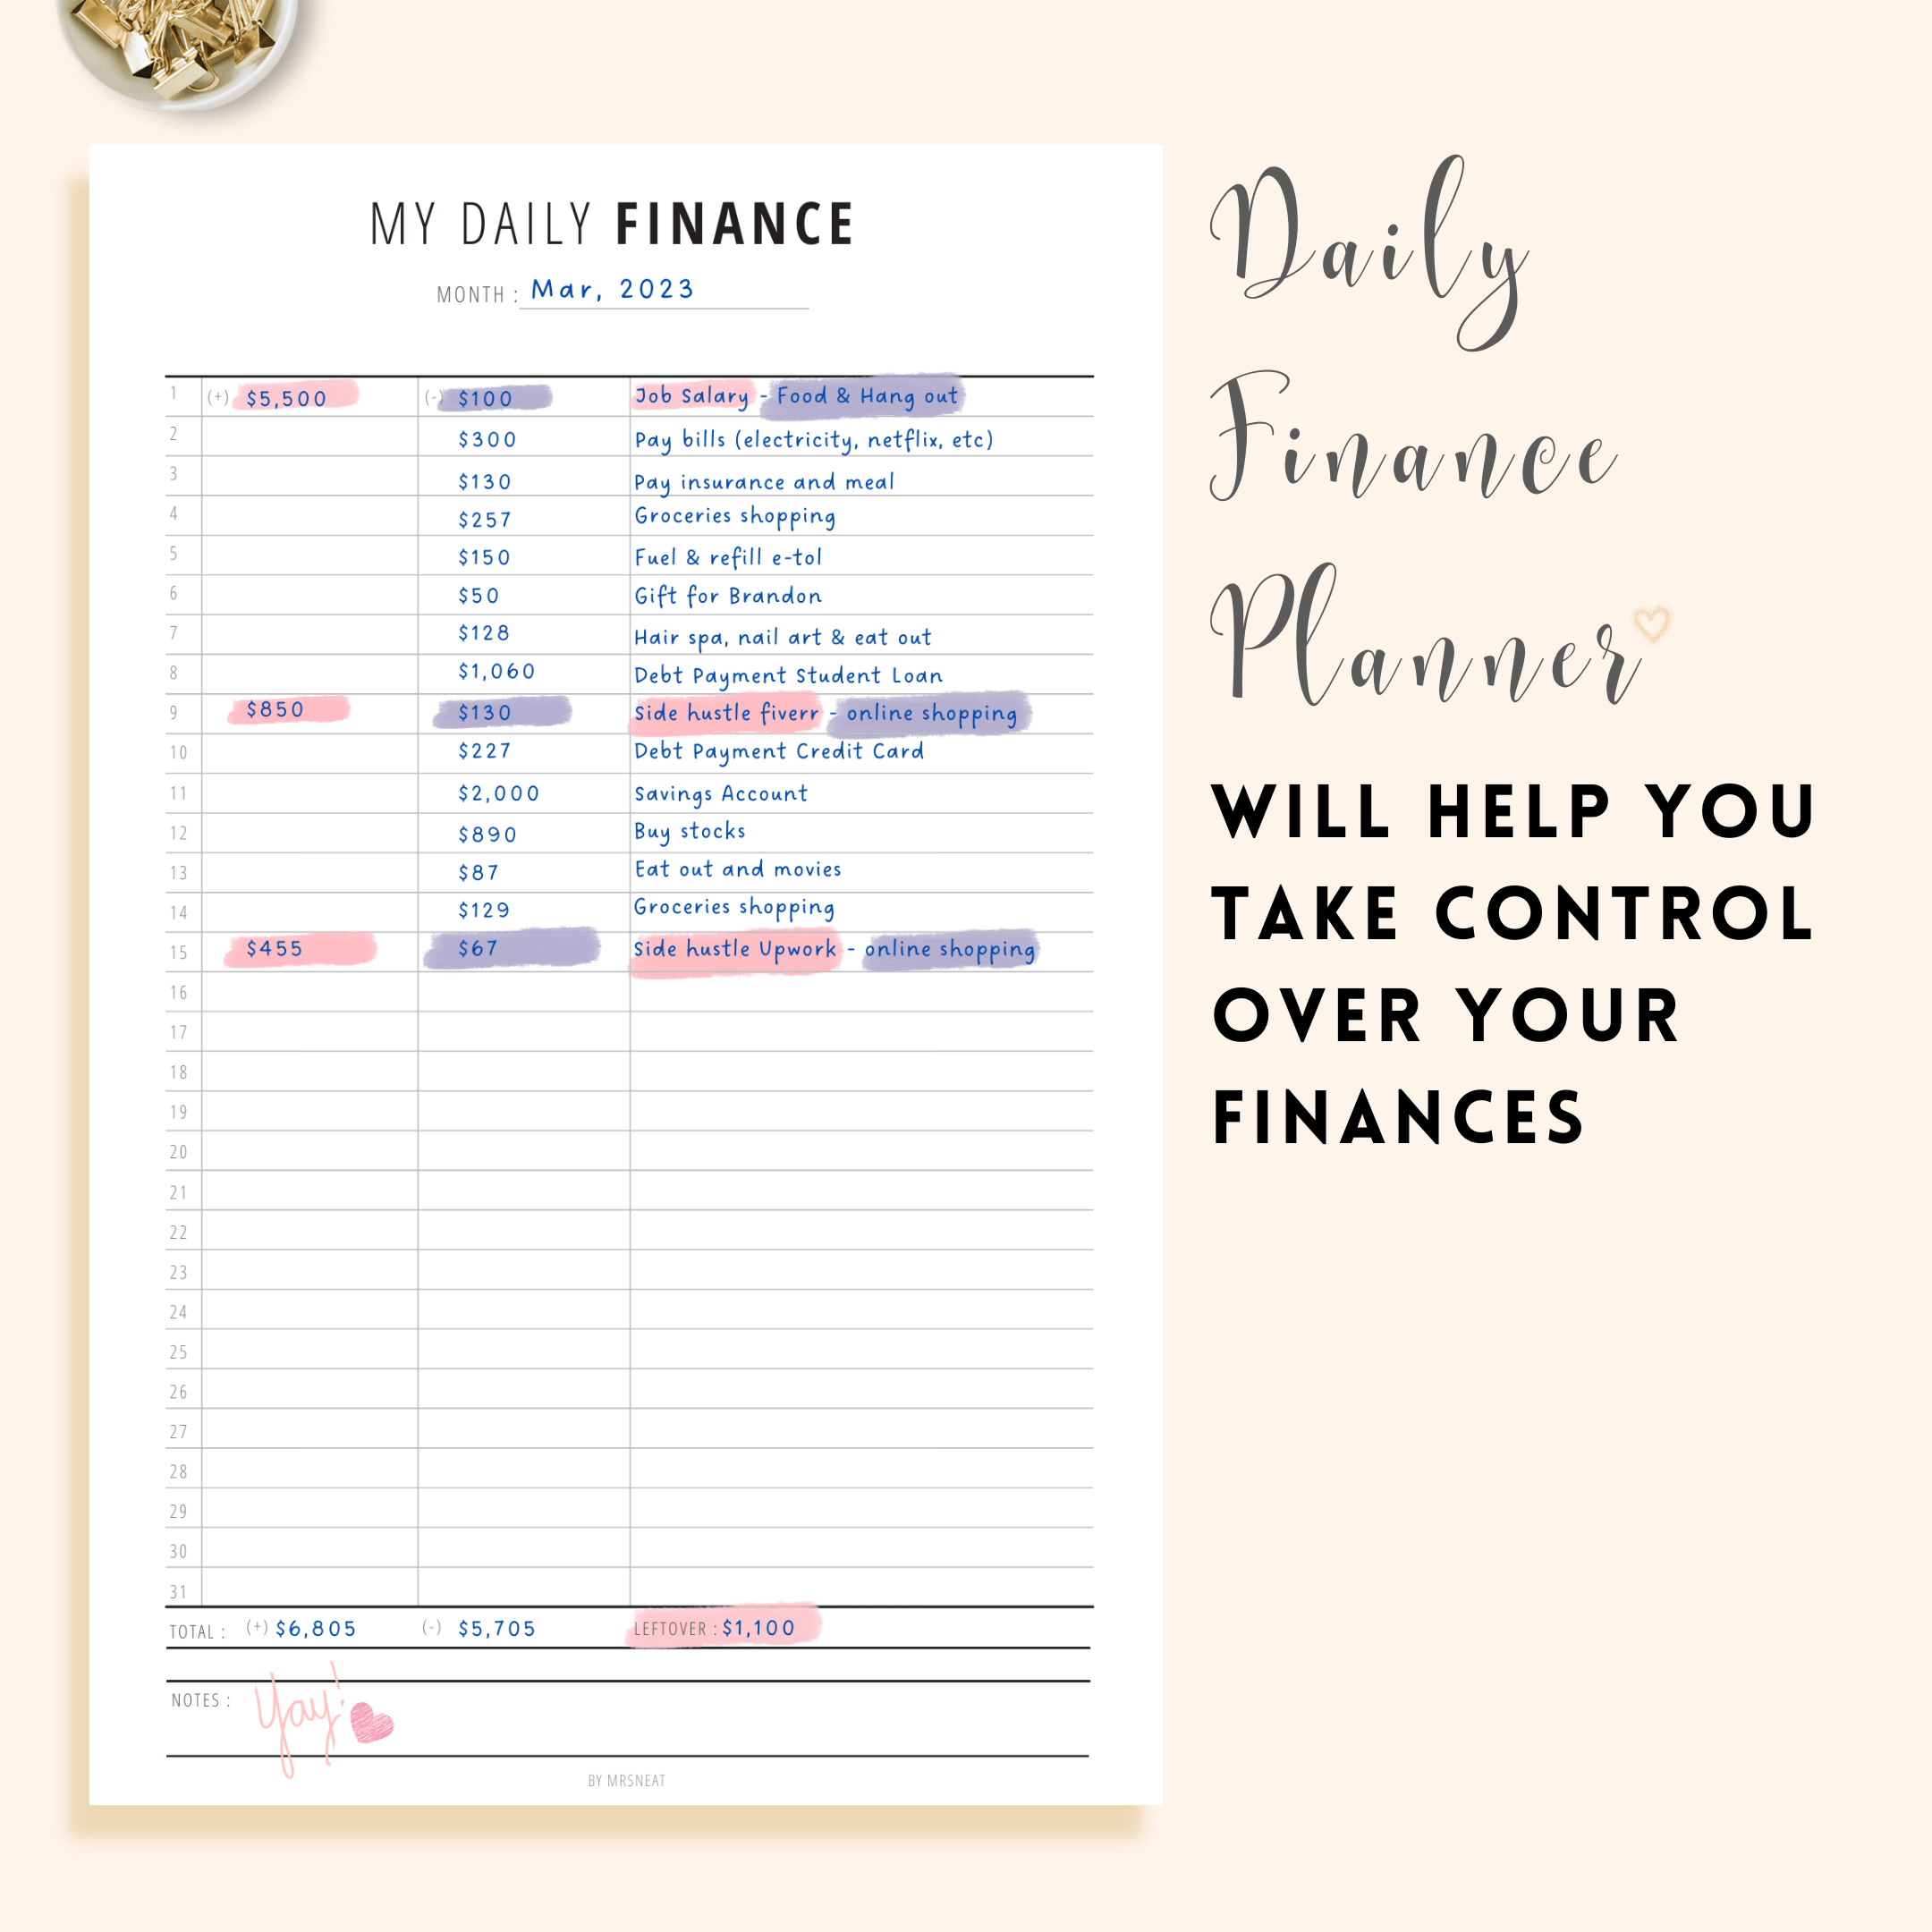
A properly sequenced Daily Finance Tutorial is just a curated progression through personal finance fundamentals, broken into digestible daily chunks over 30 days. The typical structure runs like this: days one through five cover budgeting methods and cash flow tracking, days six through ten move into debt payoff strategy (avalanche vs. snowball, really just math either way), days eleven through fifteen are emergency funds and insurance basics, days sixteen through twenty hit credit mechanics and score optimization, and the final stretch covers investing fundamentals — index funds, asset allocation, tax-advantaged accounts. The trick is sequencing. Most free resources teach investing before debt, which makes no sense if you're carrying 22 percent APR on a credit card. A solid Daily Finance Tutorial flips that. It front-loads the bleeding stops first. I built mine using a simple spreadsheet with a column for topic, resource link, time estimate, and completion status. Google Sheets, nothing fancy. Each row was one day. I spent about twelve minutes per day going through the material and another ten minutes actually doing the exercises — setting up the budget template, calculating avalanche numbers, opening a high-yield savings tab, things like that. The doing part matters more than the watching.
A Real Problem I Hit and How I Fixed It
About day eighteen, I ran into a wall. The topic was tax-advantaged account ordering — Roth IRA vs. Traditional IRA vs. HSA, and when to use which. Every source I found stated a different recommendation depending on your income bracket, filing status, and whether you had access to a workplace 401(k) match. Some said HSA first, then Roth. Others said max the 401(k) match first, then HSA, then Roth. The logic was sound but contradictory across sources, and I couldn't reconcile them without pulling my tax situation apart myself. What I did was write a decision tree in the spreadsheet. If you have an employer match, take it — that's always step one. If your modified adjusted gross income puts you above the Roth IRA contribution phaseout, go Traditional IRA or backdoor Roth instead. If you're healthy and want a triple-tax-advantaged bucket, HSA comes next after the match. If you're in a high bracket now and expect to be lower in retirement, Traditional first. I ran through my own numbers once and the tree told me exactly what to do. Took me about twenty minutes. That saved me from spending another four hours jumping between articles that gave me the same answer in different words. That's the pattern with any Daily Finance Tutorial. The contradiction isn't a flaw in the topic. It's a flaw in generic advice. Pin it down with your actual numbers.
Get the Full Details

Common Pitfalls Beginners Miss
Most people treating this like a Daily Finance Tutorial make two mistakes in the first week. The first is skimming. They read or watch a lesson and move on without writing anything down or running a calculation. Budgeting lessons are useless if you never plug your own income and expenses into the template. Debt avalanche calculations mean nothing until you type in your actual balances and rates. Learning is doing, not observing. The second mistake is skipping the math. People want to hear about philosophy and mindset around money. They don't want to see the compound interest formula or the debt payoff timeline. But the math is where the decisions happen. You need to see that paying an extra hundred dollars a month on a fourteen-thousand dollar student loan at six percent shaves roughly twenty-two months off the payoff and saves about eight hundred dollars in interest. That kind of thing only clicks when you run it yourself. I recommend keeping a separate notes tab in your spreadsheet for these calculations. One row per important decision. Date it. If you come back to it six months later and the numbers don't match what you remember, you'll know something changed — either your situation shifted or you remembered it wrong.
Where This Approach Falls Apart
A self-directed Daily Finance Tutorial only works if you're already somewhat organized. If you can't spend thirty to forty-five minutes a day without getting sidetracked, you'll burn through a week and end up with incomplete notes and abandoned templates. There's no accountability mechanism here. No one is checking whether you actually did the day's work. It also doesn't handle edge cases well. If you're self-employed, carry business debt, deal with rental properties, or have a complicated alimony situation, the standard Daily Finance Tutorial sequence won't touch those topics. You'd need to supplement with targeted research after finishing the core material. I knew someone who finished a thirty-day plan and then realized she had no idea how to handle quarterly estimated taxes because the curriculum assumed W-2 income only. She spent another two weeks Googling that separately. If you fall into that category, consider pairing the tutorial with a single session with a fee-only fiduciary after you complete it. It'll cost you maybe four hundred dollars for an hour and save you from making decisions based on incomplete information. That's cheaper than fixing a mistake later.
How to Actually Download or Access One
There isn't a single official Daily Finance Tutorial product you download. It's a format, not a brand. What you can do is pull together a free version or buy a pre-built one. For the free route, I'd recommend starting with the r/personalfinance wiki — it's organized, it's updated, and it covers every topic a 30-day plan would touch on. Pair that with the Bogleheads wiki for the investing side. Then put both into your spreadsheet with daily targets and you've essentially built your own Daily Finance Tutorial at zero cost. Factor in about three to four weeks of consistent effort. If you want something more structured and don't mind paying, there are a few paid options out there. The most notable is the Personal Finance Guy's course and the ChooseFI curriculum, both of which map closely to a Daily Finance Tutorial structure. They run anywhere from free to about two hundred dollars depending on what tier you pick. I've looked at both and honestly the gap between them and a well-assembled free version is smaller than the price difference suggests.
The Core Insight Nobody Leads With
Personal finance isn't a knowledge problem. It's a behavior problem. You don't need another video on how compound interest works. You need to have actually sat down and calculated how much your specific spending habits cost you over ten years. The Daily Finance Tutorial format works because the daily cadence forces repetition and small action steps. That's the value, not the content itself. Anyone can read about budgeting. Doing it every day for a month is what changes anything.