Understanding the Wealth Formula and Basic Money Principles
Chapter 1 of Dave Ramsey's foundation program focuses on the wealth formula and basic principles of financial management. The core concept is straightforward: spend less than you make. People tend to overcomplicate this, but the math doesn't lie. If you earn $4,000 a month and spend $4,200, no amount of side hustles or investment advice is going to fix that fundamental gap. The chapter answers center around five key principles. First, the cash flow gap exists between your income and expenses. Second, debt is a tool, not a lifestyle. Third, emergencies are inevitable and budgeting for them is non-negotiable. Fourth, your spending habits reflect your priorities more than your intentions ever will. Fifth, small consistent actions compound faster than sporadic grand gestures. I remember working with a couple who had $90,000 in combined income but $104,000 in annual expenses. They were shocked. Their problem wasn't poor-paying jobs. Their problem was three financed vehicles, two credit cards with revolving balances, and a subscription budget that doubled their grocery spend. The wealth formula exposed that in about five minutes of pulling statements.
The worksheet most people use tracks every dollar for thirty days. You log income sources and categorize every single purchase. The goal is visibility, not restriction. You can't fix what you refuse to see. This exercise usually takes people from thinking they know where their money goes to discovering it evaporates across fifteen different categories they never tracked before. Here is something beginners consistently miss. The wealth formula isn't just about saving. It's about building a surplus and then directing that surplus strategically. Saving money without a plan creates a buffer that sits there doing nothing. The formula only works when you pair a positive cash flow with intentional debt elimination and emergency fund building. People who only focus on cutting expenses without addressing the surplus allocation pattern hit a ceiling within six months. The edge case I see most often involves variable income. Freelancers, commission workers, and small business owners struggle with standard budgeting templates because their cash flow swings wildly month to month. The workaround is basing your budget on your lowest earning month rather than your average. When income spikes, you treat that as a windfall and allocate it aggressively toward debt or savings before you adjust your baseline spending upward.
Another counter-intuitive point is that debt elimination order matters less than people think. Dave Ramsey's debt snowflake method prioritizes smallest balances first for psychological momentum. The debt avalanche method prioritizes highest interest rates first for mathematical efficiency. Both work. The real differentiator is consistency, not strategy selection. I've watched people switch methods three times in six months and accomplish nothing because they were optimizing instead of executing. There are legitimate limitations to this approach. If you're carrying high-interest debt above twelve percent, simply budgeting harder won't move the needle fast enough. In those cases, you need to address the debt structure directly through refinancing, balance transfers, or negotiation before expecting the wealth formula to produce meaningful results. Budgeting alone is a maintenance tool, not a rescue tool. The practical application involves setting up a zero-based budget where every dollar has a job before the month begins. Income minus expenses equals zero. Not negative, not positive. Zero. Any unassigned money gets a line item. This prevents the mental accounting error where you assume leftover cash is discretionary spending when it's actually just unallocated funds waiting to disappear.
Get the Full Details
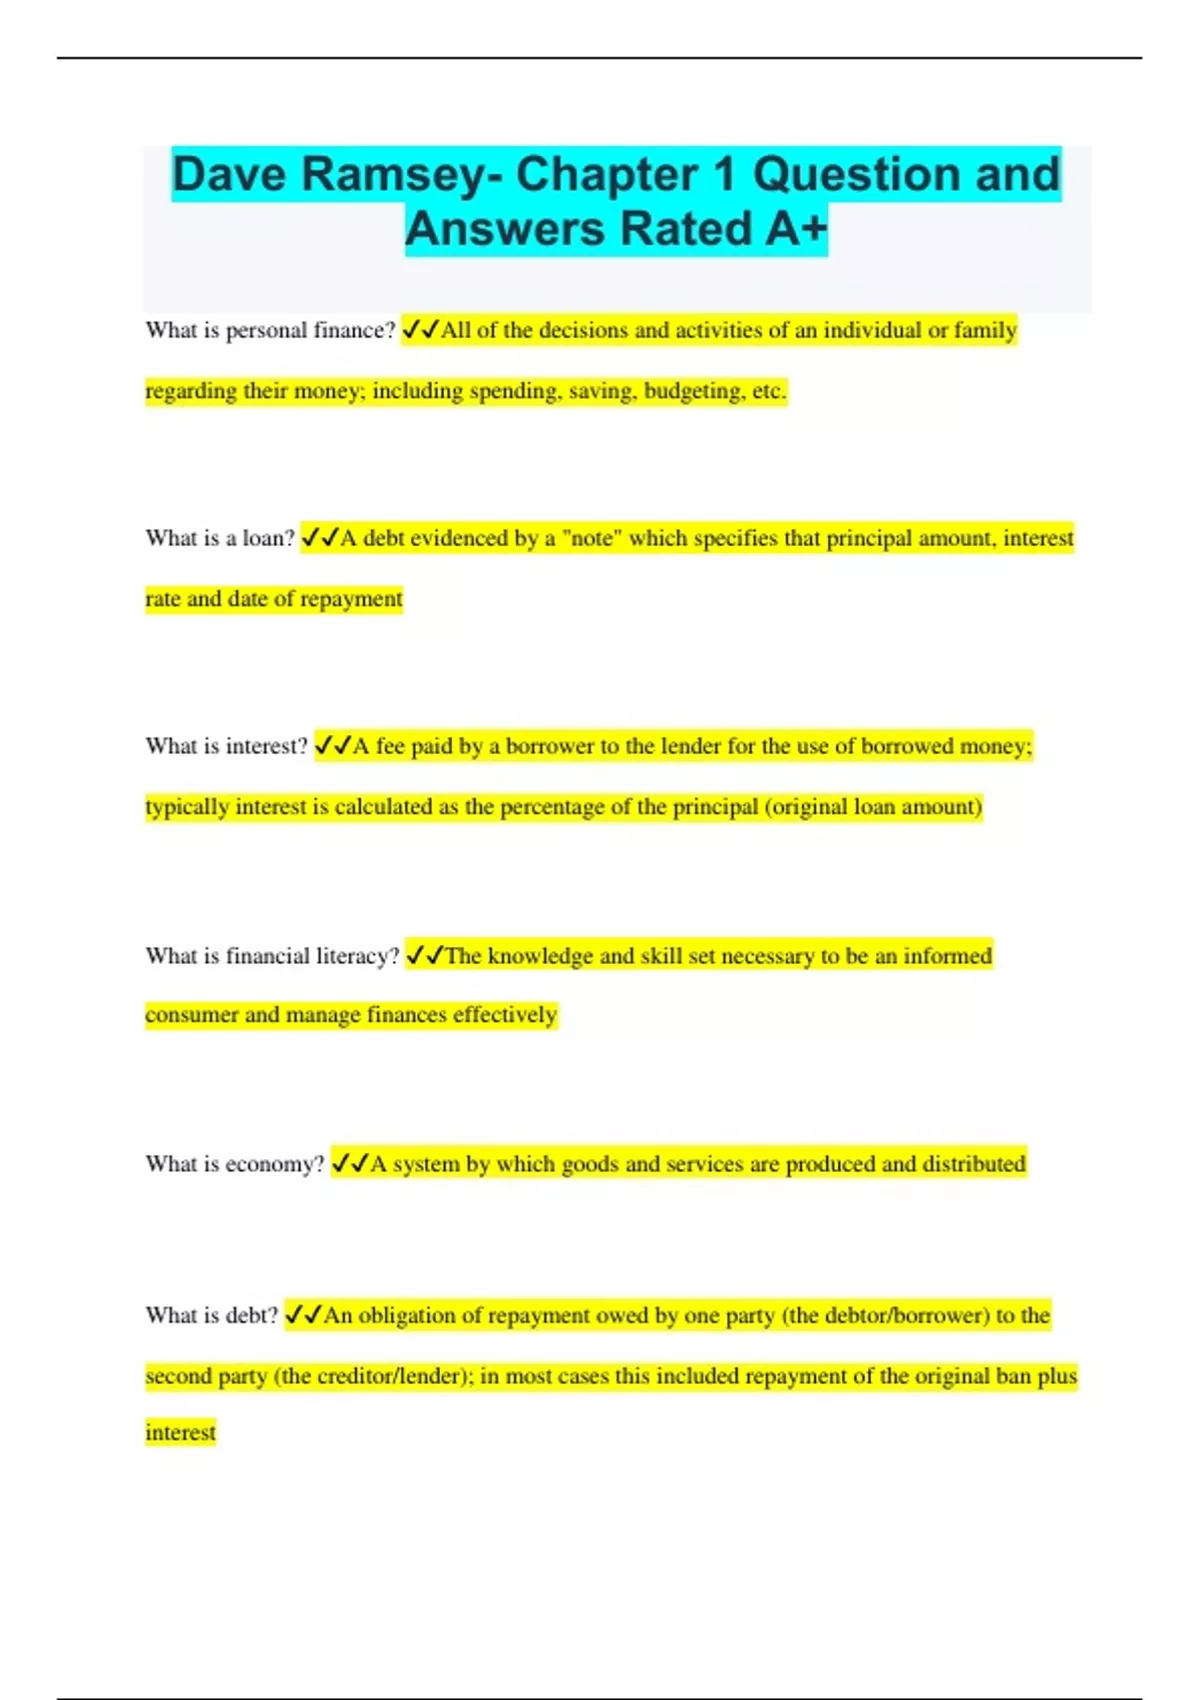
Tracking requires a system you'll actually use. Spreadsheets work for some. Apps work for others. Cash envelopes work for people who spend impulsively. The method doesn't matter as much as the discipline of reviewing it weekly, not monthly. Monthly reviews catch problems too late. Weekly reviews catch them while you still have time to course-correct before rent hits. One thing worth noting is that Chapter 1 doesn't cover investing at all. That comes later in the curriculum. People sometimes get frustrated expecting stock tips or portfolio advice. The intent is deliberate. You need stable cash flow and a funded emergency account before exposure to market risk makes any sense. Skipping this foundation to jump ahead creates fragility that collapses under the first real financial shock. The answers material typically includes a series of reflection questions and worksheets. Work through them honestly. The discomfort you feel when your numbers don't add up is the entire point. That friction is productive. It means you're finally looking at reality instead of assumptions. People who skip the worksheets and just skim the answers miss the diagnostic value embedded in each question.
Download links for the official worksheets are available through the Ramsey Solutions website. Third-party sites host copies, but the version from the source stays current with updates and includes the latest tracking tools. If you're working through the program with a group or coach, they often provide access codes for the paid workbook which contains additional exercises not found in the free materials. The real test of whether Chapter 1 landed is what happens in week three. Most people start strong. Enthusiasm carries them through ten days. Then life interferes. An unexpected charge appears. A bill comes earlier than expected. The budget feels restrictive. This is the exact moment where the principles either hold or fracture. Having a written plan in place before the disruption hits makes a measurable difference in whether you course-correct or abandon the whole effort. People who stick with this for ninety days report something interesting. The budgeting stops feeling like punishment. It becomes descriptive rather than restrictive. You know where money is going before it goes there, which reduces decision fatigue and eliminates the monthly anxiety of checking bank accounts wondering how everything disappeared. That shift from anxiety to awareness is the actual outcome worth chasing.