Getting the Dave Ramsey Debt Worksheet to Actually Work
Most people grab the Dave Ramsey Debt Worksheet expecting it to be some kind of magic debt eliminator, but the truth is it is just a very basic spreadsheet. It does not calculate anything automatically. You enter your own data and follow the debt snowball method manually. I spent about three weeks struggling with mine before realizing most of the confusion came from how people interpret the minimum payment column. The official version lives at daveramsey.com and costs nothing. You can find it under their free tools section. The file is an Excel spreadsheet with tabs for different debt categories, a payoff calendar, and a section where you track progress month by month. That is all it is. Some versions online claim to be updated with new features, but the original has not changed significantly in years because it works.
How the Dave Ramsey Debt Worksheet Structure Actually Works
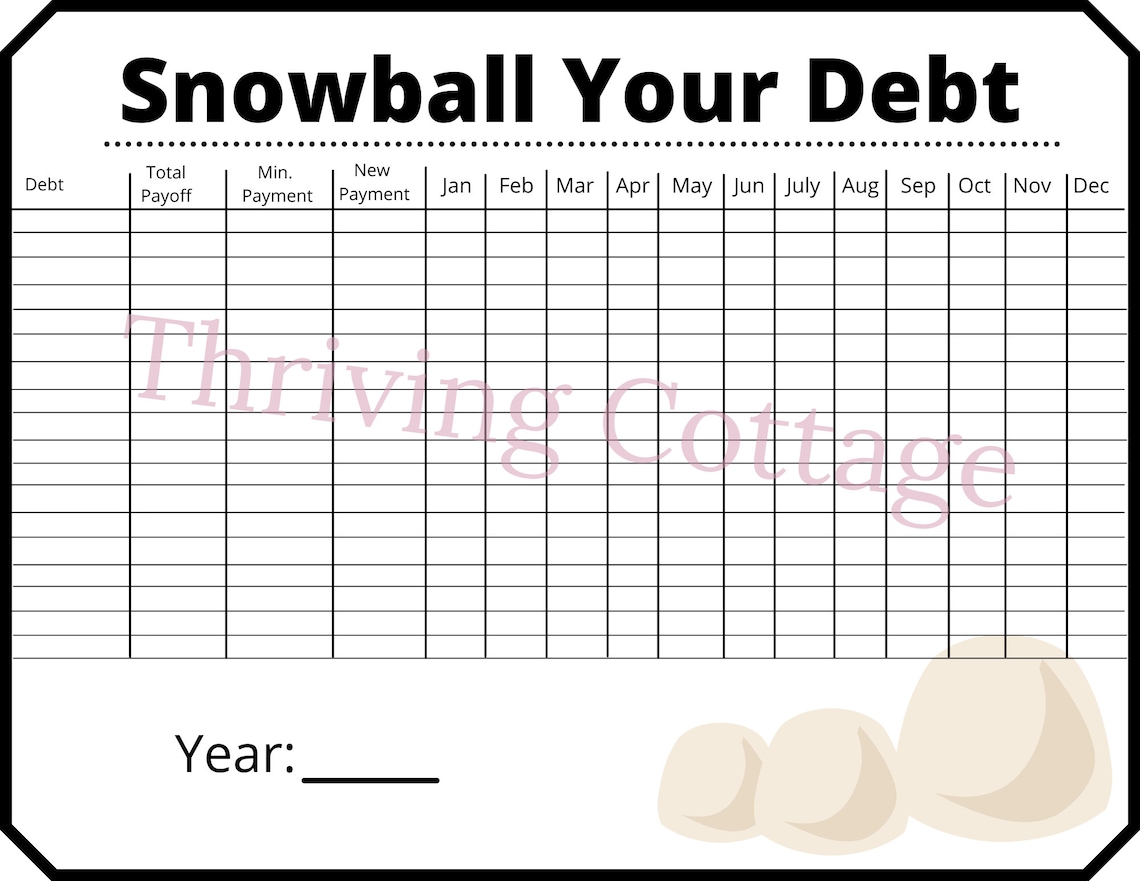
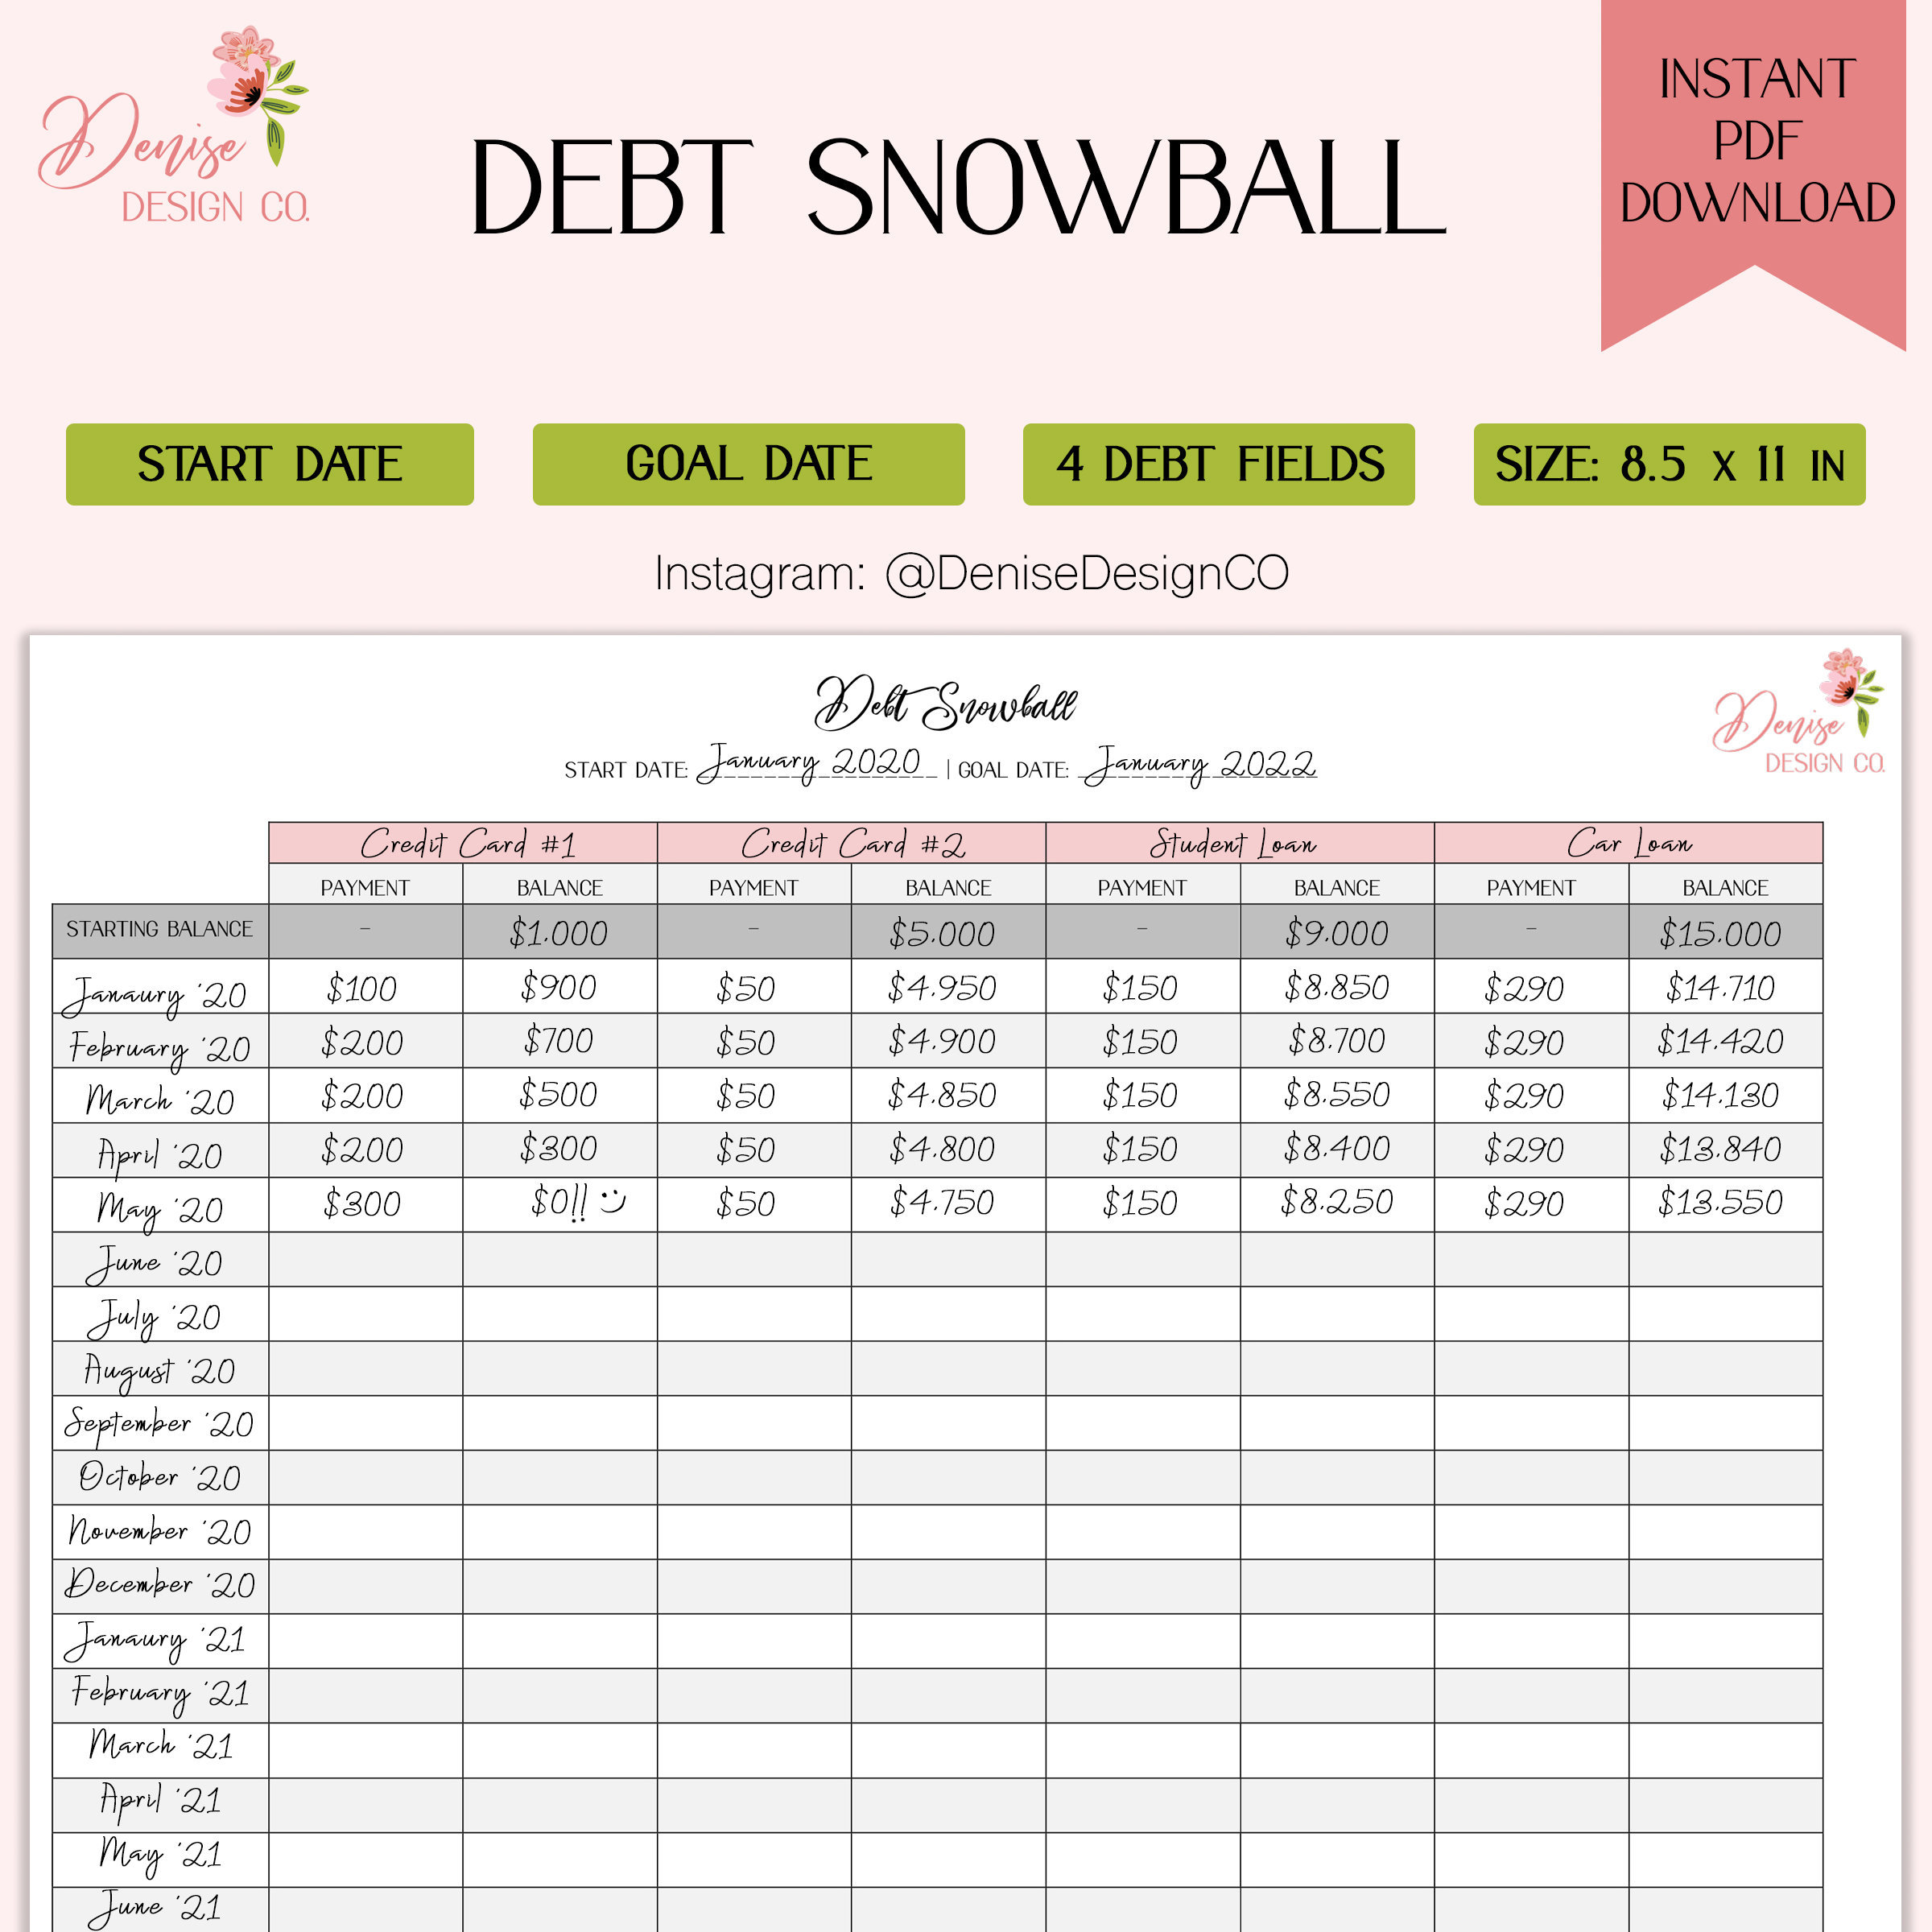
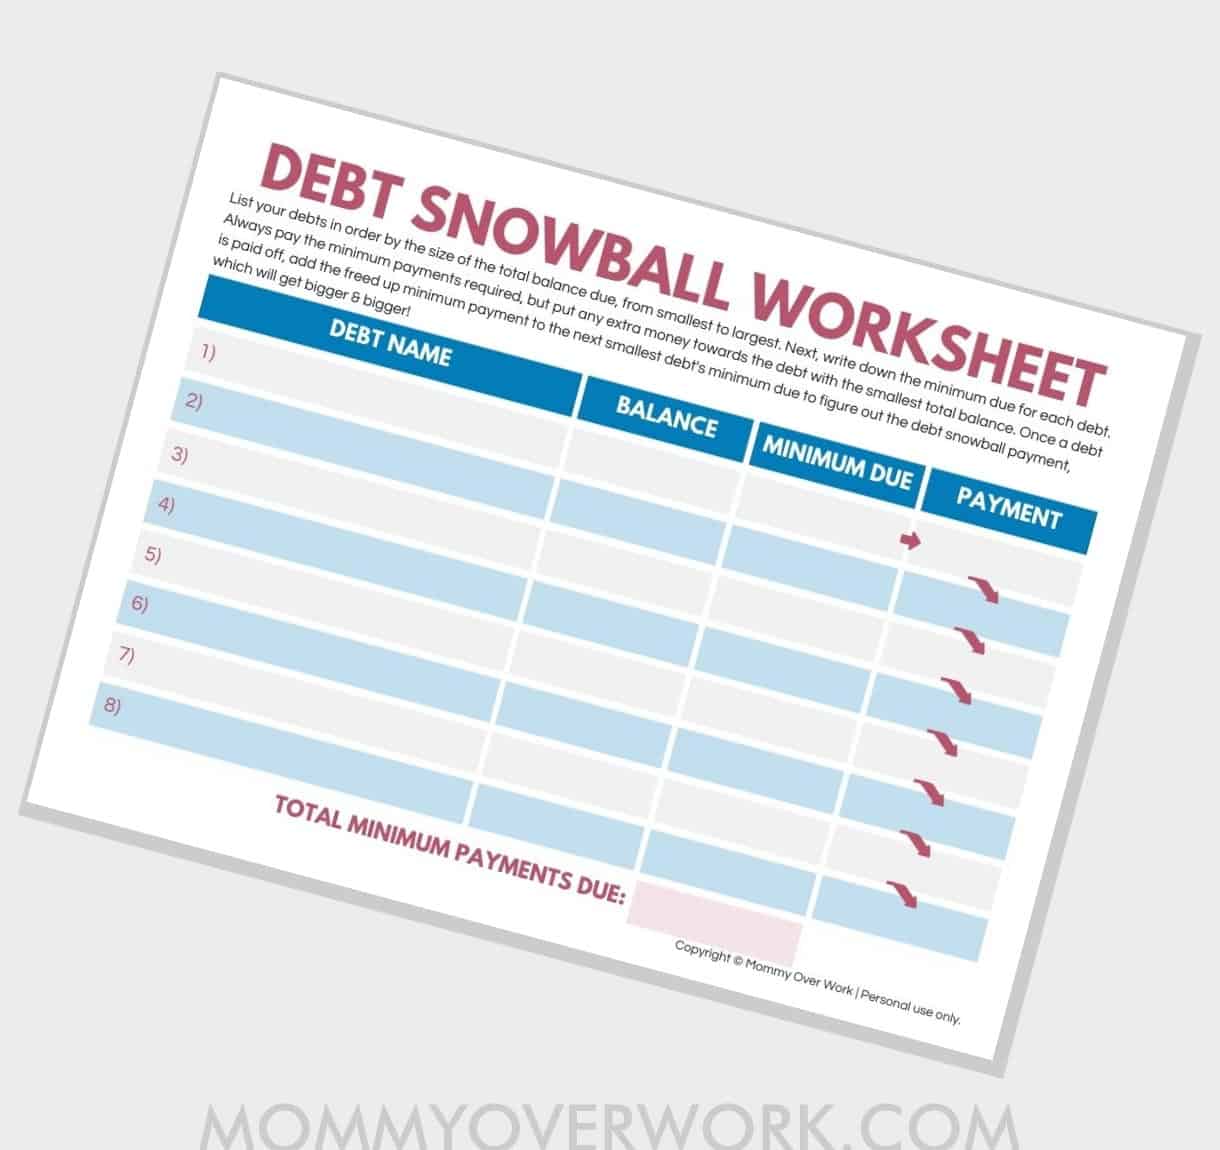
Open the file and you will see columns that look intimidating at first. There is space for account name, total balance, minimum monthly payment, interest rate, and then a column for the extra payment amount you plan to throw at each debt. The secret sauce is the order you list your debts in. Dave Ramsey wants you to list them smallest balance to largest balance, completely ignoring interest rates. This is the part that drives finance majors crazy, but it is the entire point of the snowball method. When I first filled mine out I made the mistake of sorting by interest rate instead of balance. The sheet still calculated the same payoff timeline because it does not have conditional logic that changes based on sort order. You just have to list them correctly yourself. Once you hit debt number one and roll that minimum payment into the next debt, the spreadsheet has a simple formula where you add the freed-up minimum to the next payment amount. It is not automatic. You have to update it each month. Here is something most people miss. The worksheet assumes you are only tracking installment loans and credit cards. It does not have a dedicated section for medical debt or collections that sometimes report differently. I had about four thousand dollars in old medical bills scattered across two different creditors, and the original tab structure did not accommodate that well. What I ended up doing was creating two separate rows labeled as medical debt and treating them like regular credit cards. The math still worked out fine because the snowball method does not care about debt type.
Another edge case that tripped me up involved a variable rate loan. My wife had a home equity line with a rate that changed quarterly. The worksheet asks for a single interest rate, so I averaged the last six months and wrote it down. This is only an estimate, but it is close enough for planning purposes. The actual payoff date shifted by about two months when the rate dropped, which the sheet could not predict.
Get the Full Details

The Realistic Problems with the Dave Ramsey Debt Worksheet
The biggest limitation nobody mentions is that this tool assumes a single income household with predictable cash flow. If you are self-employed, have seasonal income, or your partner works commission, the monthly payment tracking gets messy fast. I know people who tried to force irregular income into the sheet and ended up abandoning it after month three because the numbers looked wrong every time. There is also no integration with banking apps. Everything is manual entry. You log into each account, write down the balance, and type it into the spreadsheet. If you have twelve credit cards and three loans, that is fifteen separate logins to check every month. A realistic time estimate for the full update is forty-five minutes to an hour, depending on how organized your accounts are. Some people get lazy and stop updating, which defeats the whole purpose. The worksheet also does not account for refinancing scenarios well. When I refinanced my car loan to pay off a credit card as part of the snowball, there was no clear place to record that move in the original tabs. I had to create an extra row and manually cross-reference the paid-off account in notes. It works, but it requires you to understand what you are doing rather than following blindly.
Interest calculations in the basic version are simplified. They assume you are only making minimum payments until you start the snowball. If you are making extra payments mid-month or you have a grace period situation where new purchases accrue interest while you pay down old debt, the payoff dates will be optimistic. In practice I found the actual payoff took about six to eight percent longer than the sheet projected, which is worth keeping in mind when celebrating early wins.
What to Do When the Worksheet Fails You
Some people switch to a budgeting app like YNAB or EveryDollar when they hit the limitations I described. Those cost money and require subscriptions, but they auto-sync with accounts and handle variable income better. If you are already comfortable with spreadsheets, you can modify the Dave Ramsey Debt Worksheet itself. I added a second sheet that tracked cash flow separately, then pulled numbers from there into the payoff tab. This took about twenty minutes to set up and saved me from forgetting which debts I had already rolled payments into. Another option is printing the sheet and using it as a visual tracker instead of relying on formulas. Some people find writing the numbers by hand helps them remember where they are in the process. The emotional benefit of crossing off paid accounts sometimes matters more than perfect arithmetic. The original Dave Ramsey version remains free and functional for straightforward situations. If your debts are mostly standard credit cards, auto loans, and a mortgage, it handles the math correctly without any modifications. Just be honest about your balances when you enter them. Including that small forgotten card with a two hundred dollar balance makes a real difference in momentum, even if it seems negligible compared to the larger debts.
One thing I wish someone had told me upfront is that the worksheet does not include a bankruptcy or debt settlement fallback option. If your situation changes and you cannot maintain payments, there is no guidance in the file. You would need to seek that advice elsewhere. The tool is strictly for people committed to paying debts off, which is fine if that is what you want, but it leaves you hanging if your circumstances shift. Download the file from the official Dave Ramsey site rather than third-party mirrors. Some modified versions I saw online had broken formulas or added hidden columns that confused the calculation. The original is stable and has been tested by millions of users over many years. Keeping it unaltered means the snowball math works as intended when you follow the instructions exactly. The real value of this worksheet is not in its sophistication. It is in forcing you to confront every single debt you owe, write down the exact balances, and commit to an order of attack. That mental step matters more than the spreadsheet itself. People who skip filling it out properly and just eyeball their debts usually quit within sixty days. The ones who take the time to enter everything accurately have a fighting chance of finishing the journey.