How the Envelope System Actually Works
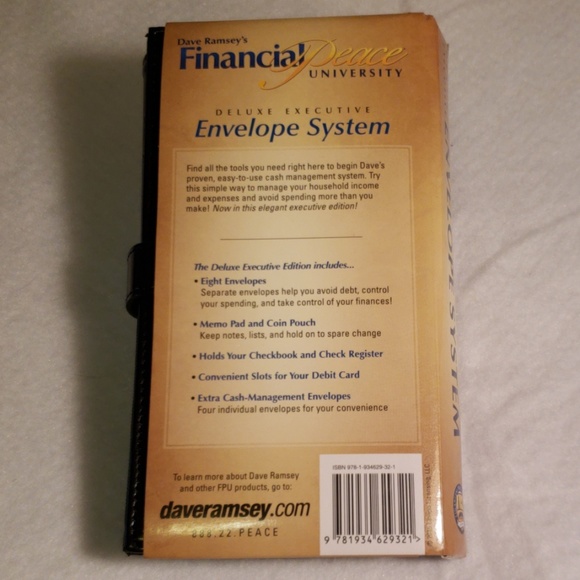
The basic premise is that you allocate cash for each spending category into physical envelopes labeled accordingly. You withdraw the amount at the start of the month, use only that cash for expenses in that category, and when the envelope is empty, you stop spending there until next month. This eliminates the invisible problem of card payments where you never feel the money leave your account. The deluxe version just uses pre-printed, color-coded envelope kits rather than making your own labels. It typically includes envelopes for categories like groceries, utilities, transportation, entertainment, and so on. The system itself is identical whether you use store-bought envelopes or manila folders with a marker. The commercial product is mostly about convenience and not looking like a person who is living out of their car trunk. Here is how I set it up last year. I opened my envelope kit, assigned each category, then went to the ATM. I withdrew about two thousand dollars in singles and twenties, sorted it by envelope, and dropped the cash inside. The initial cash-out takes about forty-five minutes if you have all your accounts organized. After that, every payday is just a matter of topping off the envelopes that ran low.
The counter-intuitive part most people miss is the timing of the withdrawal. You should fund your envelopes on the day you get paid, not the first of the month, because that is when the money is actually in your account. If you are weekly or bi-weekly paid, which is roughly half of working people, you need multiple rounds of funding. I keep a secondary stash of cash at home for the mid-cycle top-offs so I am not making unnecessary ATM trips. Another thing nobody tells you about this approach is that it only controls variable spending. Fixed expenses like rent, mortgage, car payment, and insurance are already on autopay or due the same amount each month. Putting those in envelopes is redundant and adds unnecessary friction. I learned this the hard way when I started putting my mortgage payment in an envelope, which required me to write a check every month for a transaction that could be a single electronic draft. I also encountered a specific edge case that caught me off guard. My local grocery store switched to accepting only contactless payments, and I had about eighty dollars left in my Produce envelope with no way to spend it. The workaround was straightforward. I stopped shopping at that particular store and went to a different market nearby where cash was still accepted. It added a fifteen-minute drive each trip, but it kept the system from breaking. If you live in an area where cash acceptance has dropped significantly, this is a real vulnerability.
The real bottleneck with cash envelopes is receipts and record-keeping. When you pay with a card, the transaction shows up automatically. With cash, you are carrying physical paper that proves you paid, and if you lose the receipt you have no way to verify the charge later. I started photographing every cash receipt with my phone immediately after the purchase. That takes about three seconds per transaction and saves a significant headache during tax season. There are scenarios where this method simply does not work well. If you regularly shop online, the envelope system provides no practical control because you cannot feed envelopes into a website checkout. I handle this by allocating a separate online shopping envelope for things like Amazon purchases, but honestly it is a weak proxy for actual spending restraint. For heavy online shoppers, a debit card with daily spending limits serves the same psychological function without the logistics of handling cash. Another limitation is that this system assumes you have access to sufficient physical cash and a safe place to store it. If your apartment is small, keeping several hundred dollars in cash on hand feels unsafe to a lot of people. I keep mine in a small fireproof lockbox inside a closet, which adds about twenty seconds to the retrieval process but removes the anxiety factor. If you are worried about theft or damage, a safes deposit box at a bank is the backup option, though that requires an extra trip on funding days.
Get the Full Details
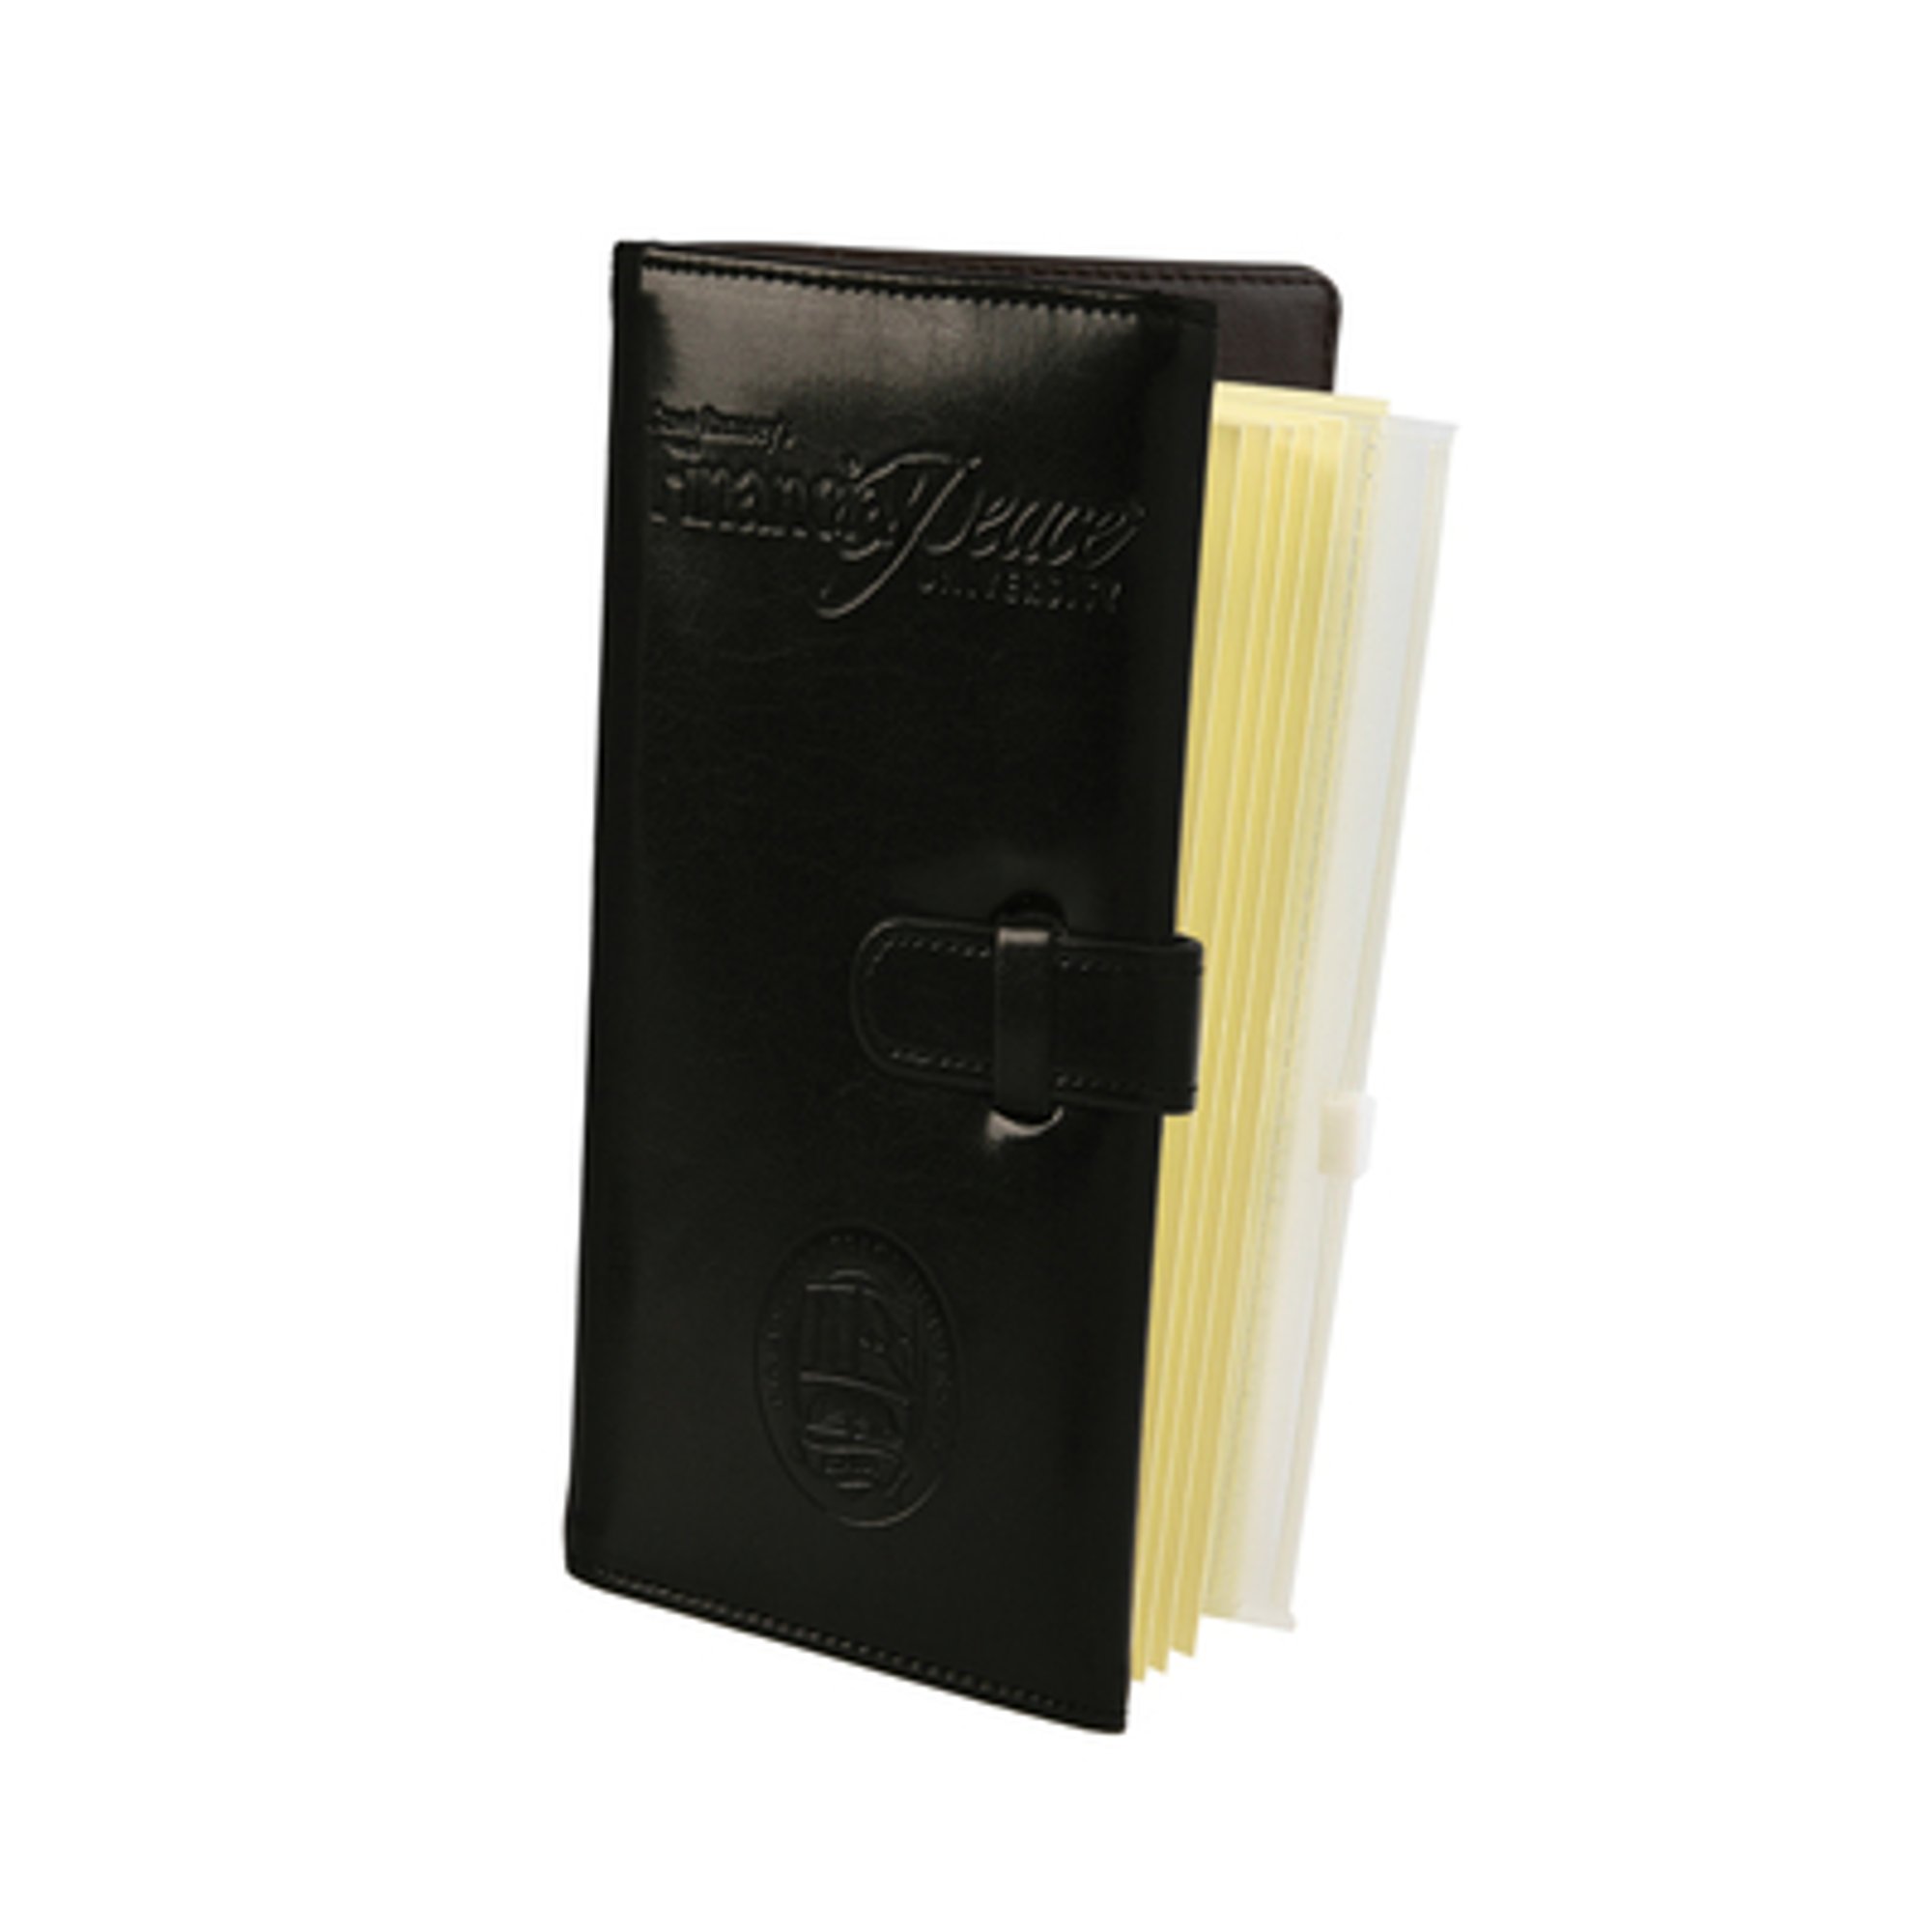
The math behind the system is straightforward enough that you do not need software for it. You add your net income, subtract fixed obligations and savings goals, and the remainder is what you divide among spending envelopes. If the numbers do not work, the envelope system will expose that immediately because you will run out of cash mid-month. That visibility is the entire point of the method, even when the feedback is unpleasant. If you are someone who struggles with impulse spending on credit cards or needs structure to follow a budget, the Dave Ramsey Deluxe Envelope System is worth trying for at least one full cycle. If you already track your spending with an app and understand where your money goes, the overhead of handling cash may not be worth the marginal behavioral benefit. The system works because it makes spending painful and visible, not because it is clever accounting.