Understanding the DCF Valuation Method
A DCF Business Valuation Calculator is a tool built around discounting future cash flows to estimate what a business is actually worth today. It is not a black box that produces a single number you can blindly accept. The output only matters as much as the inputs you put into it, and those inputs are where most people get it wrong. At its core, the calculator takes projected free cash flows for a business over a forecast period, applies a discount rate to bring those future dollars back to present value, and adds a terminal value to account for everything beyond the explicit forecast window. That terminal value alone often makes up 60 to 75 percent of the total enterprise value, which means getting the perpetuity growth rate or exit multiple right is where the whole exercise lives or dies. I have spent enough time running these models that I know exactly where they break. One specific example comes to mind from a few years back when I was valuing a small regional logistics company. The forecasted cash flows looked reasonable on paper, but the business had a heavy concentration risk. One major client accounted for about 42 percent of revenue, and the contract was up for renewal in 18 months. The calculator produced a clean valuation around $3.2 million, but that number meant nothing because it treated the revenue stream as stable when it was not. My workaround was to build a scenario toggle into the model. I ran three separate DCF passes, one with that client renewed at current terms, one with the client lost entirely, and one with a 30 percent reduction in contract value. The range between the optimistic and worst-case scenarios was nearly $1.4 million. Anyone looking at just the base case would have been seriously misled.
Setting Up the Model Correctly
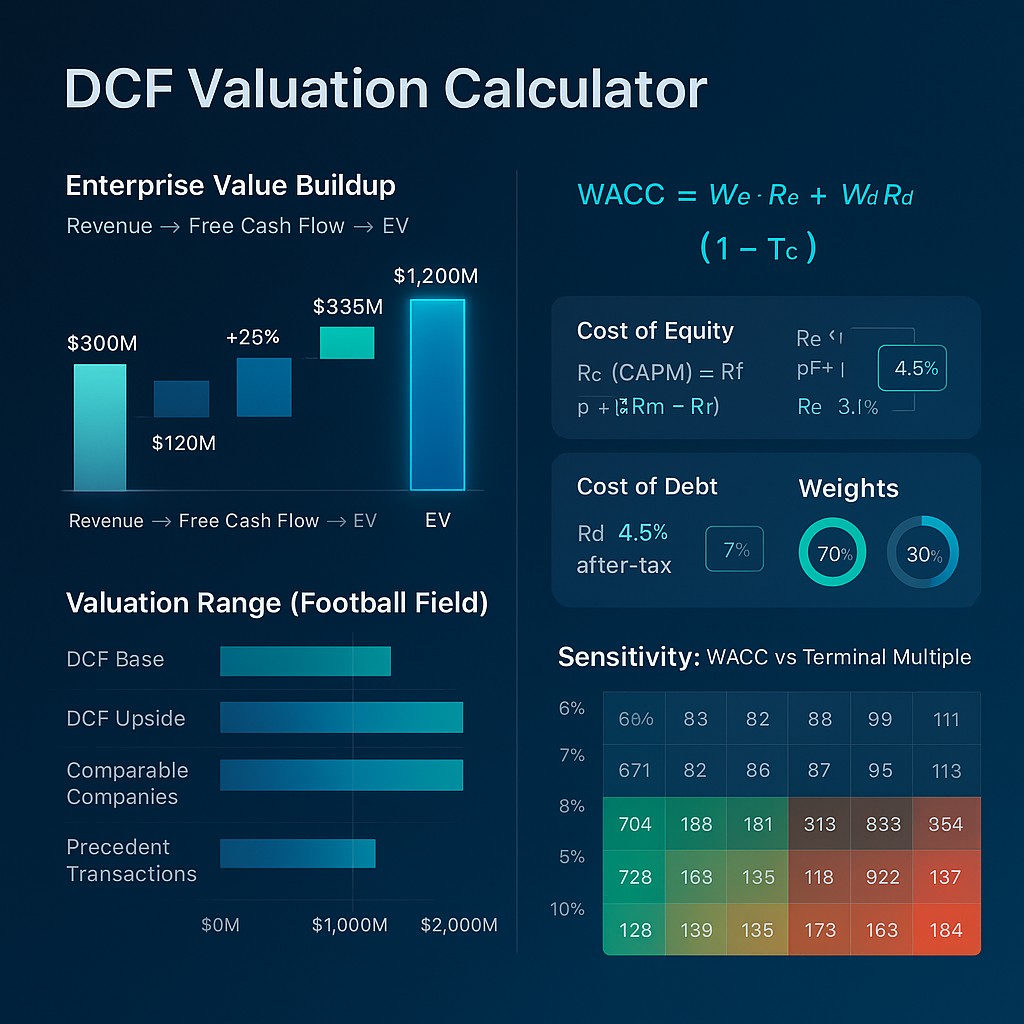
The first decision that determines whether your model is useful is picking the right cash flow definition. Free cash flow to the firm or free cash flow to equity. If you are using FCFE, the discount rate must be the cost of equity. If you use FCFF, you need the weighted average cost of capital. Mixing those two up is the most common error I see in models built by people who have never run a full valuation from scratch. Forecasting the cash flows themselves requires actual discipline. Revenue growth should be tied to something defensible, not just an arbitrary percentage pulled from a hat. Operating margins need to reflect realistic efficiency curves. Working capital assumptions should track the actual operating cycle of the business. Capex should be split into maintenance capital expenditures required just to stay in business and growth capex that expands capacity. A lot of calculators merge these two together and that merge creates a distorted picture of true free cash flow generation. The discount rate is another area where shortcuts produce bad results. The WACC is not just a default number you grab from a spreadsheet template. You need a risk-free rate that matches the currency and geography of the cash flows, a beta that reflects the actual capital structure of the business, a market risk premium appropriate for the current environment, and adjustments for company-specific risk if the business is small or lacks diversification. In practice, using a generic WACC of 10 percent for every company will give you numbers that feel concrete but are essentially guesses.
Terminal Value Calculation Choices
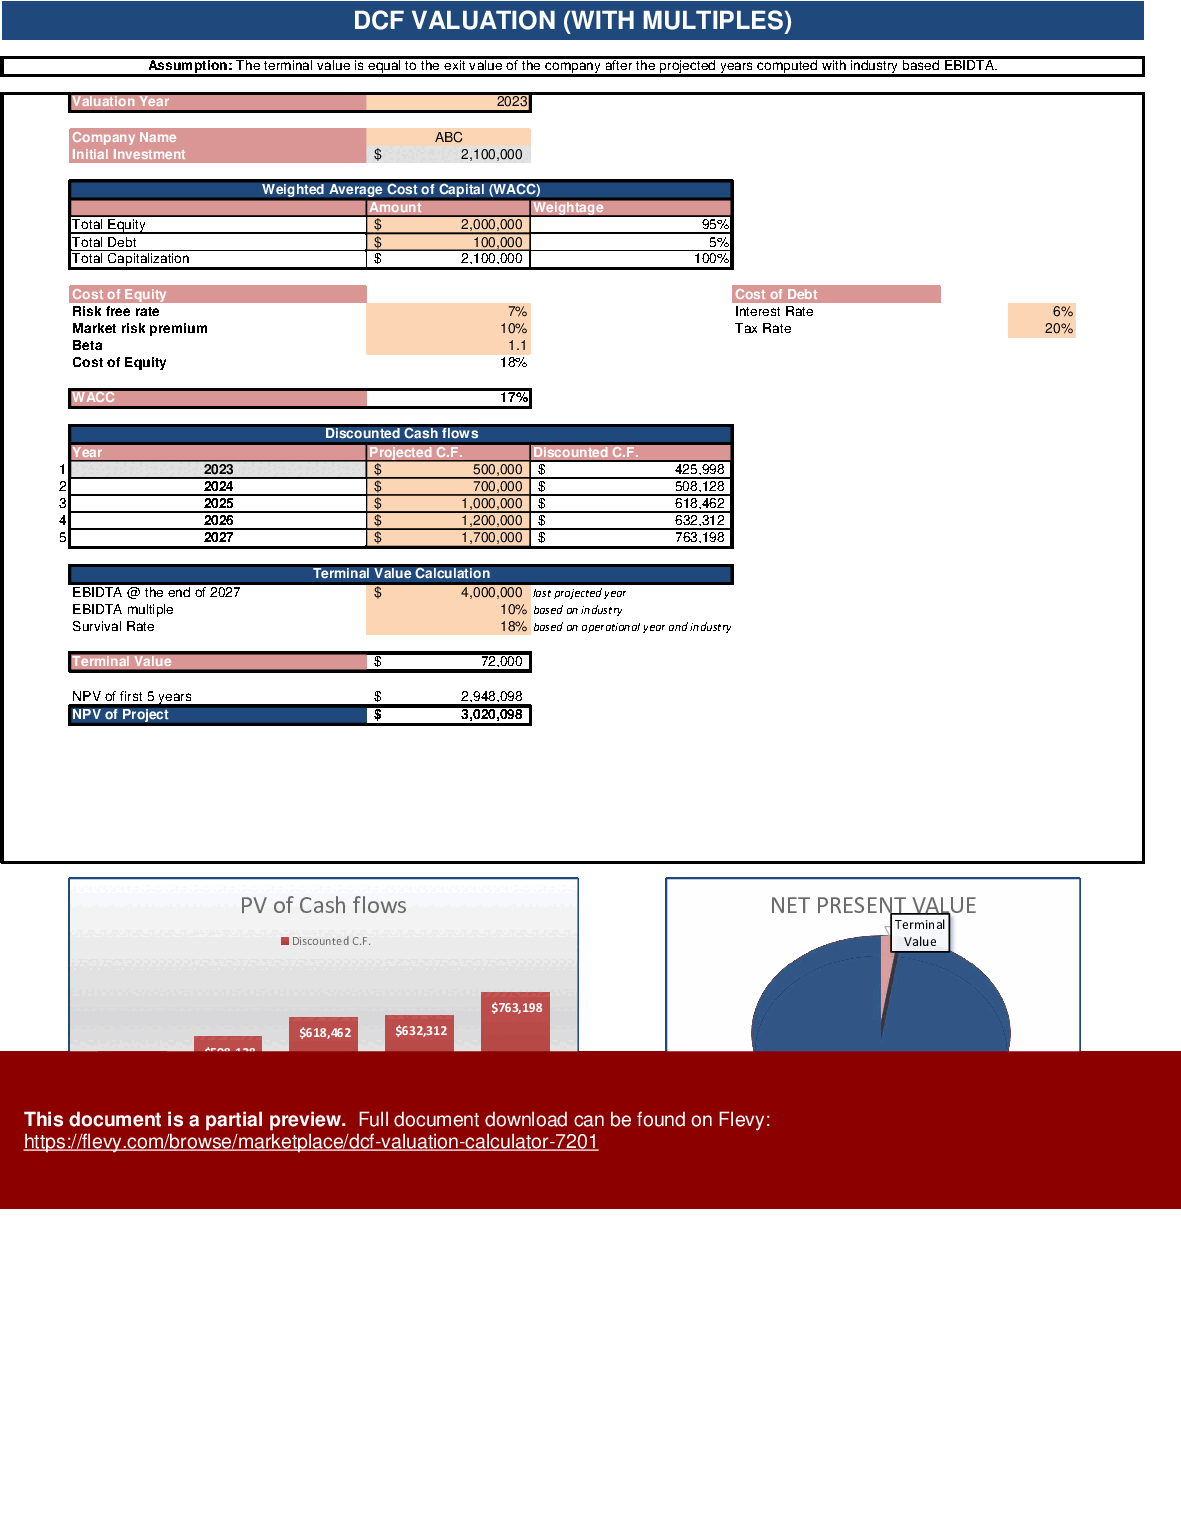
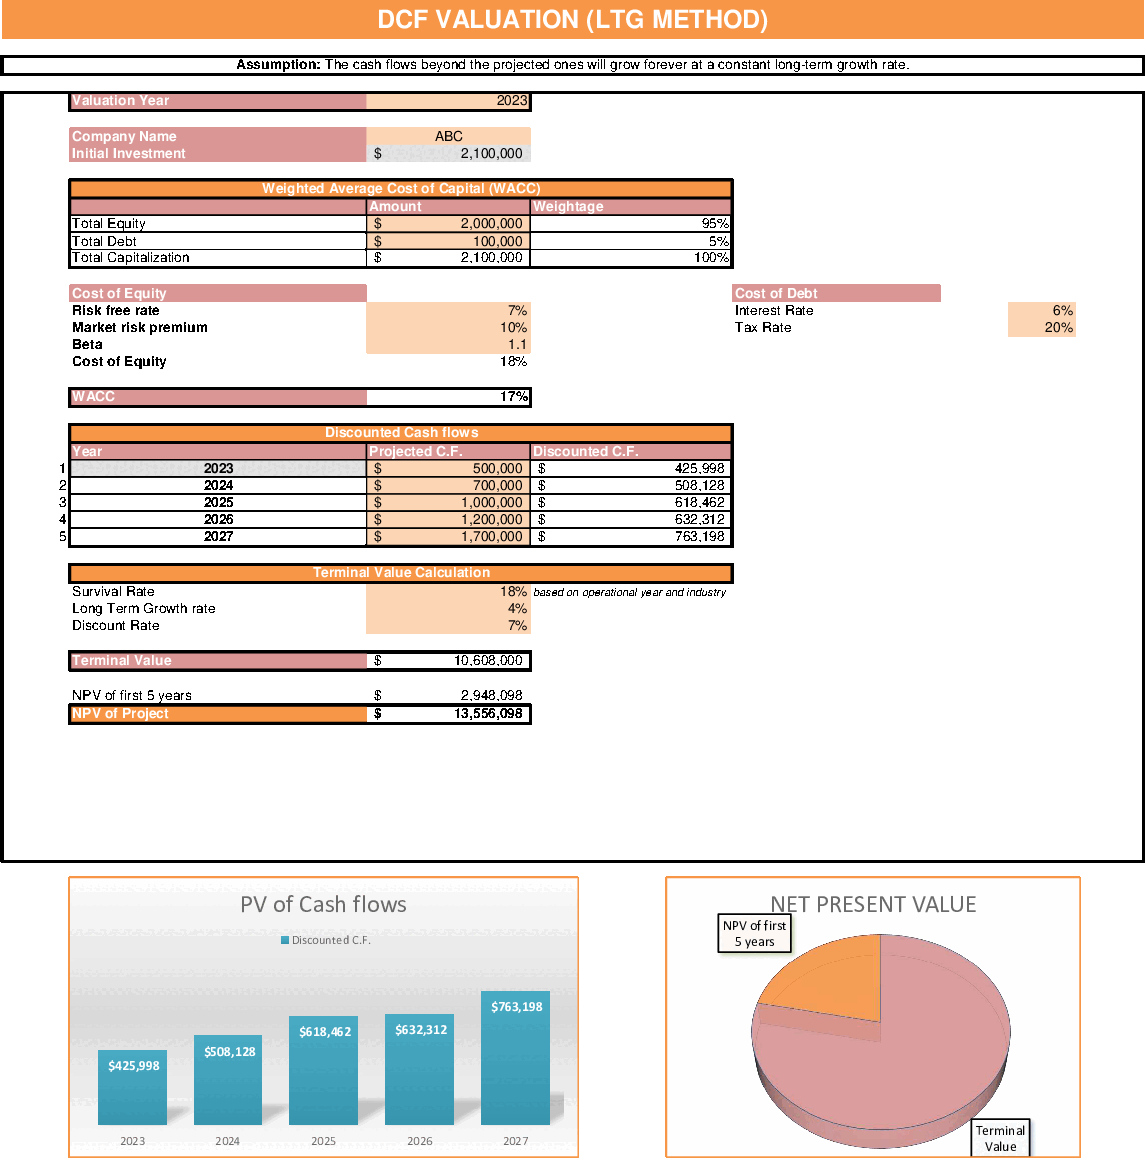
There are two accepted ways to calculate terminal value, and the difference matters more than most people realize. The Gordon Growth Method applies a constant perpetual growth rate, usually between 2 and 3 percent, to the final year cash flow and divides by the discount rate minus that growth rate. The Exit Multiple Method applies an industry-standard EBITDA or earnings multiple to the final year financial metric. The Gordon Growth Method tends to produce more conservative and stable valuations, while the Exit Multiple Method can swing wildly depending on which multiple you pick and whether current market conditions are inflated or compressed. I learned this the hard way during a tech services company valuation. The base case used a 7x exit multiple on EBITDA, which pushed the terminal value to roughly $8 million out of a $11 million total enterprise value. When I recalculated using a 2.5 percent perpetuity growth rate, the terminal value dropped to about $5.3 million. The total enterprise value moved from $11 million down to roughly $9.1 million. That is an almost 17 percent difference coming entirely from the terminal value method choice. Both methods are technically valid, but you need to be honest about which one fits the industry and the economic cycle better.
Get the Full Details
Common Pitfalls and Where Models Fail
A DCF Business Valuation Calculator is only as reliable as the assumptions behind it. Here are the failure modes I see repeatedly. Over-forecasting revenue growth is probably the single biggest problem. People project 15 or 20 percent growth for five years straight on businesses that have historically grown at 4 or 5 percent. Cash flow valuation models reward consistency, not optimism. A more realistic approach projects growth that declines each year toward a long-term equilibrium rate that matches the broader economy. Ignoring working capital needs is another frequent error. A growing business consumes cash in receivables and inventory. If your model assumes revenue can grow indefinitely without requiring additional working capital investment, you are inflating free cash flow by an amount that can easily reach six figures for mid-sized companies. Always include a working capital line item that scales with revenue growth.
Using a single-stage model for complex businesses is also a mistake. Companies with heavy capex requirements, cyclical revenue, or significant debt paydown schedules benefit from a two-stage or multi-stage DCF where you model the distinct phases of the business separately. A startup-phase biotech company should not be valued with the same structure as a mature manufacturing firm with predictable cash flows. Not sensitivity testing is perhaps the most damaging omission. Running a base case once and presenting a single valuation number gives false confidence. The professional standard is to build a data table or tornado diagram that shows how the valuation changes across a range of discount rates and growth rates. A model that takes 10 minutes to set up this sensitivity analysis is infinitely more credible than a model that produces one rigid number.
When a DCF Is Not the Right Tool
There are businesses where a DCF Business Valuation Calculator produces numbers that are technically correct but practically useless. Early-stage companies with negative or highly variable cash flows are one example. The valuation becomes extremely sensitive to terminal value assumptions, which means the result tells you more about your opinion on perpetuity growth than it does about the actual business. In those cases, a comparable company analysis or venture capital method is more appropriate. Companies in secular decline are another example. If the revenue base is shrinking predictably, the DCF may still produce a number, but that number depends heavily on assumptions about how fast the decline accelerates and whether there are any hidden assets on the balance sheet. A liquidation or asset-based valuation often provides a clearer floor in these situations. Capital-intensive industries with long cycles like utilities or mining also present challenges. The huge upfront investments and regulated or commodity-driven revenue streams make free cash flow projections extremely volatile. These businesses are better valued using a build-up approach to the discount rate combined with scenario analysis rather than a standard DCF model.
Practical Steps to Build Your Own
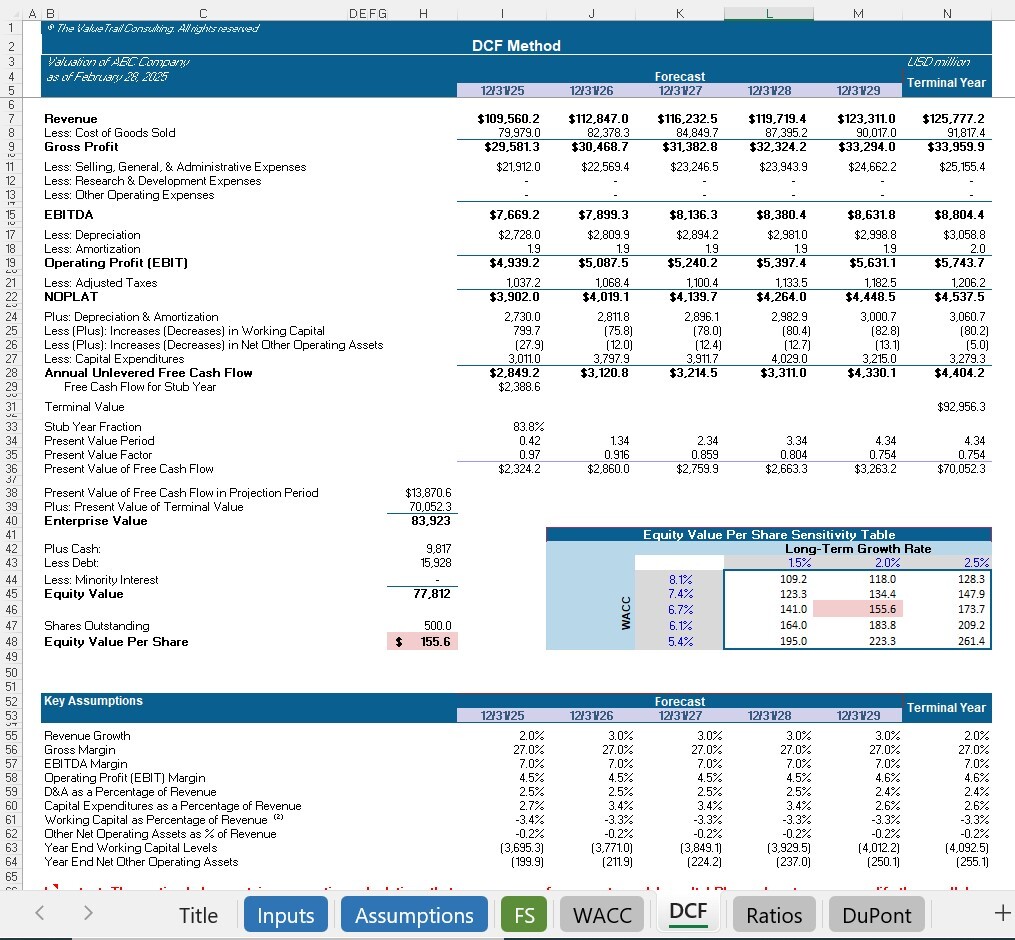
Start by pulling at least three years of historical financial statements. Focus on calculating historical free cash flow correctly. Use FCFF = EBIT × (1 - tax rate) + depreciation and amortization - capex - change in working capital. Do not skip any of these components. Next, build the revenue projection. Use a bottom-up approach where possible, breaking down revenue by product line, customer segment, or geographic market. Assign a growth rate to each component and justify it with market data or historical trends. A top-down growth rate applied uniformly to all revenue streams is a shortcut that introduces unnecessary error. Then project operating expenses. Separate fixed costs from variable costs. Variable costs should scale with revenue. Fixed costs should be reviewed for annual increases based on inflation or known contract escalations. The margin profile of the business should move gradually toward the industry median over the forecast period, not stay artificially high throughout.
Calculate the discount rate. Start with the risk-free rate, typically the yield on a government bond matching the forecast currency and duration. Add a equity risk premium scaled by beta. If the company has debt, incorporate the after-tax cost of debt and weight it according to the target capital structure. The resulting WACC should fall within a reasonable range for the industry, typically between 8 and 14 percent for most private businesses, though this varies widely by sector. Discount each year's projected free cash flow back to the present using the WACC. Sum these discounted cash flows. Then calculate the terminal value using either the Gordon Growth Method or the Exit Multiple Method and discount it back to present value as well. Add the present value of the discounted cash flows to the present value of the terminal value to arrive at enterprise value. Subtract net debt and add any excess cash or non-operating assets to get equity value. Finally, run the sensitivity analysis. Create a table showing enterprise value across discount rates from 6 percent to 16 percent and terminal growth rates from 1 percent to 4 percent. The resulting range is the only part of the model that provides actual decision support. Everything else is just a point estimate dressed up in precision.
A properly built DCF Business Valuation Calculator gives you a structured way to think about value, but it does not replace judgment. The model forces you to make your assumptions explicit, which is its real advantage. When someone asks what the business is worth, you can trace the answer back to specific inputs instead of offering a vague number pulled from thin air. That traceability is what separates a professional valuation from a guess with a calculator attached.