Why most DCF valuations are garbage
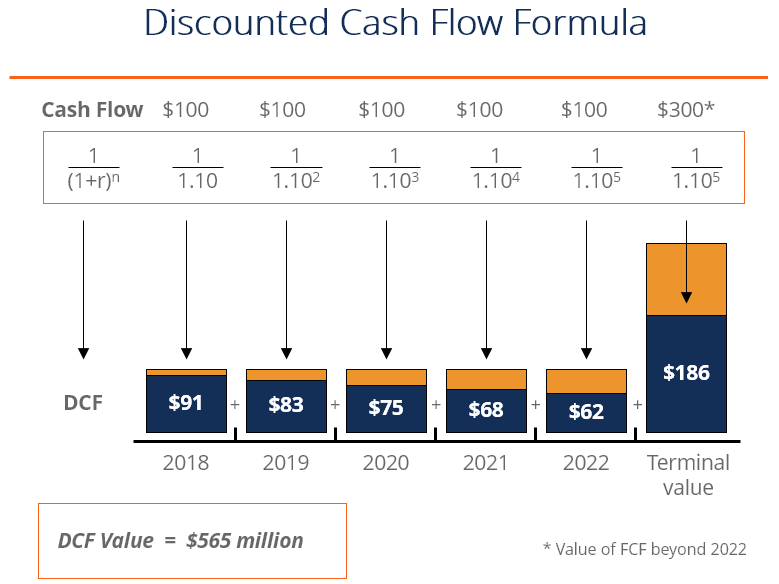
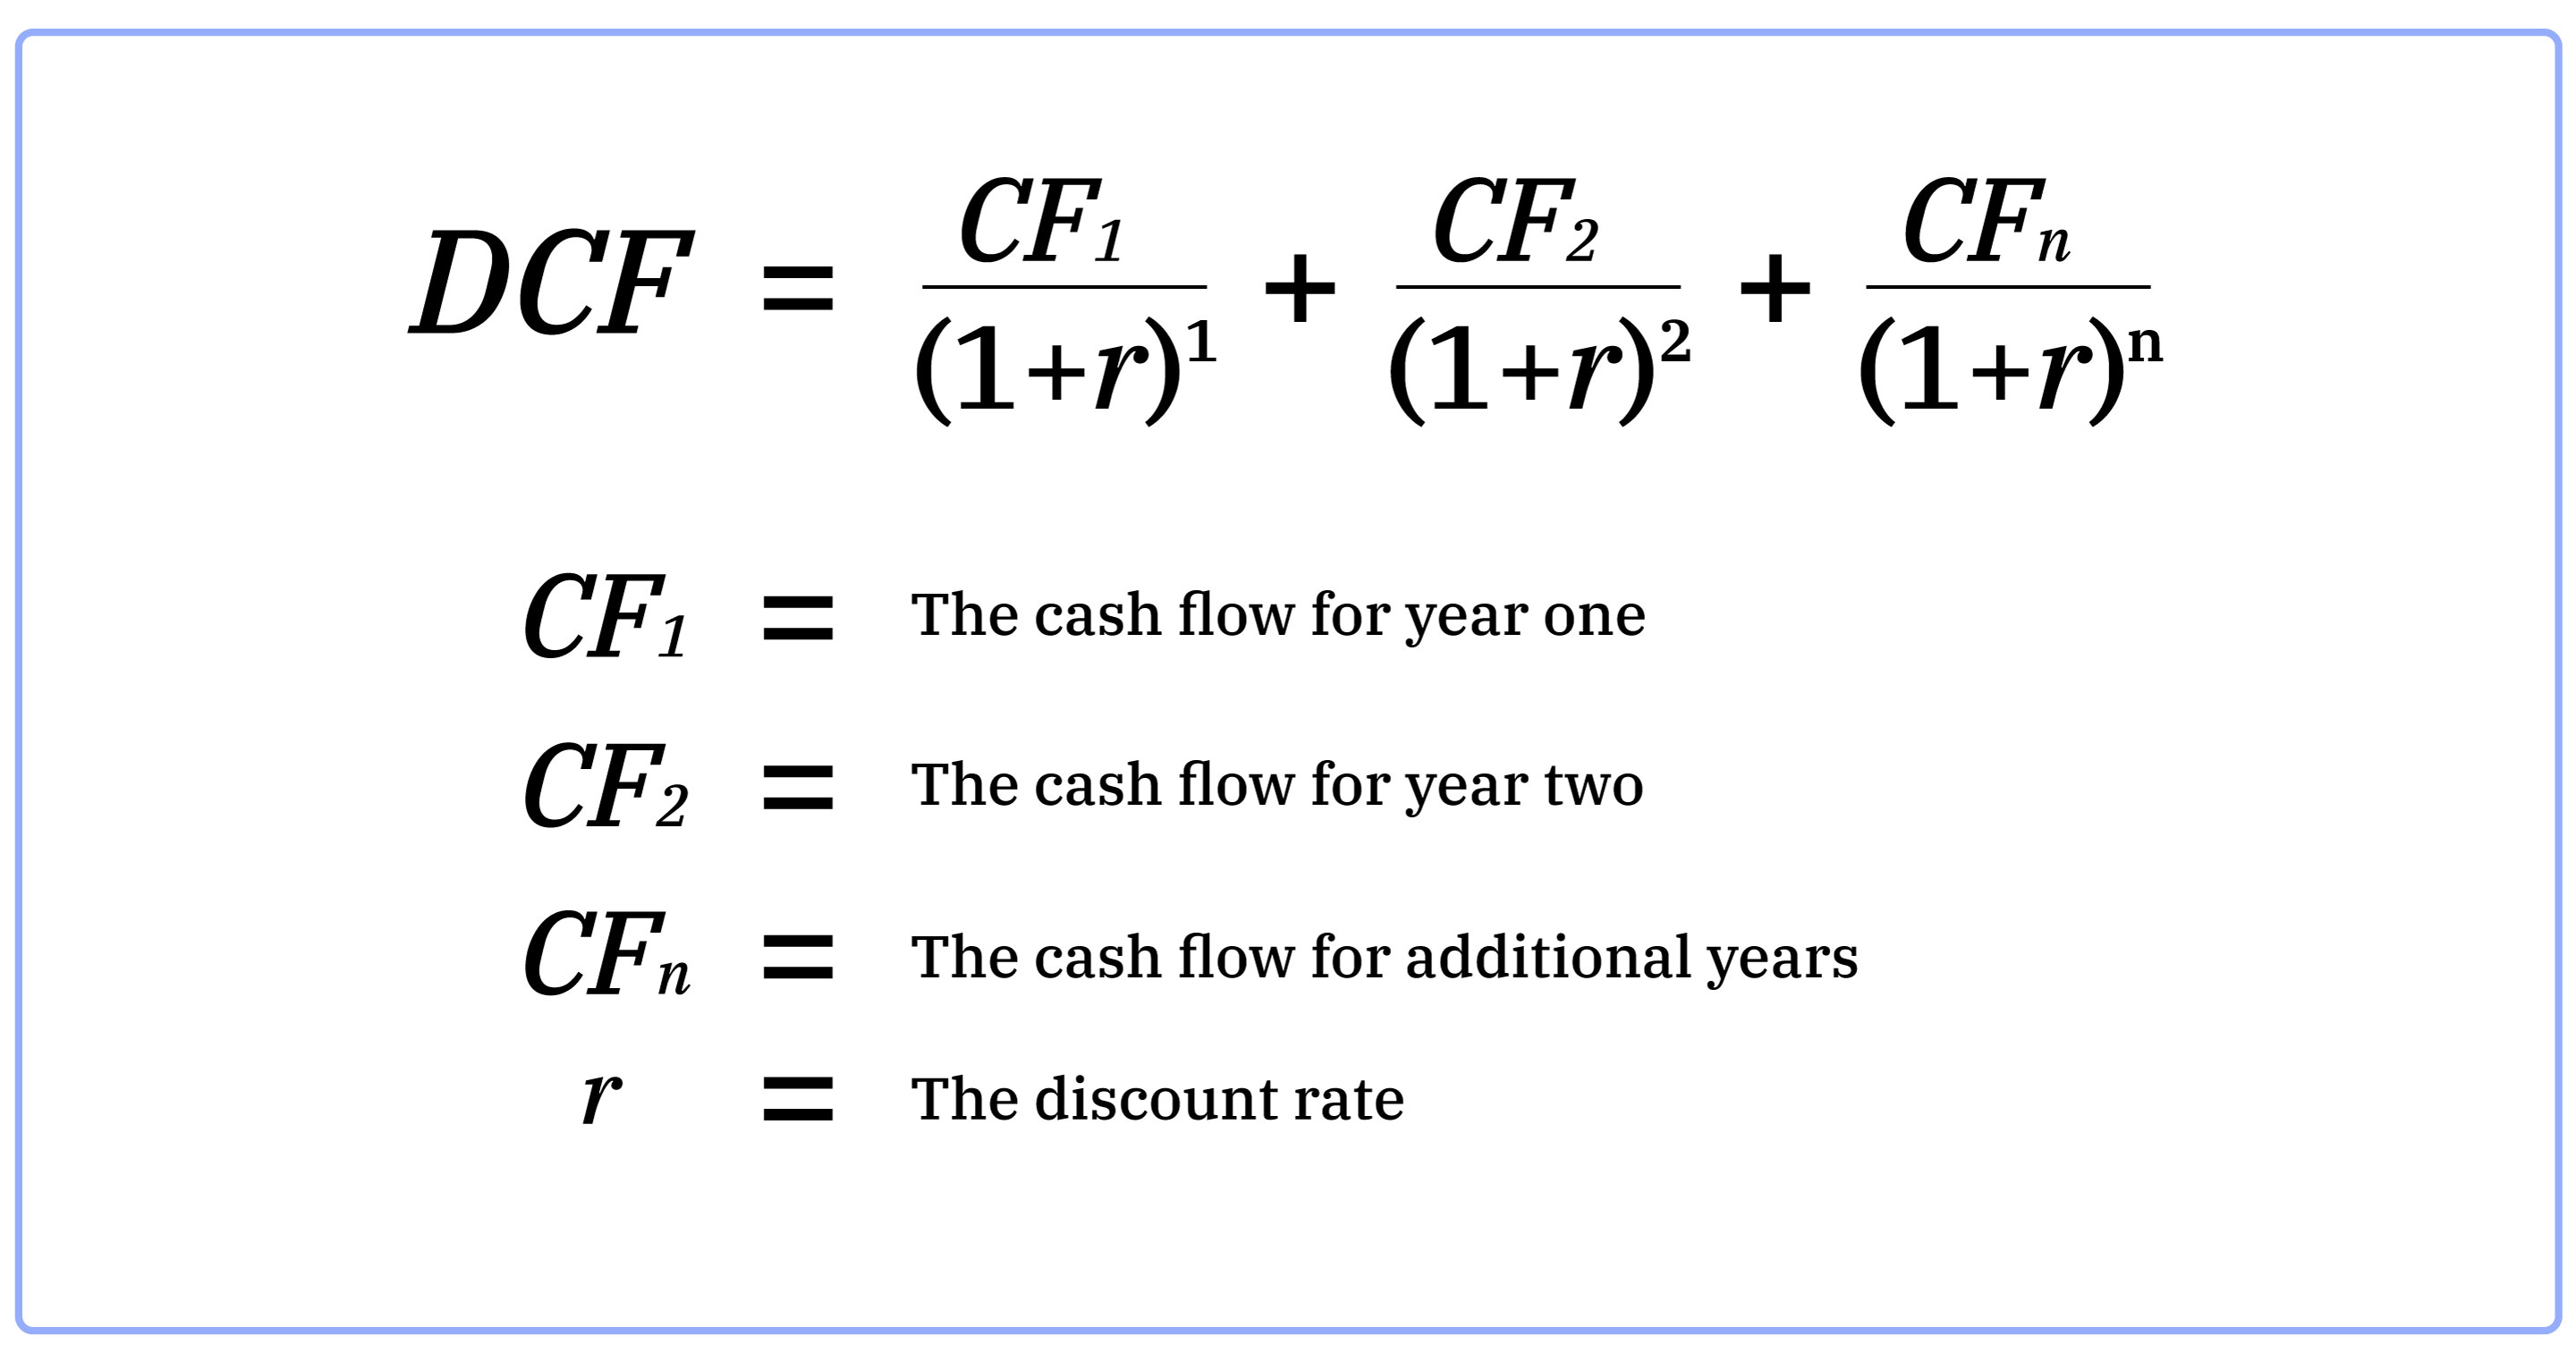
I spent three years building financial models for private equity firms before I stopped caring about making them look pretty. The truth is, a Dcf Calculator is a tool that compounds small errors into enormous ones. That is not criticism of the method itself. It is criticism of how people use it. Most spreadsheet templates you find online assume growth rates, terminal values, and discount rates come from thin air. They do not. The calculator is neutral. Your inputs are the problem. A discounted cash flow model projects free cash flows into the future, then discounts them back to present value using a required rate of return. You add the present value of those projected cash flows to the present value of a terminal value, and you get an enterprise value. Subtract net debt, divide by shares outstanding, and you have an equity value per share. That is it. Simple math. Brutally sensitive math. The calculator handles the arithmetic. It does not handle the assumptions. This distinction matters because almost every beginner confuses the two and then blames the model when their output looks wrong.
Building one from scratch
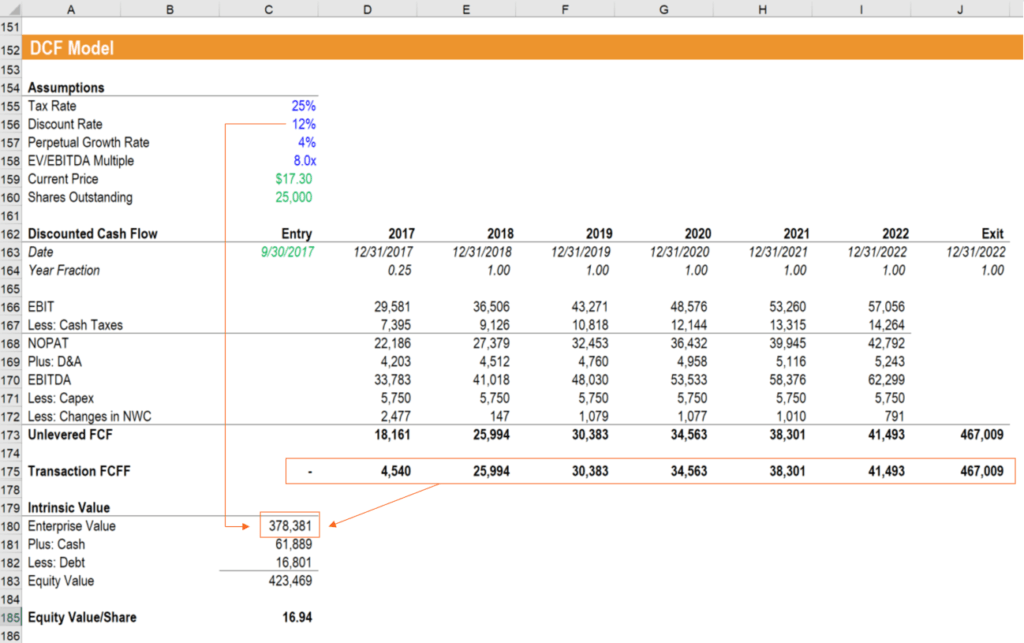
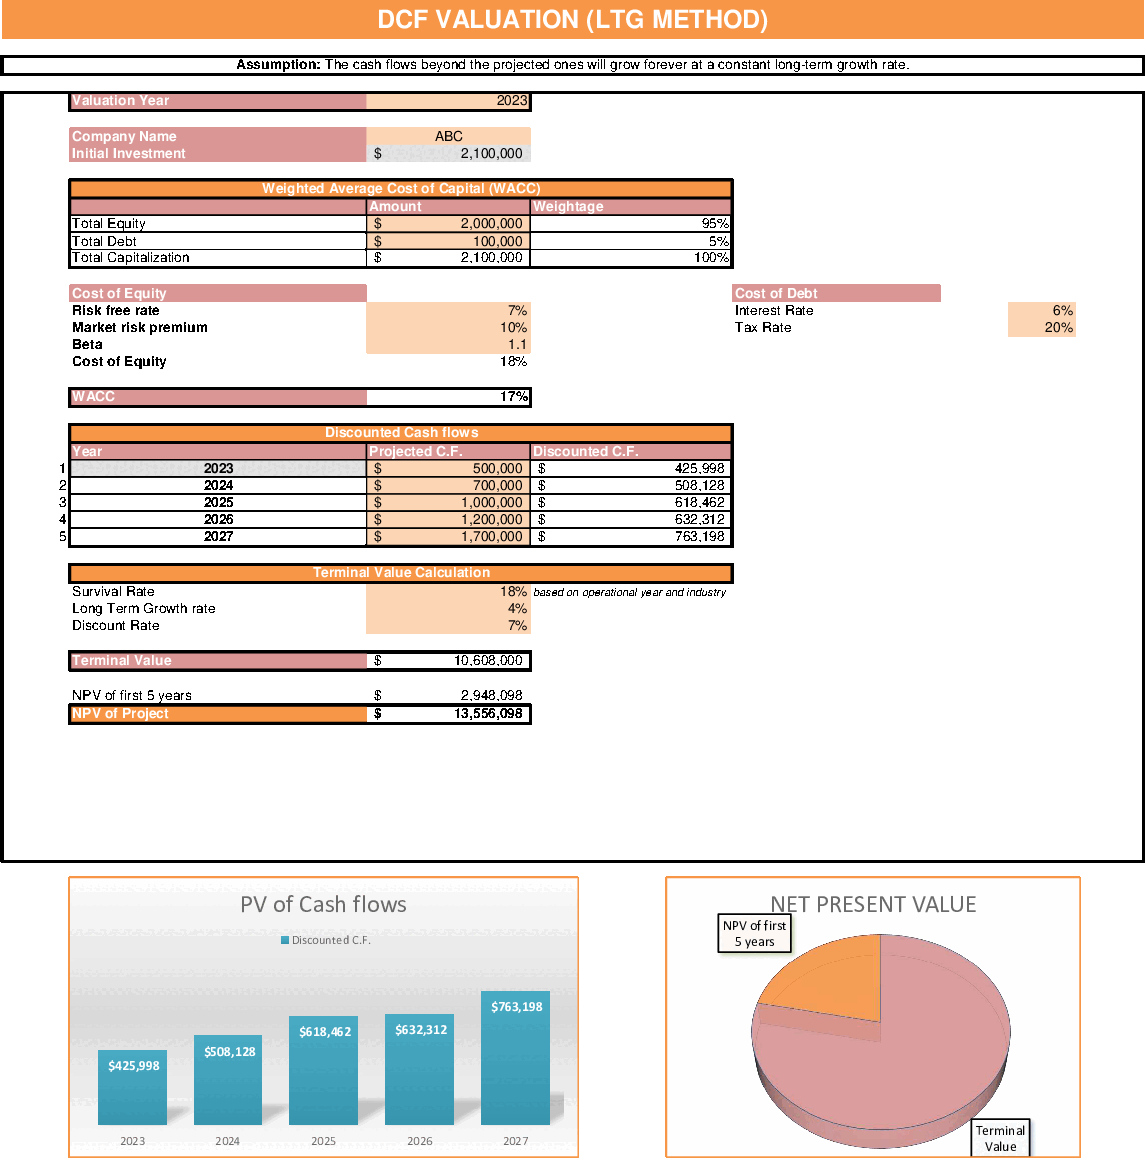
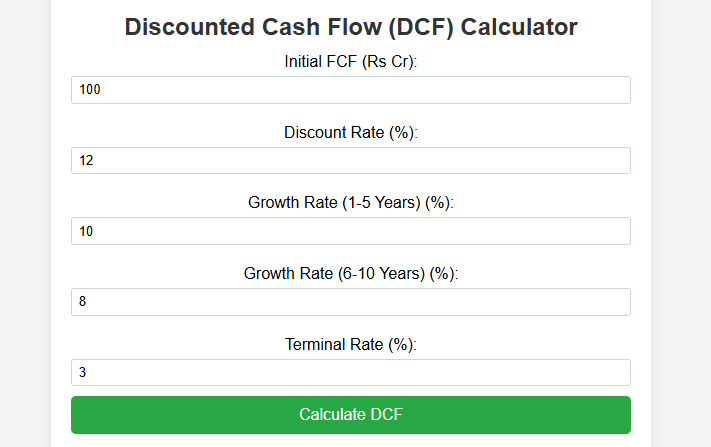
I used to build these from scratch instead of downloading some pre-made template. It takes longer upfront. I cut my modeling time from roughly two hours down to twenty minutes after I stopped reinventing the wheel on my third model. Now I use a custom Excel file with locked formulas and clearly labeled input cells. My company uses a DCF Calculator spreadsheet that has been through four rounds of revision since I stopped trusting generic downloads. Here is the basic structure you need: Input section: Current free cash flow, revenue growth assumptions for years one through five, terminal growth rate, weighted average cost of capital, net debt, and shares outstanding. Put these in a clearly separated area. Use a light yellow background so anyone opening the sheet knows immediately where to change assumptions.
Projection section: Year-by-year free cash flow calculations. Link growth rates to your inputs. Do not hardcode dollar amounts in this section. Every number must trace back to an input cell. Discounting section: Present value calculations using the WACC as your discount rate. The formula is straightforward: each year's free cash flow divided by one plus WACC, raised to the power of the year number. Terminal value section: Use the perpetuity growth method unless you have a specific reason to use the exit multiple approach. Multiply year five free cash flow by one plus the terminal growth rate, then divide by WACC minus terminal growth rate. Discount that back to present value using the same WACC.
Get the Full Details
A real problem I ran into
Last year I was valuing a logistics company with highly cyclical revenue. The standard DCF approach kept producing valuations that were nowhere near what the market would pay. The problem was that a single terminal growth rate of two and a half percent completely ignored the reality that the company's cash flows would fluctuate dramatically between boom and bust cycles over any realistic projection horizon. The calculator gave me a clean number. The number was wrong. The workaround was to model three separate scenarios explicitly instead of relying on the terminal value to absorb all the uncertainty. Base case with median assumptions, downside with slower growth and higher WACC, and upside with accelerated adoption of their new automation contracts. I weighted them at sixty, twenty-five, and fifteen percent respectively based on management guidance and order backlog visibility. The resulting range was $42 to $68 per share instead of a single point estimate of $51. The board preferred the range. It was more honest.
Things nobody warns you about
Terminal value dominates everything. In a standard five-year DCF, the terminal value typically accounts for sixty to eighty percent of total enterprise value. If you change the terminal growth rate from two percent to three percent, you are likely adding fifteen to twenty percent to your final valuation. Not ten. Not five. Fifteen to twenty. This means your forecast accuracy for years one through five barely moves the needle compared to whatever you assume for the perpetual period. WACC is not a precision instrument. The cost of equity calculated through CAPM depends heavily on your beta selection. A beta of 1.1 versus 1.3 changes your cost of equity by roughly forty basis points. Your weighted average cost of capital might shift by twenty to thirty basis points. That sounds small. Applied to discounted cash flows over a decade, it changes the result by eight to twelve percent. Nobody can tell you with confidence which beta is correct for a private company. Nobody should pretend they can. Free cash flow is not operating cash flow. Some calculators use operating cash flow by mistake. Free cash flow is operating cash flow minus capital expenditures. If you skip the capex subtraction, your valuation will be inflated. This is the single most common error I see in downloaded templates. They label the line "cash flow" and leave it at that. Check every line item against its definition.
When a Dcf Calculator gives you nothing useful
Asset-heavy businesses with short useful lives like mining operations or heavy manufacturing often produce misleading results from a standard DCF. The model assumes cash flows continue indefinitely at a stable rate. These businesses deplete or degrade their asset base within a decade or two. A sum-of-the-parts approach or a replacement cost model serves better here. Early-stage companies with negative or highly erratic cash flows are another category where the DCF breaks down. Revenue multiples, venture capital method, or scenario analysis will give you more actionable insight than forcing a DCF onto cash flows that do not exist yet. The calculator will produce a number. The number will be meaningless. Financial institutions require a different framework entirely. Their capital structure is their business, not a financing decision. Using WACC and free cash flow to value a bank or insurance company produces garbage. Book value adjustments and dividend discount models are the standard approach in those industries.

Where to get a working file
You can find basic templates on any finance education site, but most of them are designed for academic exercises rather than actual work. A proper DCF Calculator should have separate input cells, locked formulas, sensitivity tables, and scenario toggles. If you cannot change the growth rate without breaking the model, the template is poorly built. For something that handles the cycle problem I described earlier, you would need a model with built-in scenario weighting and multiple terminal value calculations. I modified mine to include a data table that shows how valuation changes across combinations of WACC and terminal growth rate. That data table alone took me an afternoon to set up. It replaced about thirty minutes of manual recalibration every time I needed to present a range.
What to check before trusting any output
Run a sanity test. Take your final valuation per share and compare it to the current trading price or recent transaction prices in the same sector. If your DCF says the company is worth twice the market price, something is wrong with your assumptions. Most likely your growth rate is too high, your terminal value is overstated, or you are using an insufficient discount rate. Check the sensitivity table. Adjust one variable at a time and watch how the output changes. If every change produces roughly proportional movement, the model is behaving normally. If a one-percent change in terminal growth produces a ten-percent change in valuation, your projection period is too short or your terminal value formula is misconfigured. I have seen people use three-year projections paired with a terminal value assumption and wonder why the result feels arbitrary. Extend the explicit projection period to at least five years. Even ten years if the business has a long runway for growth. The longer your explicit period, the less dominant the terminal value becomes, and the more your valuation actually reflects the cash flows you projected rather than a guess about forever. The DCF Calculator is a tool, not an answer. It requires input from someone who understands the business being valued. If you are plugging in numbers without understanding where they come from, the model is just automating your ignorance faster.