
Working Through the Basics Before You Actually Do It
Most people learn debits and credits as separate, opposing forces. They memorize the acronym DEALER or DEAD CLIC and move on. That approach works for introductory quizzes but breaks down fast when you're staring at a real journal entry at 11pm the night before month-end close. I stopped trying to memorize lists and started thinking about what actually happens to the account when a transaction hits the system. The fundamental rule is simpler than most textbooks make it. A debit is just a left-side entry. A credit is just a right-side entry. That's it. The question that actually matters is whether the account being affected increases or decreases on that side. Assets and expenses increase on the debit side. Liabilities, equity, and revenue increase on the credit side. Once you lock that down, everything else follows without needing a trick device.
Common Debit And Credit Accounting Practice Problems
I see the same mistakes show up repeatedly in practice problems and real-world entries. Here are the ones that actually cost people points and time. The first big one is treating every account the same way. A student will see "cash" in a problem and automatically debit it because cash feels like an asset that should go up. But what if the business is paying rent? Cash is going out. The asset account decreases, so it needs a credit. The confusion comes from not separating the account type from the direction of the transaction. Always identify the account type first. Then decide if it's increasing or decreasing. Then apply the rule. The second common problem is ignoring multi-part transactions. Textbooks love simple two-account entries at first, but the real world rarely works that way. A typical problem might involve purchasing inventory on account, then later paying off part of the balance with a discount. Each step is its own journal entry. People lose track of which accounts have already been touched and try to adjust them again. Keep a running trial balance as you work through each step. It takes extra minutes but saves hours of debugging at the end.
The third issue I encounter constantly is the adjustment entries. Depreciation, prepaid expenses, accrued revenue, unearned revenue. These are where theory meets reality. Students often know how to record the original transaction but freeze when asked to adjust it at period end. The problem is usually not the accounting itself but the failure to map the adjustment back to the original entry. When you see a prepaid insurance adjustment, remind yourself that the original debit went to a prepaid asset, not an expense. The adjusting entry moves a portion of that asset to expense. That mental link makes the whole process click. Here's a specific edge case I ran into recently that most practice problems skip entirely. A client was processing intercompany transfers between two subsidiaries in different currencies. The standard debit-credit logic still applied, but the exchange gain or loss created a third account that nobody seemed to know where to plug in. The workaround was straightforward once you step back from the numbers. Treat the foreign currency difference as a separate transaction that happens at the moment of transfer. Debit or credit the intercompany account for the local currency amount, and the offset goes to the foreign exchange gain or loss account. It's not a special rule. It's just recognizing that the currency conversion is a distinct economic event layered on top of the transfer. Another counter-intuitive thing about debits and credits that trips people up regularly: the normal balance of an account doesn't determine whether a debit or credit increases it. The normal balance tells you which side carries the positive balance, but the increase or decrease depends entirely on the account type classification. A contra-asset like accumulated depreciation has a credit balance by definition, which means a debit actually decreases it. Beginners see the credit balance and assume credits increase the account. They don't. This distinction matters enormously when you're reconciling a balance sheet.
Get the Full Details
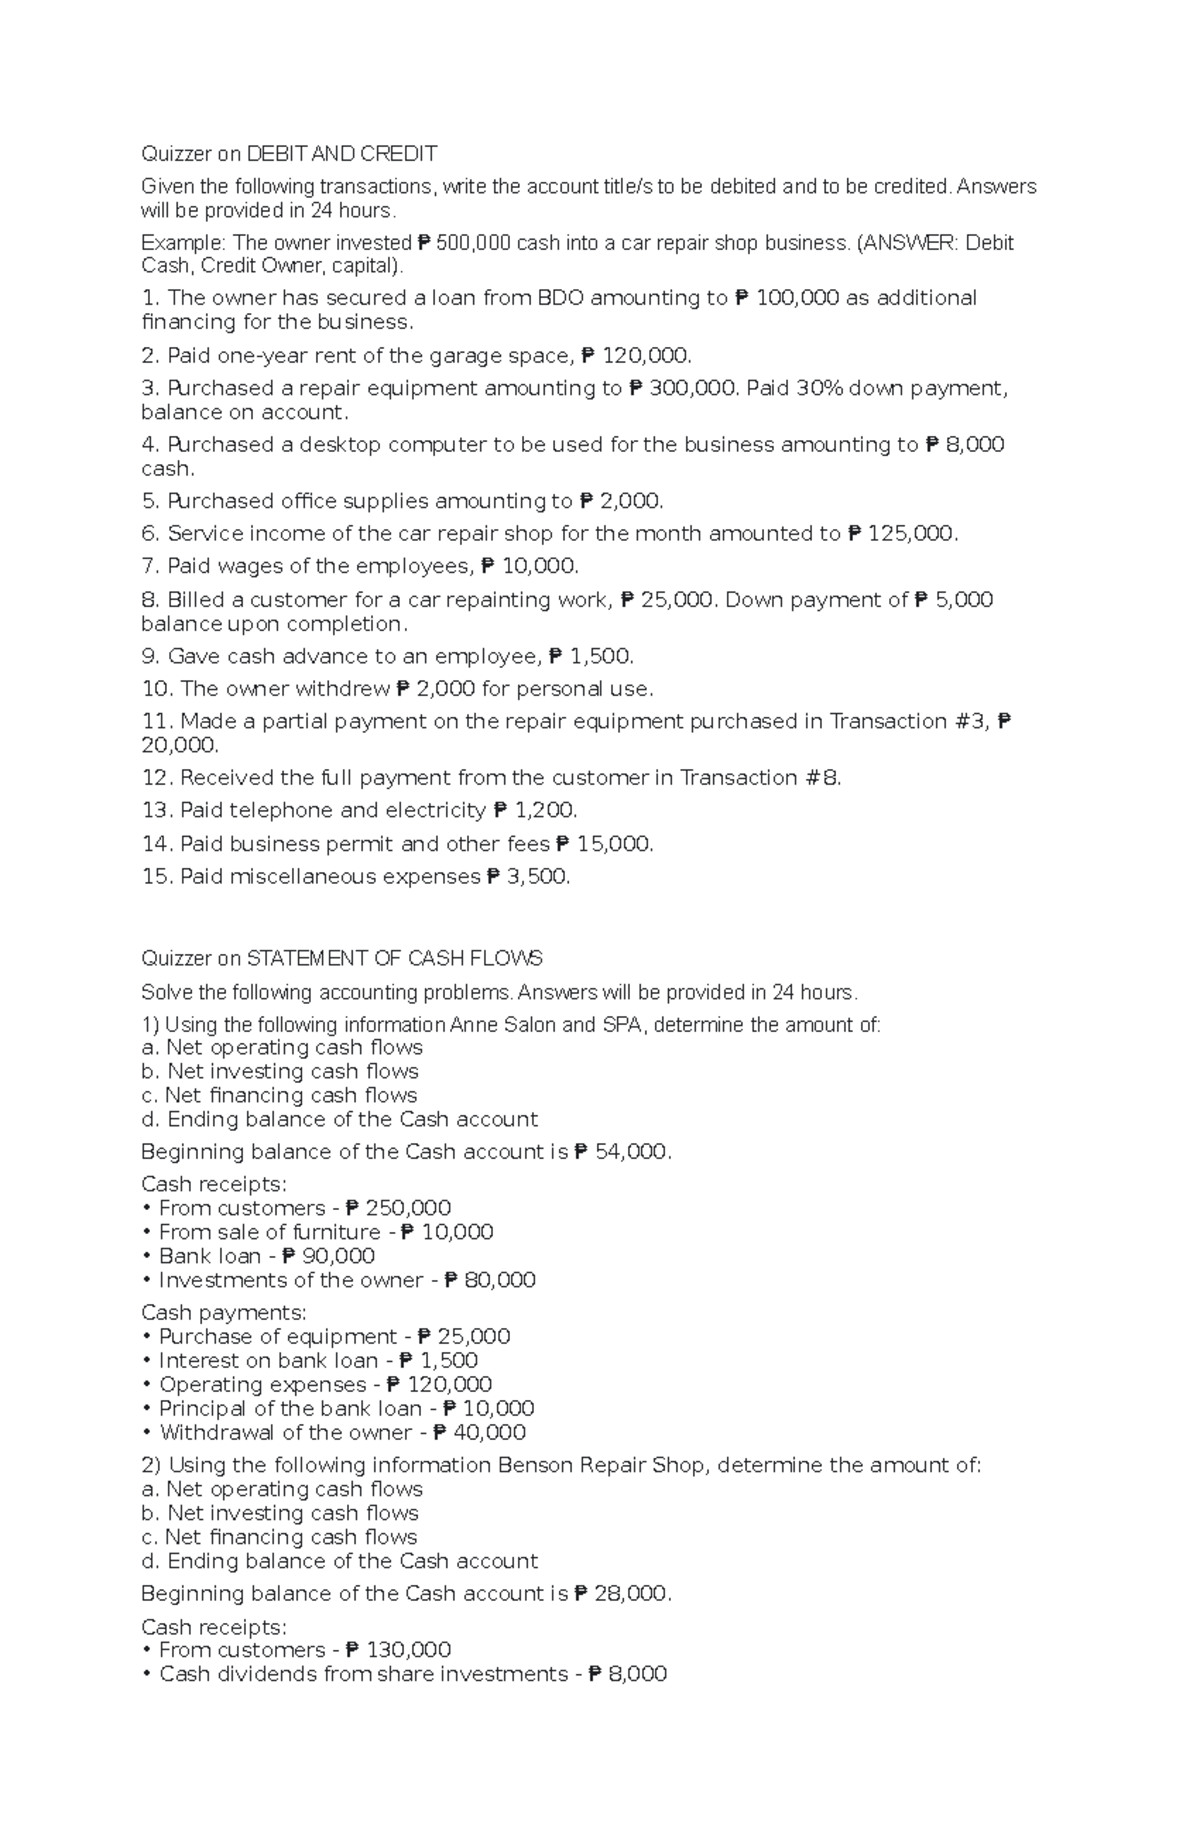
I also want to be honest about where this system runs into real limits. The double-entry model works beautifully for straightforward commercial transactions. It starts to get messy with complex financial instruments, lease accounting under ASC 842, or revenue recognition under ASC 606 where you're dealing with performance obligations spread across multiple periods. In those cases, the basic debit-credit framework still applies, but the determination of what gets debited and credited requires reading through contract terms and making judgments that practice problems rarely capture. No amount of drill sheets will prepare you for that. You have to work through actual financial statements and see how the standards play out in context. For practice, I'd recommend starting with straight journal entries using a free spreadsheet template. Don't use flashy accounting software while you're learning. Software hides the mechanics from you. Open a blank sheet, list your accounts on the left, put your transactions in chronological order, and build the entries by hand. Then post to a T-account diagram. Then run a trial balance. When the debits and credits don't match, you'll find the error yourself instead of clicking a button that just tells you something is wrong. There are several free resources online that provide practice problems with solutions. The OpenStax Accounting textbook has a chapter of exercises specifically on journal entries and adjusting entries. The accounting department websites at state universities sometimes post problem sets with answer keys. I've used those before when I needed fresh material that didn't feel repetitive. The problems themselves are usually fine, but don't treat the answer key as gospel. Cross-check any discrepancy by going back to first principles. If the key doesn't match your reasoning, walk through the logic one more time before assuming you're wrong.
One final practical note about building fluency. Time yourself on basic entries until you can do them without hesitation. Five simple transactions in under three minutes should be your target before moving on to combined problems. Speed isn't the goal, but automaticity frees up mental bandwidth for the harder stuff. When you're wrestling with a complex revenue recognition scenario, you don't want to be second-guessing whether a liability increases with a debit or a credit. That should be background noise by that point.


