How The Debt Snowball Actually Works
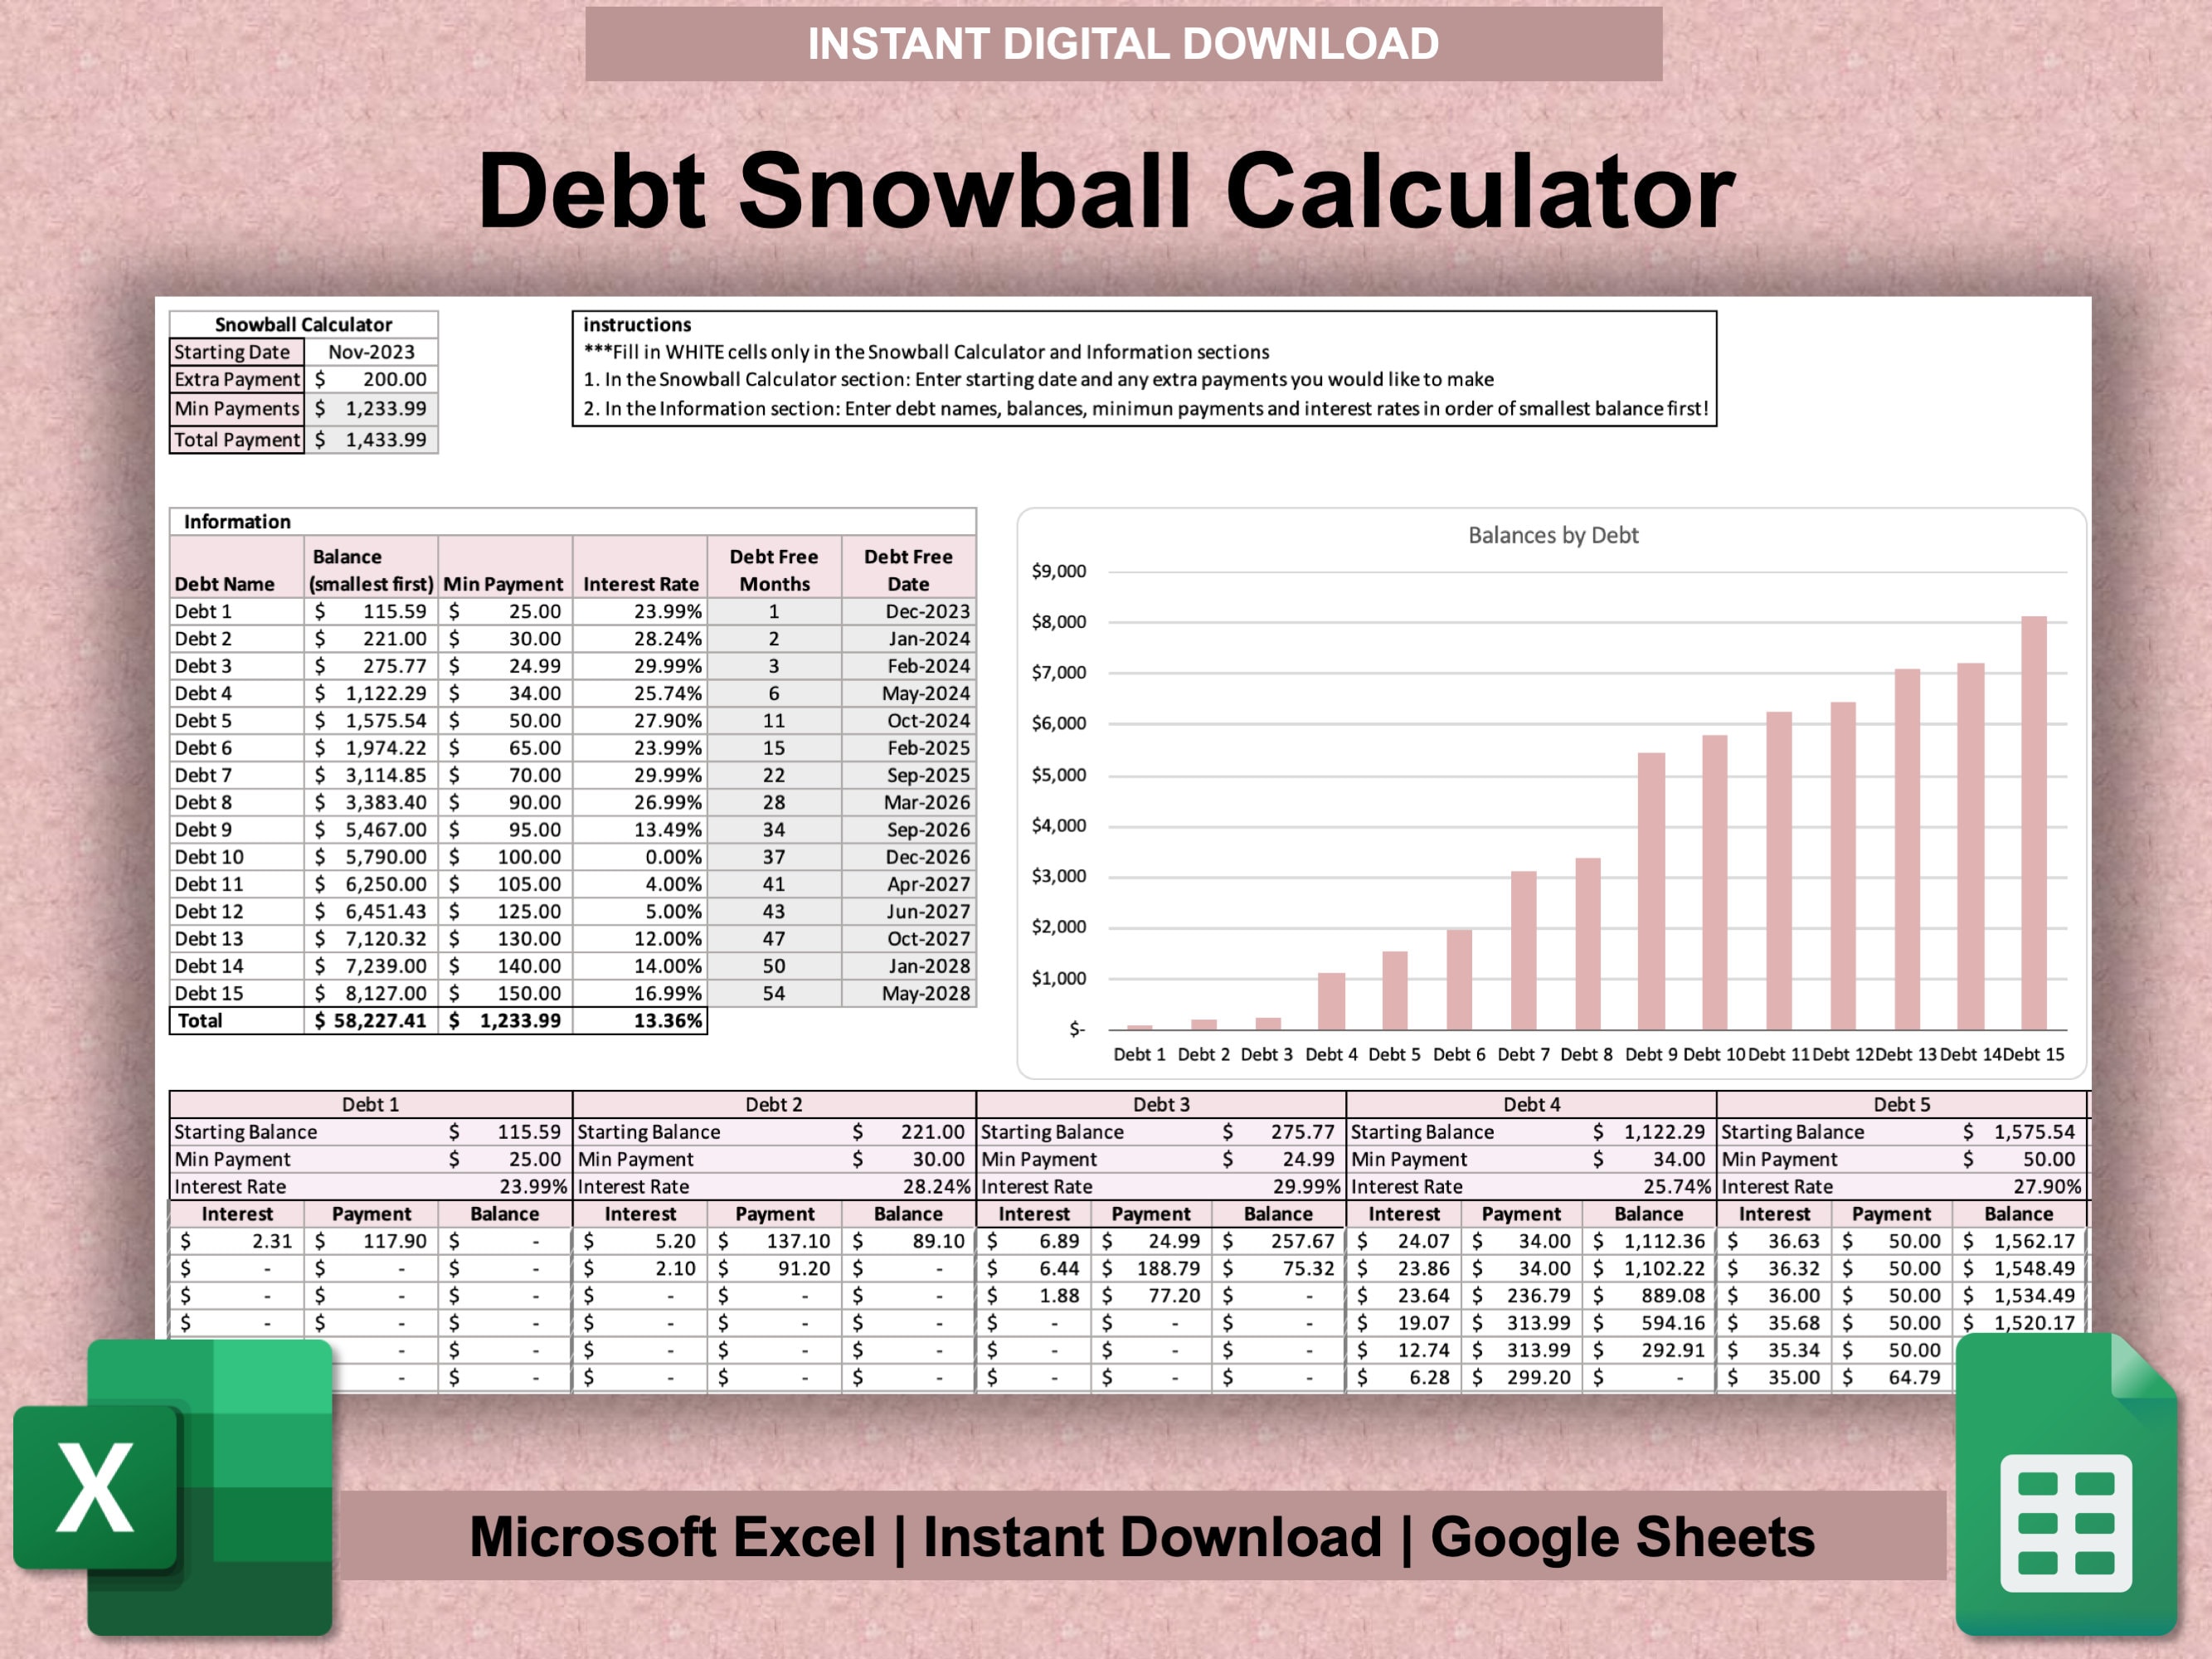
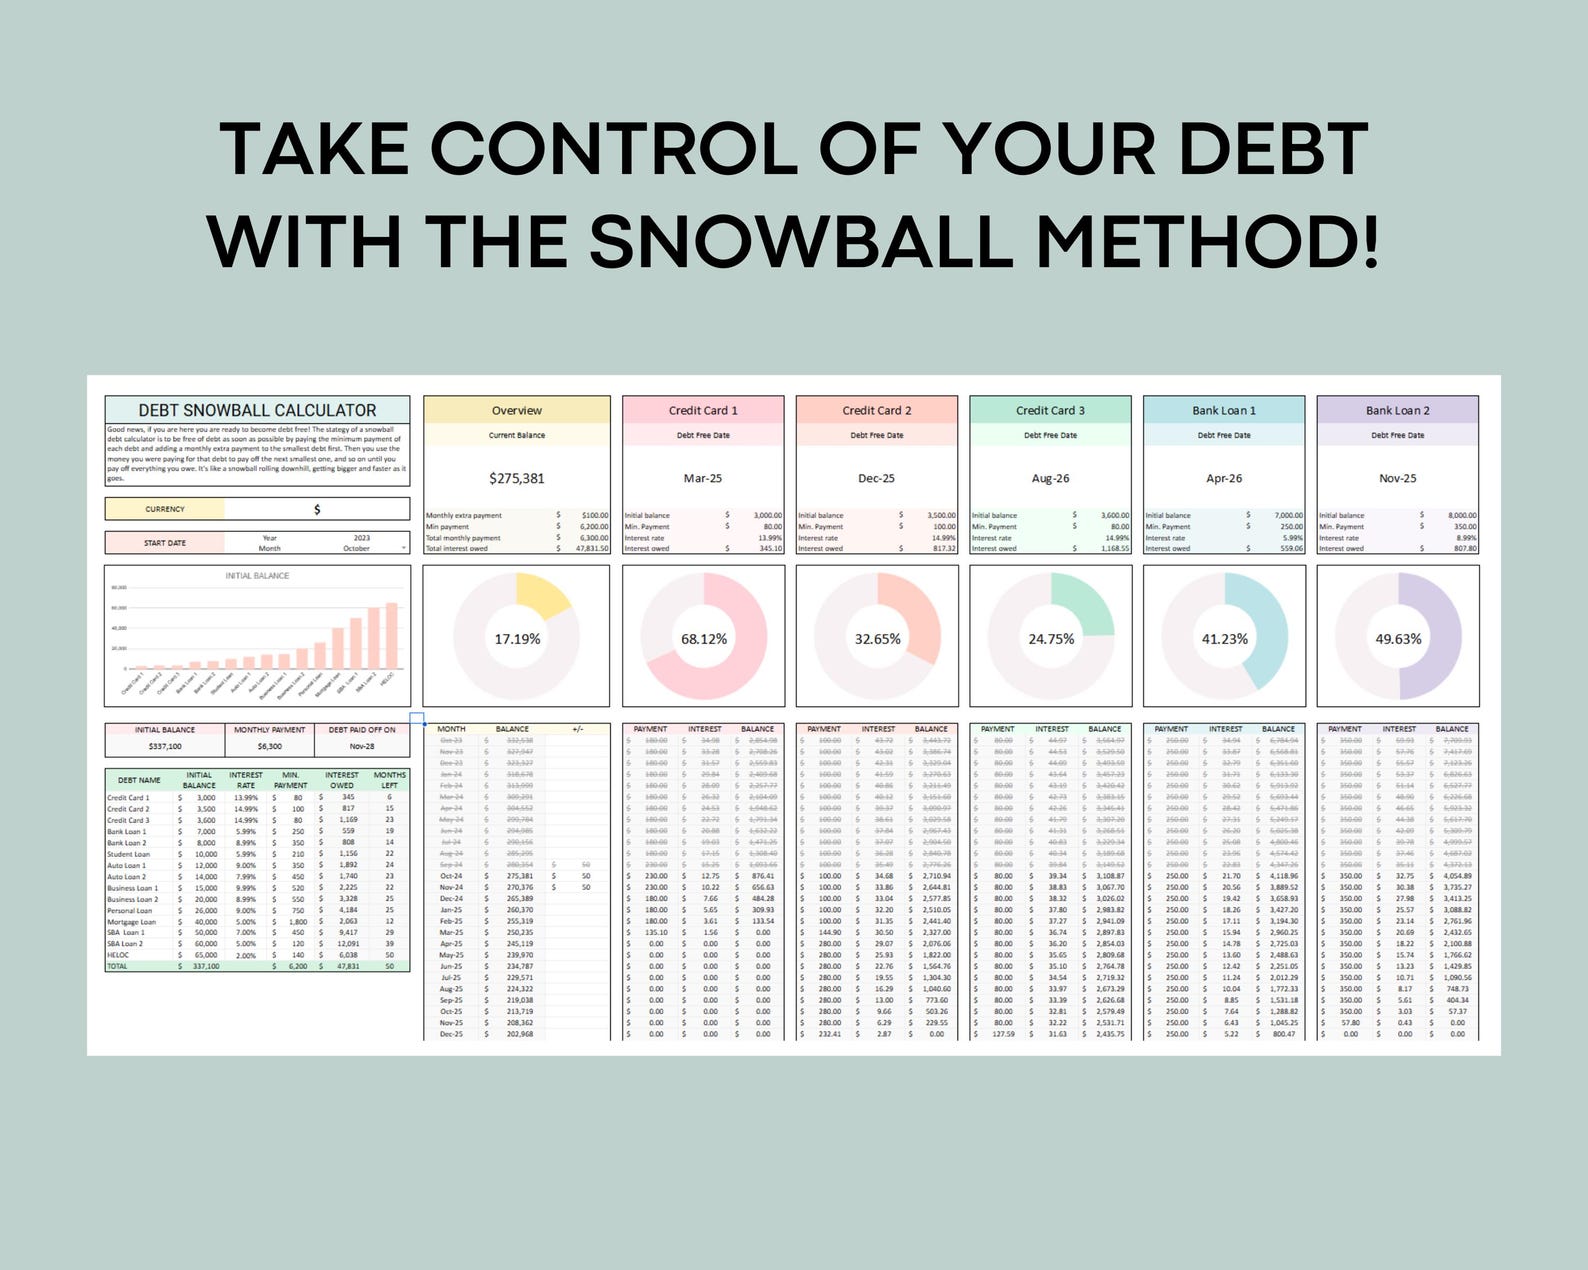
A Debt Snowball Calculator is a tool that takes your list of debts, orders them from smallest balance to largest, and shows you month-by-month how paying off the smallest first changes your payoff timeline. The method itself is straightforward: list every debt by balance, pay the minimum on all of them, throw any extra money at the smallest balance, clear it, then take that entire payment and redirect it to the next smallest. Repeat until nothing is left. The "snowball" name comes from the payment amount growing each time you eliminate a debt. Your total monthly debt payment stays the same, but the portion going toward your target balance increases dramatically with each payoff. It is not mathematically optimal, but it is psychologically effective for people who are struggling to stay consistent.
A Concrete Example
Say you have three debts: Debt A: $400 credit card, $12 monthly minimum, 18% APR
Debt B: $1,800 medical loan, $50 monthly minimum, 7% APR
Debt C: $7,500 student loan, $90 monthly minimum, 5% APR You have $300 extra per month to apply toward debt. Without a snowball, you would split that $300 however you like, probably proportionally. With the snowball method, you throw all $300 at Debt A each month until it is gone.
Month 1 through Month 4: You pay $12 + $300 = $312 toward Debt A, minus accrued interest. Debt A clears around month 4. Your total minimum payments across all debts are $152, so your "extra" capacity when focused on Debt A is $148 per month above the minimums. Once Debt A is gone, Debt B suddenly receives $50 minimum + $312 from the former Debt A payment, totaling $362 per month. Debt B clears much faster than it would have on its own. Then Debt C gets even more.
Get the Full Details
Where A Debt Snowball Calculator Helps You Avoid Common Mistakes
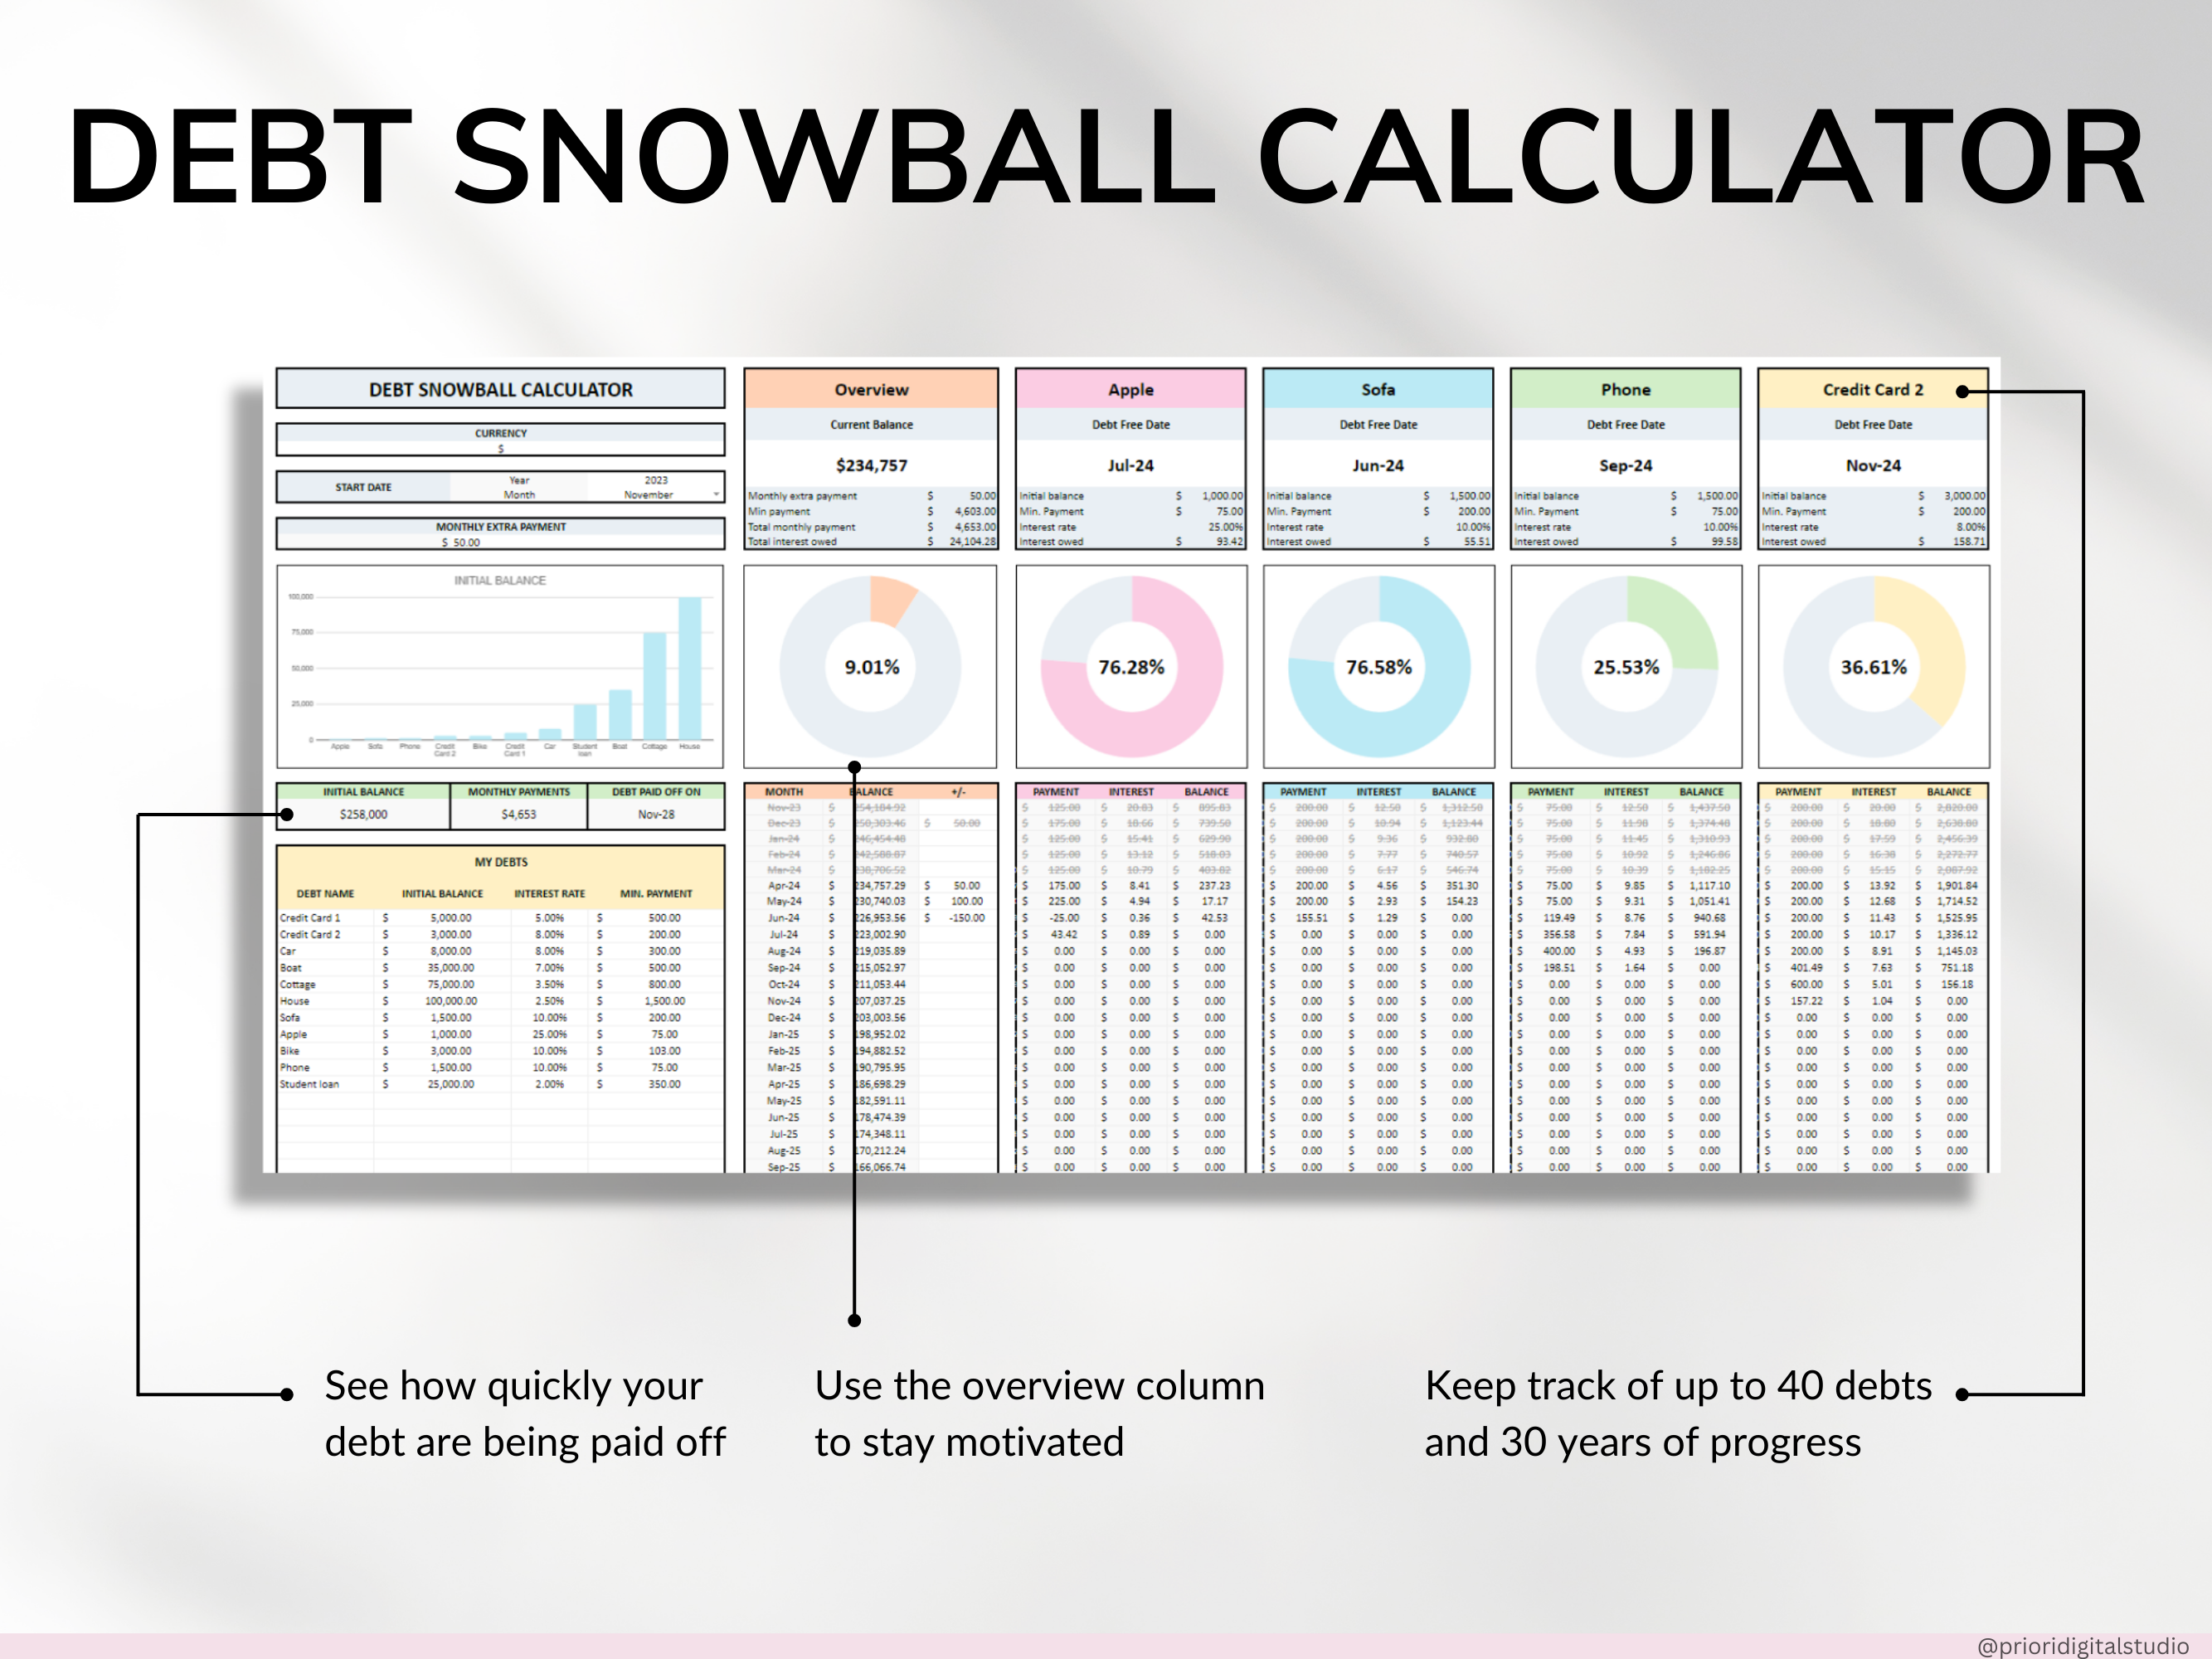
I built a spreadsheet-based payoff tracker a few years ago because the free calculators online kept giving me results that didn't match my actual bank statements. The problem was almost always interest accrual timing. Most simple calculators assume your first payment happens immediately and that the balance doesn't grow before you start attacking it. In reality, your statement closes at a specific date, interest posts daily or monthly depending on the creditor, and your first snowball payment might not go in for two weeks after you open the tool. My workaround was simple: I pulled the exact current balance from each creditor's most recent statement, calculated the monthly interest factor manually (APR divided by 12, applied to the average daily balance), and added roughly 2% to each projected payoff duration to account for timing mismatches between the calculator's assumption and my actual payment schedule. The final result was within a week of what my actual payoff dates turned out to be. The free online Debt Snowball Calculator tools typically don't do this step, which is why their timelines can be optimistic by a month or two on small debts and by several months on larger ones.
The Math Behind The Method
Each debt has a monthly interest component. If a balance is $400 and the APR is 18%, the monthly rate is 1.5%. After one month, the balance before your payment would be $406. If you pay $312, the remaining balance is $94. The next month, interest is calculated on $94, not $400, so the snowball effect becomes visible in the numbers themselves. When you clear a debt, the entire payment you were making on it—minimum plus extra—rolls into the next target. This is what makes the total payment on your remaining debts escalate quickly. A $50 minimum payment on a debt you just paid off might now be going toward a $2,000 balance, turning a $50 monthly bite into a $350 monthly bite.
When The Snowball Is The Wrong Tool
The debt snowball ignores interest rates entirely. If you have a $3,000 credit card at 26% APR and a $500 car loan at 4.5% APR, the snowball tells you to pay off the car loan first because it is smaller. The avalanche method—targeting highest interest rate first—would save you money. On a 26% balance, that $500 is far more expensive than the $3,000 at 4.5%. Paying the card first would cost you less in total interest over the life of the debt. However, the snowball still has a role. People who have tried the avalanche and given up halfway through because the progress felt too slow are exactly the people the snowball is designed for. Mathematical optimality does not matter if you abandon the plan because no debt disappeared in six months. A tool like a Debt Snowball Calculator can help you see the timeline, but you have to decide whether staying on track matters more than saving a few hundred dollars in interest.
Edge Case: What Happens When Interest Compounds Between Cycles
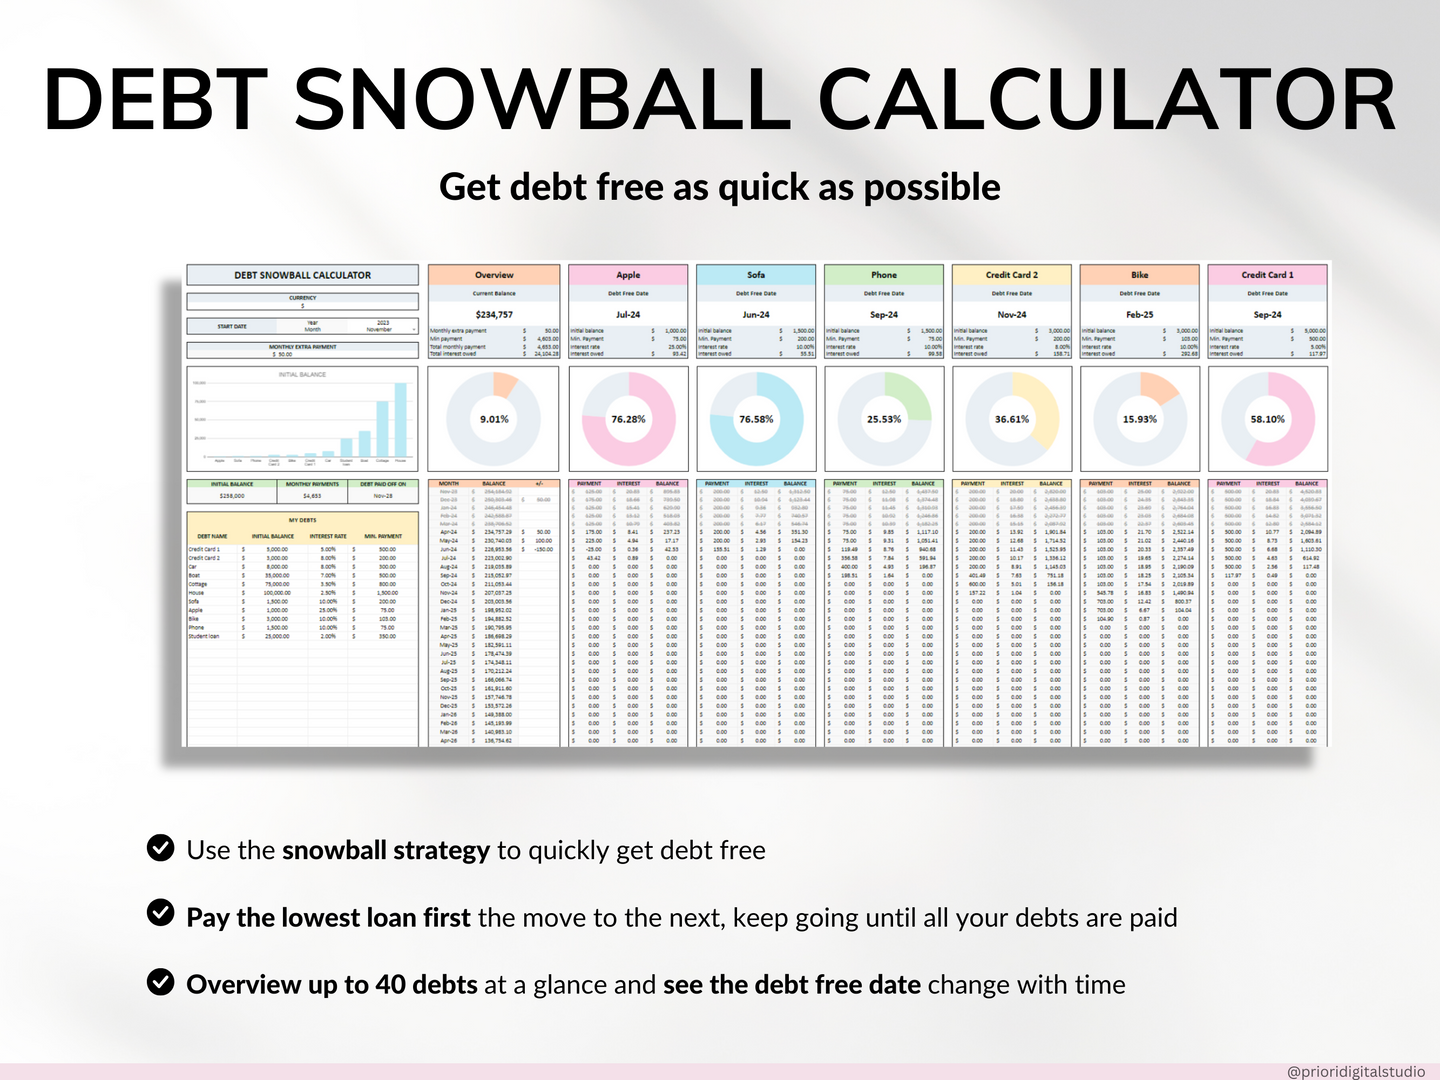
Some creditors compound interest daily. Others compound monthly. Some use the average daily balance method. When you are calculating a payoff schedule, this detail matters more than people expect. I once used a calculator that assumed monthly compounding for a collection account that actually compounded daily. The projected payoff was three months shorter than what actually happened because the balance grew faster than the tool assumed. The fix was to switch to a daily compounding model in my spreadsheet, which added approximately one month to the payoff timeline for that specific debt. If you are using a Debt Snowball Calculator and your actual payoff dates drift from the projections, check your creditor's interest method first. Most of the time the variance comes from compounding assumptions, not from the snowball structure itself.
What To Do Before You Run The Numbers
Gather your most recent statement for every debt. Note the current balance, the minimum payment, the APR, and whether the issuer compounds daily or monthly. Enter these into the calculator. Do not round your balances down to clean numbers. A $1,247 balance is not a $1,250 balance, and the interest difference between the two will compound over the life of the payoff. The calculator output will be slightly more accurate if the input is exact. After the calculator gives you a schedule, verify at least the first two months manually. Multiply the opening balance by the monthly rate, subtract your payment, and confirm the result matches the tool's second-month balance. If it does not, the tool is likely using a simplified interest model that may drift over longer timelines. Adjust accordingly.
Practical Limits Of The Method
The debt snowball works best when you have three to eight debts. Beyond that, the mental overhead of tracking rolling payments increases and the compounding momentum starts to feel less rewarding. It also assumes you have a fixed extra amount each month. If your extra cash varies—bonus one month, unexpected expense the next—the snowball timeline becomes less reliable. In those cases, the method still works, but you should recalculate whenever your available extra payment changes by more than 15%. If you have a single large high-interest balance alongside several small ones, the snowball may not be the fastest path out. Consider running both a snowball and an avalanche projection side by side before committing. The difference in total interest paid can be significant on high-rate debt, and knowing that number helps you decide whether the psychological win of a quick payoff is worth the cost.