Building a Debt To Income Ratio Worksheet That Actually Works
Most people build their DTI calculation wrong the first time. They list monthly debt payments and divide by gross monthly income, then get confused when the lender's number doesn't match. The gap is usually in how different obligations get classified and reported. A proper Debt To Income Ratio Worksheet accounts for the things most calculators ignore. I'm going to walk you through the structure, the common mistakes, and then show you exactly where it breaks down in practice.
The Basic Structure
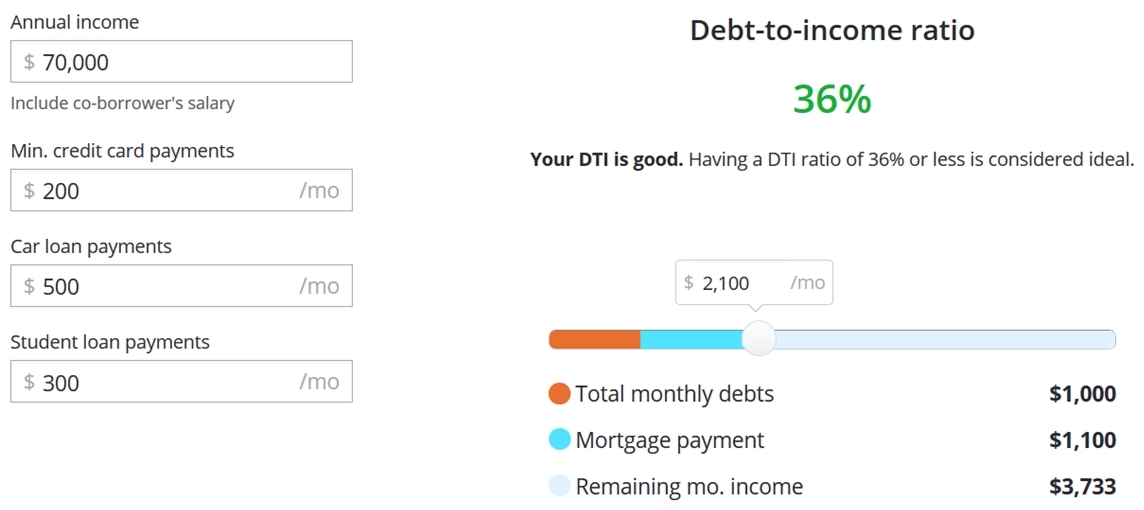
Start with two sections: gross monthly income and monthly debt obligations. For income, include base salary, bonuses, overtime, rental income, alimony, and any consistent supplemental income. Take annual figures and divide by 12. Don't use net income. Lenders use gross. Period. For debt obligations, list every recurring monthly payment: Mortgage or rent
Auto loans
Student loans
Credit card minimum payments
Personal loans
Child support or alimony payments you owe
Co-signed loan payments
Homeowner association fees (if escrowed separately)
Open lines of credit with available balances
Then apply the formula: total monthly debt divided by total monthly gross income, expressed as a percentage.
Get the Full Details
Where People Get It Wrong
The most common error is using credit card current balances instead of minimum payments. A $8,000 balance doesn't count as $8,000 a month. It counts as whatever the minimum payment is, usually 2 to 3 percent of the balance. Some lenders will calculate a hypothetical minimum at 3 percent if the statement minimum is below that. That detail matters more than you'd think. Another frequent mistake involves student loans. If the loan is in deferment or forbearance, some lenders still charge a monthly payment for DTI purposes. The standard approach is to use either the repayment plan payment shown on the loan servicer's statement or 1 percent of the outstanding balance, whichever is higher. If the loan is in the income-driven repayment bucket, use the documented payment amount. Auto leases count as debt. People forget this constantly. A $380 monthly lease payment goes straight into the DTI calculation just like an auto loan payment would.
The Edge Case I Keep Running Into
Last year I was working with a borrower who had $22,000 in medical debt she was actively paying down. She'd paid off $9,000 over six months and had a structured repayment plan for the remainder. Her DTI looked terrible on paper because the outstanding balance was still dragging down her numbers. The workaround was straightforward: we pulled documentation showing the account was in a formal repayment arrangement, got the lender to verify the reduced monthly obligation of $340 instead of the minimum-payment calculation, and that dropped her back-end ratio by nearly 4 percent. Without that documentation, the worksheet would have told her story incorrectly. This happens more often with medical debt and collection accounts that have been paid but not yet removed from the credit report. The worksheet should reflect the actual current obligation, not the stale credit report number. You need supporting paperwork to make that argument stick.
Two Distinctions That Change Everything
First, front-end versus back-end ratios. The front-end ratio is housing expenses only—principal, interest, taxes, insurance, and HOA—divided by gross monthly income. Most conventional loans want this at 28 percent or below. The back-end ratio includes everything and that's the number people actually care about. Conventional loans typically target 36 percent, though many programs approve up to 45 percent with strong credit scores or compensating factors. FHA loans can go higher in some cases, sometimes up to 57 percent if the borrower has significant residual income. Second, seasonal or variable income gets handled differently. If you're self-employed or work commission, lenders typically average the last two years of tax returns. A single strong year doesn't protect you. The worksheet should reflect the averaged figure, not your best month. This is where people who had a killer year in 2023 get punished by a calculation that smooths everything out.

Building the Worksheet Itself
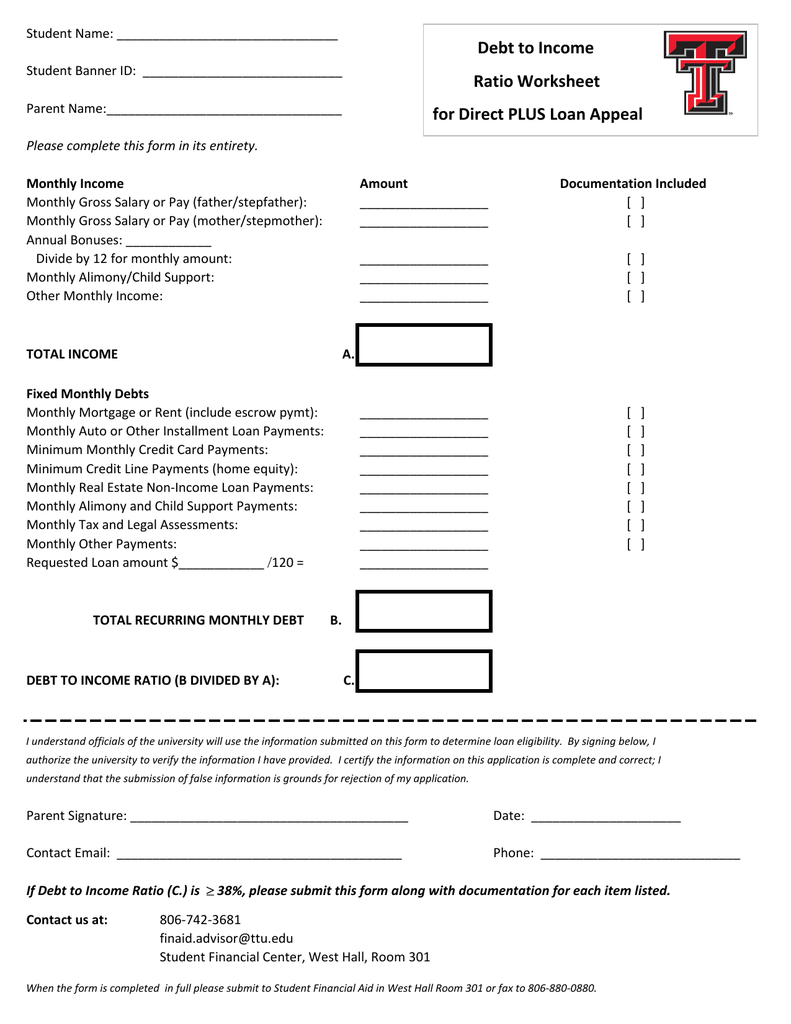
Set up columns for each income source and each debt obligation. Use separate lines for each account so you can note the creditor, account type, and current balance or payment amount. Add a column for the monthly payment that actually goes into the DTI calculation, which may differ from the statement amount. Include a notes section for any special circumstances—repayment plans, co-signed debts, deferred loans, or accounts under dispute. Sum the income column. Sum the debt column. Divide debt by income. Multiply by 100. That's your back-end ratio. If you're tracking the front-end ratio separately, sum only the housing costs and divide by income.
When the Worksheet Lies to You
DTI is a blunt instrument. It doesn't measure your actual financial flexibility. A person making $65,000 a year with $1,800 in monthly debt payments has a 33 percent DTI, which looks fine on paper. But if $1,400 of that debt is high-interest credit cards and personal loans, they're carrying a much heavier burden than the ratio suggests. Conversely, someone with a $2,200 monthly mortgage payment and no other debt might look like they're at 50 percent DTI, but that mortgage is building equity while the credit card debt is burning cash. The worksheet can't make that distinction. The ratio also completely ignores asset position. A borrower with $400,000 in invested assets and a 42 percent DTI is in a very different situation than someone with no savings and the same DTI. Lenders know this, which is why compensating factors exist, but the worksheet itself won't capture it.
A Note on What This Won't Fix
If your DTI is already above 50 percent and you're applying for a conventional conforming loan, no worksheet design will help. You'll need either a larger down payment, a co-borrower, or a different loan program. FHA, VA, and USDA have different guidelines. Some portfolio lenders will go higher but at significantly worse rates. The worksheet is a diagnostic tool, not a solution to a structural problem. If you're working with a lender who seems to be using a different calculation method than what your worksheet shows, ask them exactly how they're deriving the number. Discrepancies between your worksheet and theirs usually come down to one of three things: they're using a different income figure, they're calculating credit card minimums at 3 percent instead of the statement minimum, or they're including an obligation you didn't know counted. All three are fixable once you identify which one it is. Keep a copy of your worksheet and all supporting documentation for at least two years. Circumstances change, and having a baseline makes it much easier to explain variations during a later application.