
How Debt Verification Actually Works in Practice
Most people send a debt verification letter and then wait 30 days for a response, assuming the process is straightforward. It's not. I've watched collectors throw everything at a file except what you actually asked for. Here's what the process looks like when you're sitting on the other side. A debt verification letter is a written request sent to a collector asking them to prove, in writing, that the debt you owe is valid. Under the Fair Debt Collection Practices Act, you have 30 days from their first contact to send this request. Once they receive it, they must stop all collection activity until they mail you verification. That's the rule. The reality is messier.
Where to Find a Debt Verification Letter Template
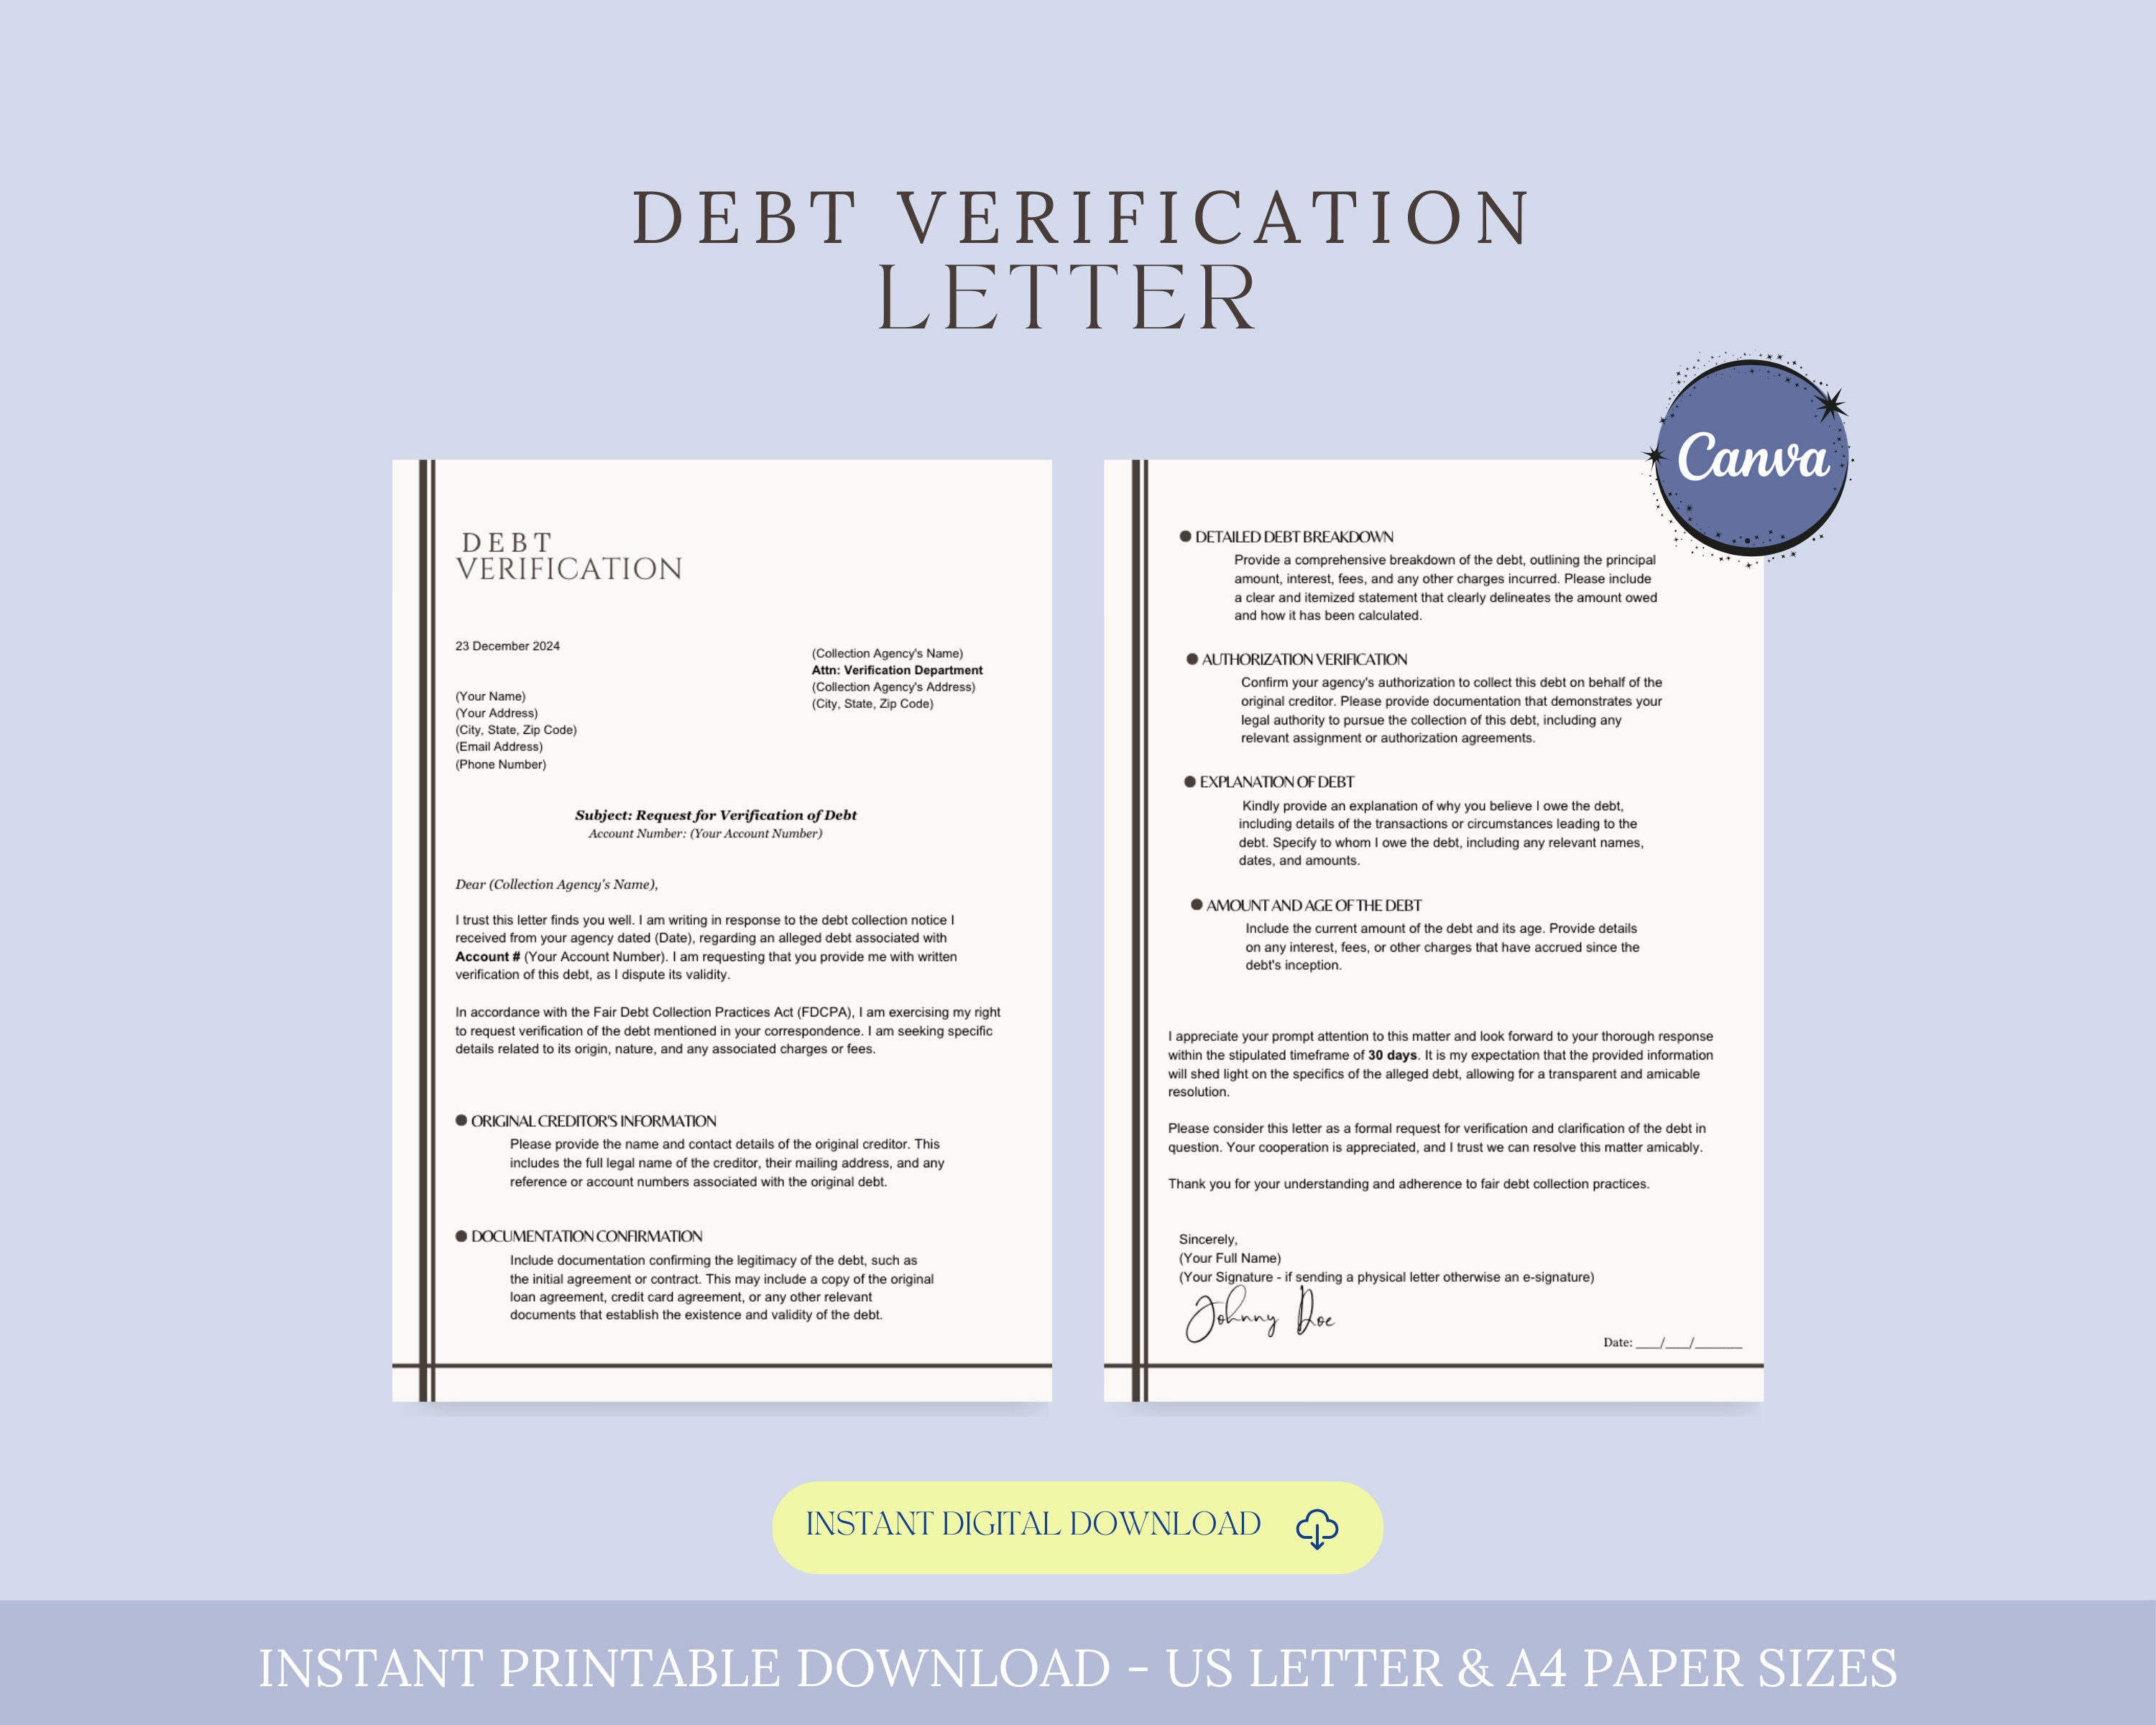
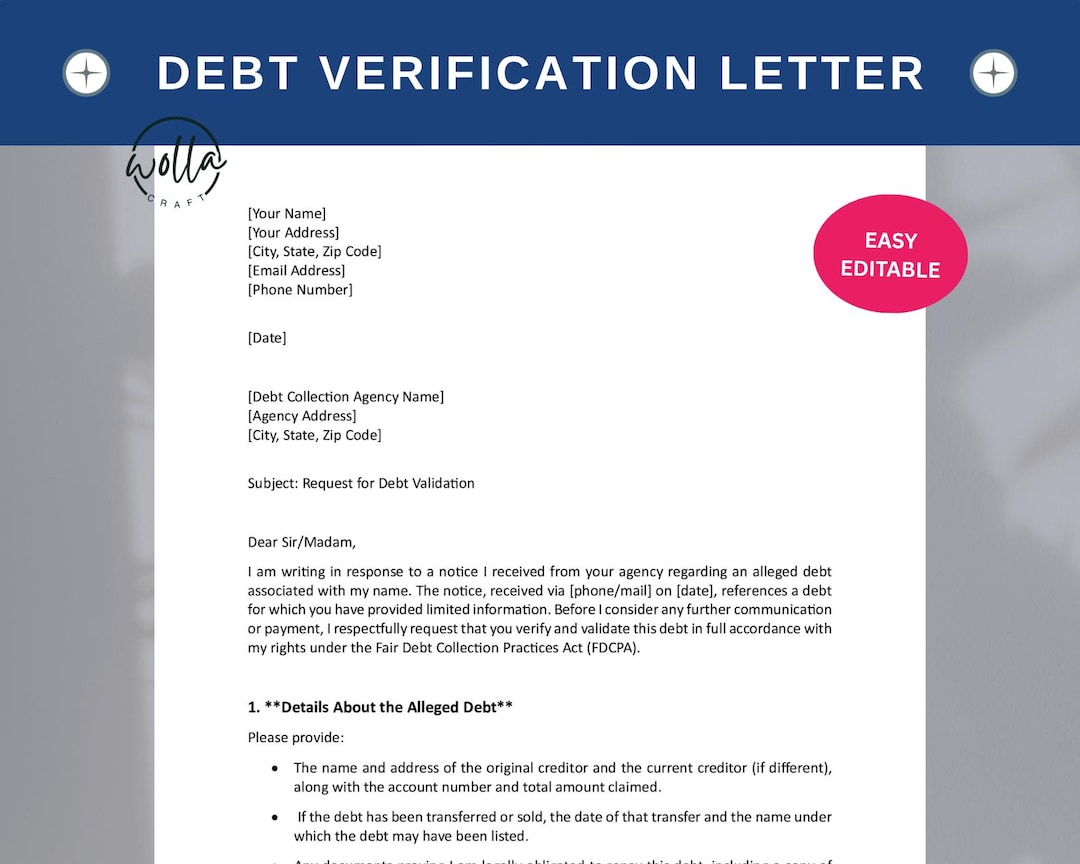
You don't need to pay for one. Consumer Financial Protection Bureau, Federal Trade Commission, and several consumer law nonprofits all publish free templates online. The trick isn't finding a template — it's using it correctly. Most people fill in their name and the debt amount and hit send. That's where things go wrong. Here's what I'd put in the letter instead of just copying a template blindly: Your full name and address. The collector's name and address exactly as it appears on their last correspondence. The date. A statement that you're disputing the debt and requesting verification under FDCPA Section 809(b). The amount they claim you owe. A request that they provide the name and address of the original creditor if it differs from the current holder. Your signature. Keep it under a page. Anything longer just gives them more to work around.
The Edge Case I Ran Into
Two years ago I was helping someone handle a medical debt that had been sold to a collection agency three separate times. The debt showed up on her credit report with three different account numbers, three different collectors, and three different balances. She sent one verification letter to the most recent collector. They sent back a photocopy of the original charge-off statement from the hospital — not even the right hospital. The name on the document didn't match hers. Here's what I did: I had her send a separate certified letter to every single collector on record, each one referencing the specific account number and balance for that collector. I also wrote a dispute to each of the three credit reporting bureaus naming the exact account numbers. Within 45 days, two of the three entries dropped off because the collectors couldn't produce matching documentation. The third stayed because the collector finally produced a properly assigned chain of custody. That one took another six months and a formal complaint to the CFPB before it moved. The lesson wasn't that the template was wrong. It was that the template assumes one debt, one collector, one account number. Real life rarely works that way.
Get the Full Details
Counter-Intuitive Things That Aren't Common Knowledge
Sending the letter via certified mail with return receipt requested isn't optional if you want legal protection. If you email it, text it, or use a collector's online portal, you may not trigger the 30-day response window. The FDCPA says the request must be "made in writing." Certified mail creates a paper trail. Without it, you're arguing against their word and theirs always wins in a dispute. A validation letter doesn't automatically remove the debt from your credit report. It stops collection activity and forces the collector to verify. If they verify it, the collection entry stays. If they can't verify it, the entry should be deleted — but only if the credit bureau agrees. You still need to dispute with the bureau separately. These are two different processes that rarely talk to each other.
What the Letter Can't Do
It can't stop a lawsuit. If the statute of limitations hasn't run out and the collector has already filed suit, sending a verification letter won't dismiss the case. It also won't reset the statute of limitations in every state, but in some states even acknowledging a debt in writing can restart the clock. Check your state's laws before you send anything. It doesn't work well against original creditors. The FDCPA covers third-party collectors, not the company you originally borrowed from. If the hospital or bank is still collecting its own debt, this letter has no legal force behind it. You'd be writing to someone who doesn't have the same compliance infrastructure. Most templates also don't include a request for the debt's age. That matters because some debts are time-barred but collectors still try to collect them. If you don't ask them to confirm when the debt originated, you might end up paying something you legally don't have to.
A Practical Walkthrough
Step one: pull your credit reports from all three bureaus. Write down every account number, every collector name, every reported balance. One spreadsheet. Step two: find the collector's address on their last letter or voicemail greeting. Not their website address — the physical address they use for correspondence. Step three: draft the letter. Keep it under 300 words. Include the account number, the disputed amount, and a clear request for validation under FDCPA Section 809(b). Step four: send it certified mail, return receipt requested. Step five: document the delivery date. Step six: wait 30 days. If they don't respond, you have grounds to escalate to the CFPB or your state attorney general's office. If they send verification, read it carefully. Check the name, the amount, the original creditor. If anything is wrong, send a second letter pointing out the discrepancies and demand corrected documentation. Collectors will often resolve minor errors quickly because it costs them nothing and avoids a formal complaint.
When It Fails Completely
Some collectors ignore verification letters entirely. They don't care about the FDCPA. In those cases the letter is still useful because it creates a paper trail for your eventual complaint or lawsuit, but it won't change their behavior. If you've sent three letters over 90 days with no response, your next move is either filing a complaint with the CFPB or consulting a consumer law attorney. Individual litigation costs money. Class action complaints are free but slow. There's no good option here, just different degrees of frustration. Another failure mode: debts that are already too old. If the statute of limitations has expired in your state, the collector can still validate the debt, but you likely have an affirmative defense if they sue. In that scenario, a verification letter is less useful than a cease-and-desist letter combined with legal advice. One doesn't replace the other.


