The formula you memorized doesn't quite work the way your textbook says
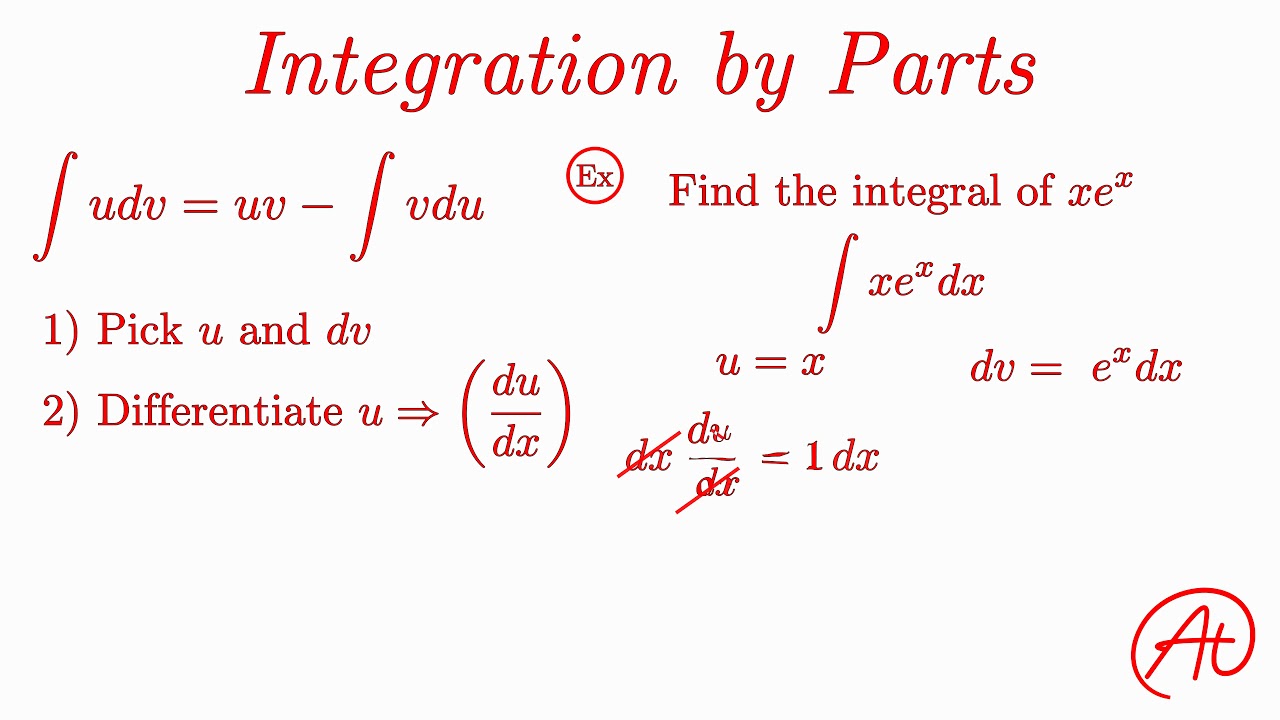
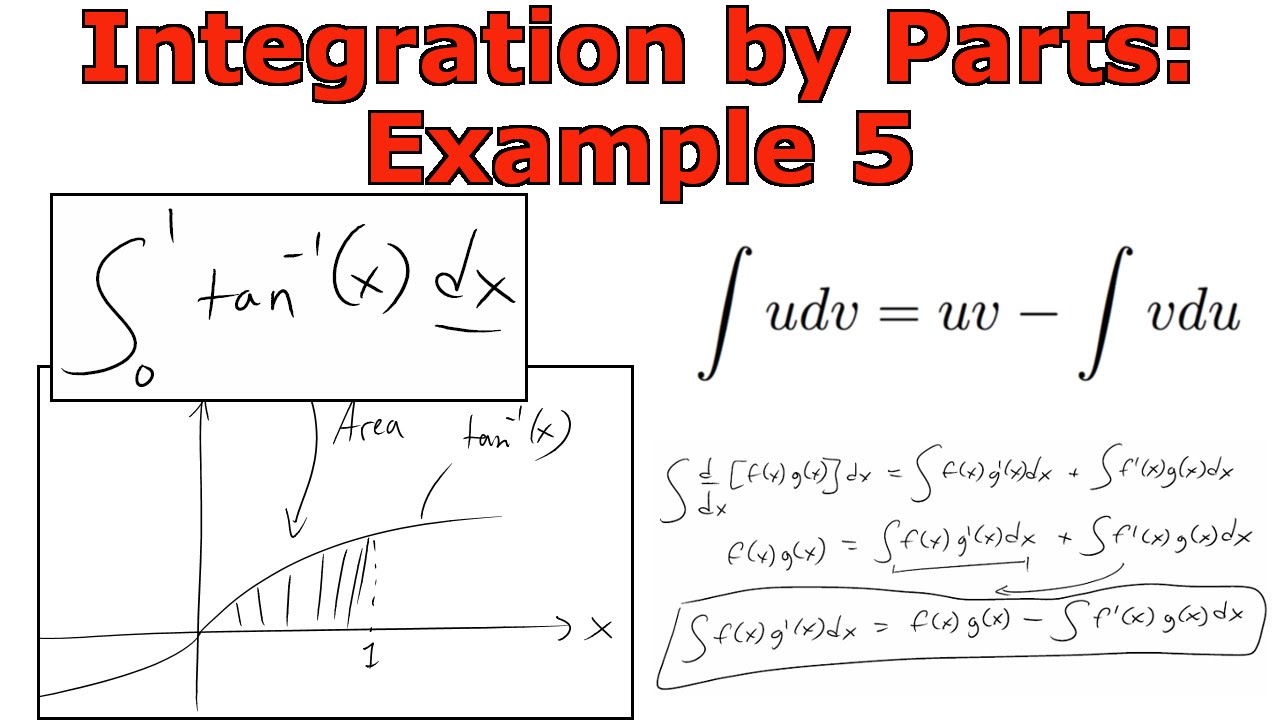
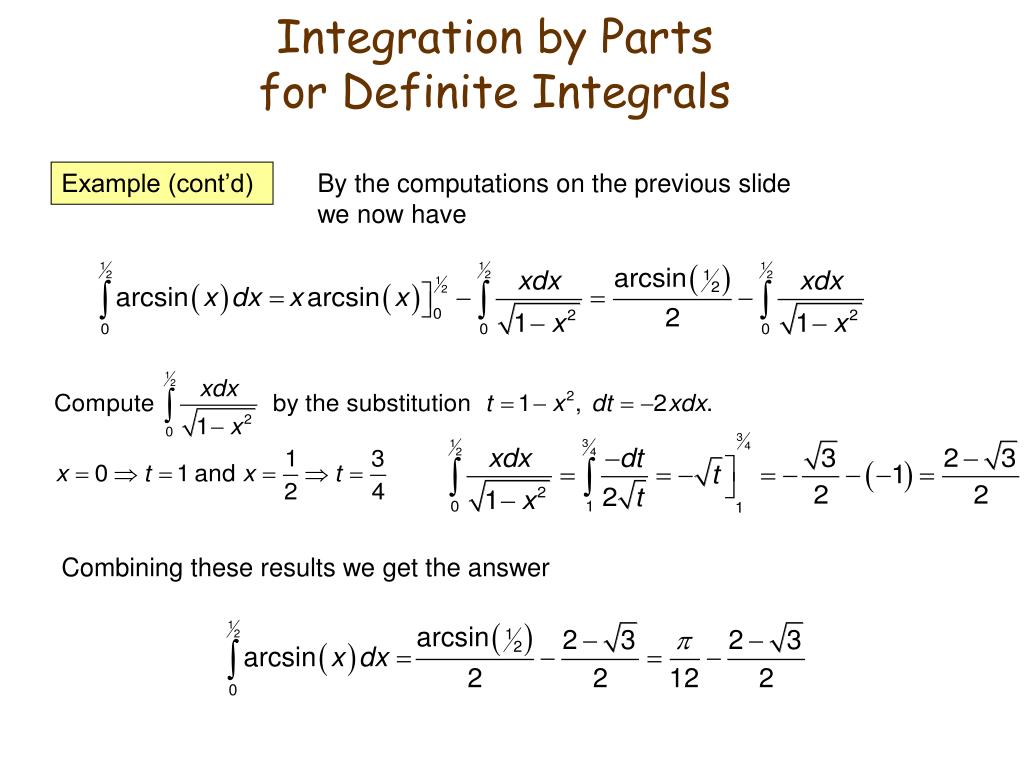
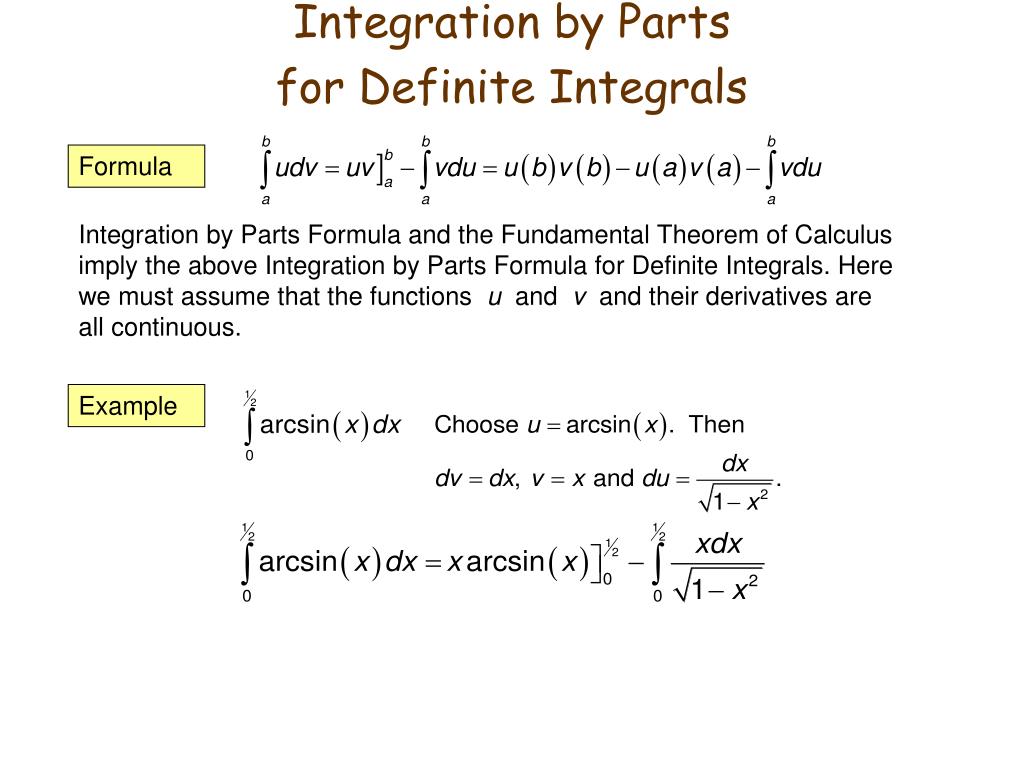
When you first learn integration by parts, the standard presentation shows it as a standalone trick. It isn't. It's just the product rule backwards, applied with bounds already in place. The definite version follows directly from the indefinite case, but skipping straight to the definite form without understanding the boundary term is how most students lose points on exams and waste time on homework. The formula is straightforward enough that I won't belabor it, but the way it's usually written in textbooks hides a practical complication. Here it is in the clean form: (a to b) u dv = [u(v)] from a to b (a to b) v du
Or in the more common notation you'll see on a formula sheet: u · dv/dx dx = [u · v] v · du/dx dx The boundary term [u·v] is where people go wrong. They evaluate it mechanically and move on. The real work is in choosing u and dv correctly before you even think about plugging in numbers. Pick poorly and you've just made the integral harder instead of easier. Pick well and the second integral often vanishes or simplifies to something trivial.
I remember working through a problem back in my grad years — something like ¹ x²e^(x) dx — that looked routine on paper. The standard LIATE rule told me to pick u = x² and dv = e^(x)dx. That works. Two rounds of by-parts and you're done. But then I ran into the same integrand with a twist: ^ x²e^(x) dx, the improper version. The boundary term at infinity doesn't vanish the way you might assume without checking. I evaluated [x²e^(x)] from 0 to and got zero at both ends, which felt too easy. Then I tried a slightly different variant where the exponential had a coefficient, and the upper bound didn't cleanly disappear. I ended up using L'Hôpital's rule twice on the limit to verify that the boundary term actually went to zero. It did, but barely. That experience taught me to always check improper bounds explicitly before declaring the boundary term dead. Here's a practical note that most courses skip. When you apply by parts to a definite integral, you don't need to reintroduce a constant of integration. The boundary evaluation handles everything. If you find yourself writing "+ C" inside a definite integral setup, stop and reconsider what you're doing. The reduction formula angle is where this gets useful in practice. Take integrals of the form xe dx or xsin(x) dx. Each application of by parts drops the power of x by one. You can set up a recurrence relation rather than computing each case from scratch. For ¹ x(1x) dx, applying by parts gives you a relationship between the n case and the (n1) case. That's not just elegant — it's how you evaluate things like ¹ x³(1x)³ dx without expanding the polynomial and integrating term by term.
Get the Full Details
There's a specific trap with trigonometric products that catches people regularly. Consider ^(/2) sin²(x) dx. You can use by parts with u = sin(x) and dv = sin(x)dx. After one round you get sin(x)cos(x) evaluated at the bounds plus ^(/2) cos²(x) dx. At this point you might think you've gone in a circle. You haven't. Use the identity sin²(x) + cos²(x) = 1 to combine the two integrals and solve algebraically for the answer. The result is /4. This self-referential pattern shows up often enough that recognizing it saves you from restarting the problem incorrectly. Another thing worth noting: tabular by parts works fine for definite integrals, but you have to be careful about when you evaluate the boundary term. The tabular method is just repeated by parts laid out in a grid. The diagonal products give you the integral terms, and the boundary term comes from the top-left product evaluated at both limits. Students often forget to apply the bounds to the boundary product and only apply them to the remaining integral. The correct approach evaluates [u·v u'·v + u''·v ...] at both limits as a single operation before subtracting. The method has clear limitations. By parts doesn't help with integrals like e^(x²) dx or sin(x)/x dx — no choice of u and dv makes those any simpler. Those require special functions or numerical approaches. By parts also struggles when the resulting integral is genuinely harder than the original, which happens frequently with logarithmic functions paired against certain rational expressions. In those cases, substitution or partial fractions is the right call, and sticking with by parts just wastes time.
For computational work, if you're evaluating a large batch of definite integrals that all share the same structure, setting up the reduction formula once and coding it as a loop is dramatically faster than re-deriving each case. I've seen this cut evaluation time from hours down to minutes for parametric families of integrals in numerical analysis projects. The core takeaway is that definite integration by parts is reliable when you know what you're dealing with, and it's unreliable when you're guessing. Check your boundary terms, especially at infinity or at singularities. Verify that each application actually simplifies the problem. And if you find yourself going in circles after two rounds, you've probably picked the wrong split on the first pass.