The Mechanics of Notes Payable Before the Textbook Definitions Hit
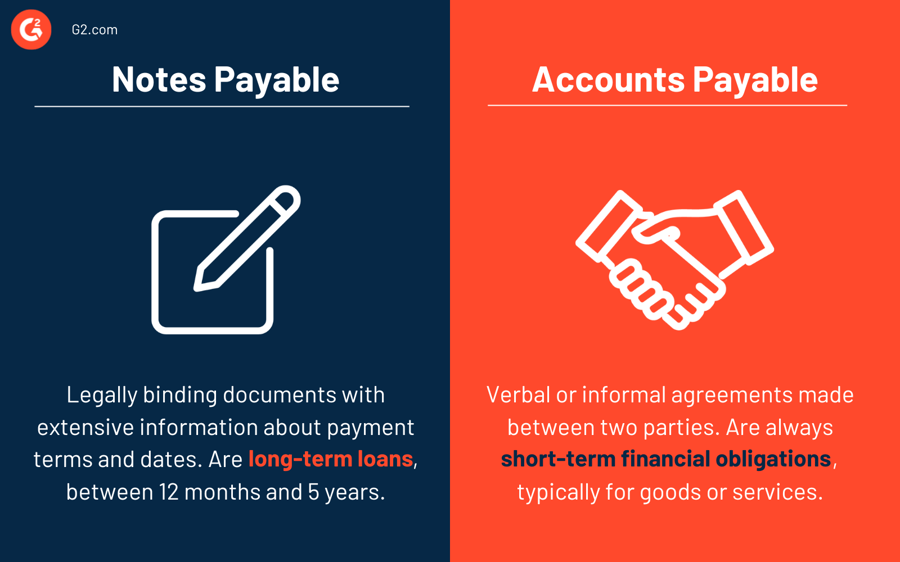
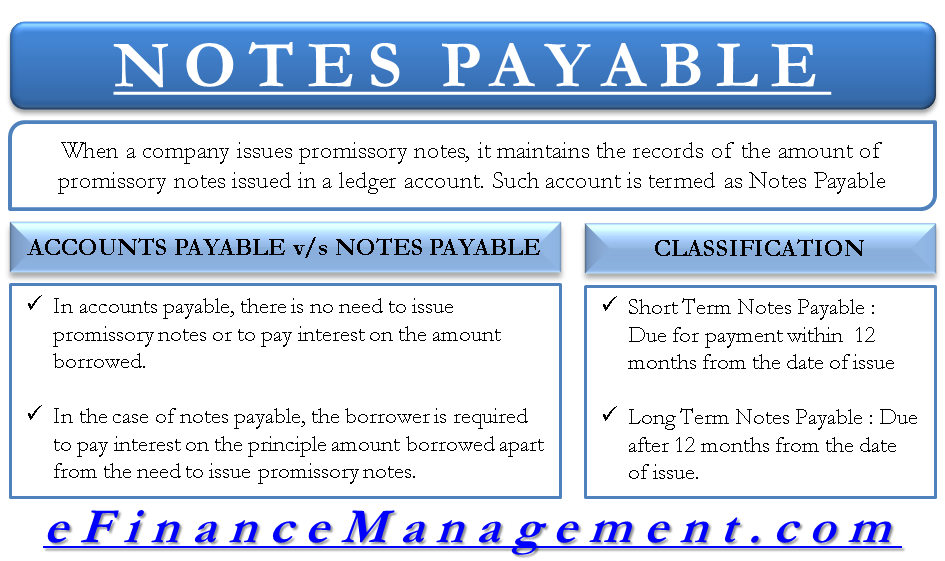
A note payable is a written promise to pay a specific amount of money, usually with interest, at a defined future date. It's more formal than an account payable. You sign it. You get a promissory note. The lender can take you to court over it much faster than they can over an unpaid invoice because the paper itself serves as evidence of the debt. That distinction matters when you're categorizing liabilities on a balance sheet and someone asks why your short-term obligations look different from last quarter. The textbook definition tends to stop there. In practice, a note payable shows up whenever a business borrows money through a formal instrument rather than a trade arrangement. This includes bank term loans, promissory notes issued to suppliers for extended payment terms, and convertible notes that carry equity features. Each one gets treated slightly differently in the books, and mixing them up creates reconciliation headaches that will eat an entire afternoon.
Definition Of Notes Payable In Accounting And What Nobody Warns You About
I've seen junior accountants treat every note the same way, which works fine until you hit a discounted note or one with an imputed interest rate. Here's the edge case that cost me two days last year: a supplier agreed to extend payment terms on a fifty-thousand-dollar equipment purchase, but instead of a standard zero-percent interest arrangement, the note was issued at a discount. The face value was fifty thousand, but the company received only forty-seven thousand in cash upfront. The difference got buried in AP because nobody flagged it as a financing activity rather than a purchase transaction. The workaround was straightforward once I caught it. I pulled the original promissory note, recalculated the effective interest using the discount amortization schedule, and reclassified the entry. The note should have been recorded at its present value with the discount amortized over the life of the loan. Fixing it required backing out the original journal entry, recording the note at the discounted amount, and setting up an amortization table for the remaining three payments. Took about forty-five minutes once the pattern was clear. The deeper issue most people miss is that not all interest-bearing notes generate interest expense in the periods you expect. If a note is issued at a discount or premium, the effective interest method requires you to recognize interest based on the carrying amount rather than the face value. This means your interest expense line will drift from what the coupon rate suggests. I've had controllers question why the P&L didn't match the payment schedule. It doesn't, and that's correct under GAAP.
Another thing that trips people up involves notes payable to related parties. When a parent company lends to a subsidiary at below-market rates, the imputed interest calculation isn't optional. You have to use the applicable federal rate or the incremental borrowing rate to figure out what the interest should be. Skip it and your financial statements look casual to auditors who know where to look. The adjustment usually shows up as a deemed dividend or capital contribution depending on the jurisdiction and relationship structure.
Get the Full Details

How To Record A Note Payable Step By Step
When you receive cash from a bank loan, the initial entry is simple. Debit cash for the amount received. Credit notes payable for the face value if the note is issued at par. If there's a discount or premium, credit notes payable for the face value and use a separate contra or adjunct account for the difference. Here's what that looks like in a real scenario. A company borrows one hundred thousand dollars from a bank at seven percent annual interest for two years. The note is issued at par. The entry on receipt date is a debit to cash for one hundred thousand and a credit to notes payable for one hundred thousand. Each period end, you accrue interest. Debit interest expense and credit interest payable. When the payment hits, debit interest payable and notes payable for the principal portion, and credit cash for the total amount paid. The trickier scenario involves installment notes where each payment covers both principal and interest. You need an amortization schedule before you record anything. Without one, you'll misstate the principal reduction each period and your notes payable balance won't reconcile to the lender's statement. I build mine in Excel with columns for payment date, beginning balance, total payment, interest portion, principal portion, and ending balance. The interest portion uses the effective rate times the beginning balance. The principal portion is the payment minus interest. The ending balance becomes the next period's beginning balance. This takes about ten minutes per note and saves roughly three hours of reconciliation work later.
Classification And Presentation On The Balance Sheet
Notes payable split between current and non-current based on when the next principal payment is due. Anything due within twelve months from the balance sheet date goes to current liabilities. The rest stays non-current. This sounds mechanical but causes errors constantly because people forget to reclassify the portion of long-term debt that matures within the next year. At each reporting date, you need to move that slice from long-term to current. The adjusting entry is a debit to long-term notes payable and a credit to current notes payable or short-term borrowings depending on your chart of accounts. Near the maturity date of a long-term note, the entire remaining balance migrates to current liabilities. Even if the note was originally structured as a five-year loan, six months before it comes due, every dollar of remaining principal sits in the current section. This is required regardless of whether the company intends to refinance. If you plan to refinance and can demonstrate the ability to do so through a binding agreement before the financial statements are issued, you can keep it long-term. Otherwise, it's current. This rule exists specifically to prevent companies from hiding near-term obligations in long-term debt to make their liquidity ratios look better.
Disclosure Requirements And Common Mistakes
Financial statements require footnote disclosures for notes payable that most small-business bookkeepers ignore. You need to disclose the interest rates, maturity dates, collateral pledged, and any covenants attached to the notes. If you have multiple notes, a summary table with carrying amounts by maturity year is standard practice. Missing these disclosures won't break your trial balance, but it will raise eyebrows during an audit and could result in a qualification if the omissions are material. The most common mistake I encounter is failing to track covenants. A note might require the company to maintain a minimum current ratio or limit additional debt beyond a certain threshold. When you miss a covenant breach, the entire note becomes callable. The lender doesn't have to wait until maturity to demand repayment. I once worked with a company that violated a debt service coverage ratio covenant without realizing it because they hadn't been recalculating their DSCR after a revenue dip. The note was classified as non-current when it should have been current. We caught it during quarterly review and restated the balance sheet before anyone else noticed. The fix was clean because the bank had already been notified of the breach and had agreed to a waiver, but the waiver document had to be obtained before the financial statements could reflect the correct classification. Another frequent error involves notes payable with variable interest rates. Companies often record interest at the current rate and never adjust it when the benchmark changes. The entry should reflect the rate in effect during each accrual period. If your note is tied to SOFR or a prime rate, you need a mechanism to track rate changes and adjust your accruals accordingly. Manual tracking works for a handful of notes. Once you cross into double digits, you need automated rate update routines or you'll fall behind within a reporting cycle.

When Notes Payable Get Complicated
Convertible notes deserve special attention because they straddle the line between debt and equity. Under ASC 470-20, you need to evaluate whether there's a beneficial conversion feature that requires separate accounting treatment. If the conversion price is below the stock price at issuance, part of the proceeds may need to be allocated to equity. This creates a discount on the debt that gets amortized as interest expense over the note's life. The journal entries are more involved than a standard note, and getting them wrong affects both your balance sheet and your diluted earnings per share calculation. Installment notes with balloon payments create another classification puzzle. If the final payment is due well beyond twelve months but interim payments require liquidity management, you need to show the upcoming principal portions as current even though the bulk of the debt is long-term. I recommend maintaining a detailed maturity schedule that breaks down principal payments by fiscal period rather than just by year. This makes it easier to populate the current versus non-current split at each reporting date without manual recalculations. Foreign currency notes payable introduce exchange gain and loss considerations. If your note is denominated in a currency other than your functional currency, you revalue the liability at each balance sheet date using the spot rate. The difference between the carrying amount and the revalued amount flows through income as a foreign exchange gain or loss. This can create volatility in your P&L that has nothing to do with operations. I've seen this blow up a quarterly earnings report when a strengthening dollar turned a manageable note into a six-figure unrealized loss. The hedge accounting election is available but comes with documentation requirements that many companies skip, leaving them exposed.
Practical Tools And Shortcuts That Actually Help
Most accounting software has a notes payable module, but they're inconsistently implemented. QuickBooks handles basic installment notes reasonably well, but amortization schedules for discounted notes often require manual setup. Xero lacks native notes payable tracking entirely, which means you're maintaining schedules outside the system and reconciling against bank statements monthly. NetSuite handles it comprehensively but requires configuration that smaller teams don't always have time for. For businesses with moderate complexity, a well-structured Excel template beats any off-the-shelf module. I use a master sheet that links to a payment schedule, an amortization table, and a covenant compliance tracker. The master sheet pulls data from the schedule using simple formulas, so when a payment is made, everything updates automatically. This takes about twenty minutes to set up for a new note and then requires minimal maintenance. The time savings become obvious during month-end close when other teams are still manually calculating accruals. There's no shortcut for understanding the underlying mechanics. Software can record entries, but it can't tell you when a covenant is at risk or why a note should be reclassified. Those decisions require judgment based on the terms of the agreement and the company's financial position. The people who get promoted in this field are the ones who understand both the bookkeeping and the business logic behind it.