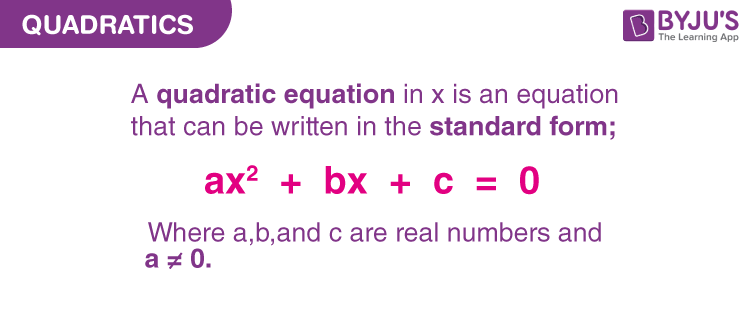
Where We Actually Start
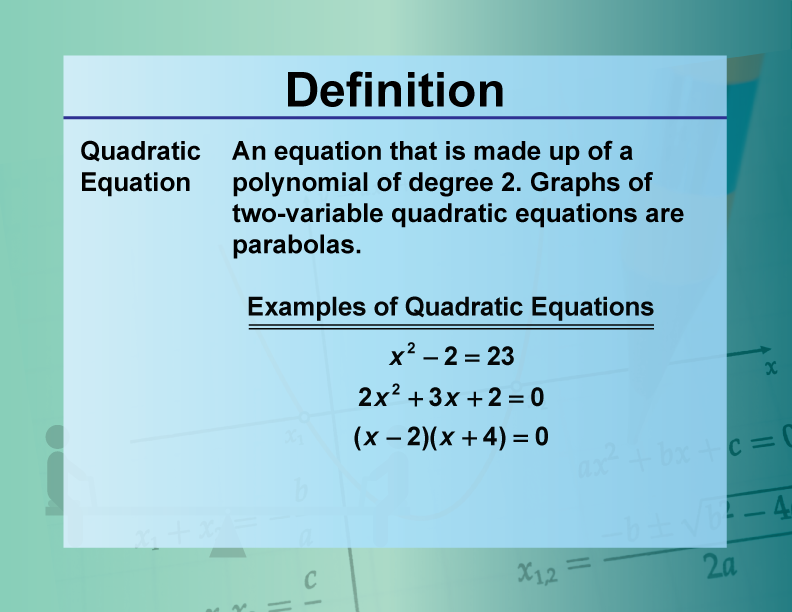
The definition of quadratic equation in math is straightforward enough that most people gloss over what it actually means when they see one in the wild. It is any polynomial equation where the highest power of the variable is exactly two. The standard form looks like ax² + bx + c = 0, where a, b, and c are constants and a is not zero. That last bit matters because if a equals zero, the whole thing collapses into a linear equation and you have been looking at a completely different problem the entire time. I ran into this exact issue last year while working through a structural engineering problem involving parabolic cable tension distribution. Someone had derived what they claimed was a quadratic relationship, but after simplifying terms, the coefficient on the squared term canceled out to zero. The equation was not quadratic at all. I caught it because I always check whether the leading coefficient survives after combining like terms before I apply any quadratic-specific method. If you skip that verification step, you end up dividing by zero or applying the wrong tool to the problem.
Definition Of Quadratic Equation In Math
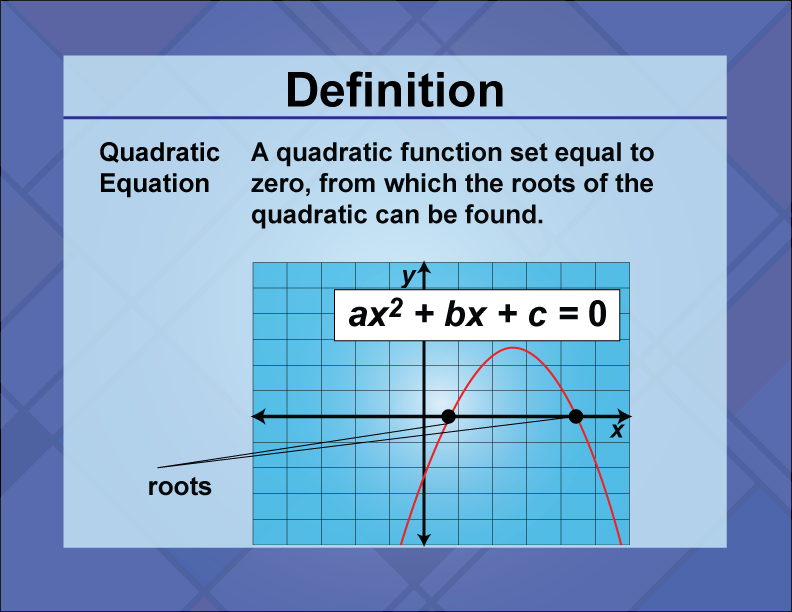
Formally, the Definition Of Quadratic Equation In Math specifies a second-degree polynomial set equal to zero. The variable appears with an exponent of two as the maximum degree, and the equation describes a parabola when graphed. The solutions to the equation correspond to the x-intercepts of that parabola, which means a quadratic can have two distinct real roots, one repeated real root, or two complex conjugate roots depending on the discriminant. The discriminant is b² - 4ac. You compute it once and it tells you everything you need to know about the nature of the roots before you spend time solving anything. A positive discriminant means two real roots. Zero means one real root with multiplicity two. Negative means complex roots. I use the discriminant first in almost every case because it saves me from running the quadratic formula on problems where completing the square or simple factoring would be faster. Here is something most introductory courses do not emphasize enough. The quadratic formula itself, x = (-b ± (b² - 4ac)) / (2a), is derived by completing the square on the general form. It is not a standalone trick. Understanding the derivation gives you the ability to reconstruct it when you cannot remember it under pressure and it also makes it obvious why the ± symbol exists in the first place.
How To Solve One Without Second-Guessing Yourself
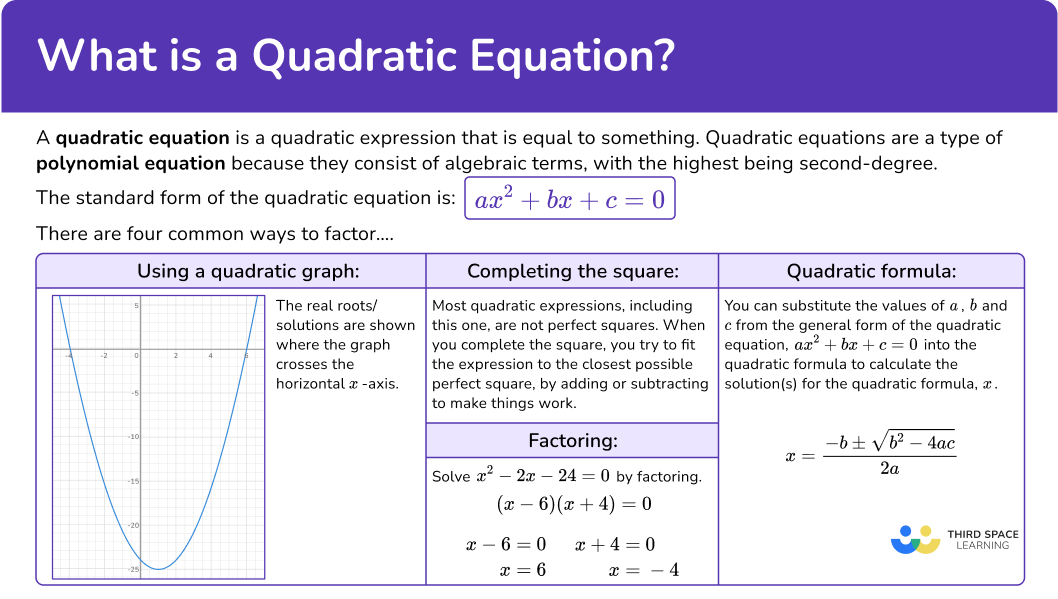
The three main methods are factoring, completing the square, and using the quadratic formula. Factoring works when the equation breaks cleanly into two binomials. Completing the square converts the equation into vertex form and reveals the axis of symmetry directly. The quadratic formula handles every case but can produce messy irrational numbers that require approximation. I typically attempt factoring first when the coefficients are small integers because it is nearly instantaneous if it works. When the leading coefficient is not one, I use the AC method. Multiply a and c together, find two numbers that multiply to that product and add to b, then rewrite the middle term and factor by grouping. This method works consistently and avoids the guess-and-check trap that wastes time on harder problems. Completing the square has practical value beyond just being another solution method. When I needed to analyze the vertex of a projectile motion problem for a robotics competition project, completing the square gave me the peak height and time-to-peak directly without computing the discriminant first. The vertex form y = a(x - h)² + k outputs h and k straight from the algebra. That saved me roughly twenty minutes of computation compared to finding roots and then back-substituting.
Get the Full Details
Problems With The Quadratic Formula Nobody Warns You About
Numerical cancellation is a real issue when you use the standard quadratic formula with floating-point arithmetic. If b is a large positive number and the discriminant is very close to b², then -b + (b² - 4ac) involves subtracting two nearly equal large numbers. The result loses significant digits and the computed root can be garbage. This is not theoretical. I hit it when working with regression coefficients from a financial model where the coefficients were on the order of ten thousand and the discriminant was within 0.01 of b². The workaround is the conjugate method. Compute the root that does not suffer cancellation using the standard formula, then get the other root by dividing c / (a × computed_root). This uses the fact that the product of the roots equals c/a. It restores precision without any additional complex algebra. Another valid approach is the alternative formula formulation where you multiply numerator and denominator by the conjugate expression. Both methods are well documented in numerical analysis literature, but they rarely appear in high school textbooks. Another limitation worth stating plainly. The quadratic formula assumes you are working over the real or complex numbers. It does not generalize cleanly to modular arithmetic without additional care. If you need to solve quadratics modulo a prime, you need a different framework involving Legendre symbols and square root extraction in finite fields. The quadratic formula itself is not wrong there, but the square root operation behaves differently and the division by 2a requires modular inverses that only exist under specific conditions.
Edge Cases That Break Routine Methods
When a equals zero, the equation is linear and the quadratic formula breaks because you are dividing by zero. This is why checking the leading coefficient first is non-negotiable. When both a and b equal zero, you either have a trivial identity or no solution depending on whether c is also zero. Another edge case appears when the discriminant is a perfect square in a rational coefficient equation. The roots are rational and factoring is usually faster. When the discriminant is positive but not a perfect square, the roots are irrational conjugates and you should leave them in exact radical form unless a numerical approximation is explicitly required. Rounding too early introduces error into any downstream calculation. I worked on a signal processing calibration task where a quadratic appeared in the frequency response equations. The discriminant was slightly negative due to measurement noise rather than the actual system physics. Treating it as a straightforward complex-root problem produced unstable feedback coefficients. The fix was to recognize that the negative discriminant was an artifact of measurement tolerance and constrain the problem to the nearest physical parameter range rather than accepting the complex roots at face value. This kind of judgment call does not come from memorizing definitions, it comes from seeing what happens when theory meets imperfect data.
Practical Tips That Actually Help
Always verify your solutions by substituting them back into the original equation. It catches sign errors and arithmetic mistakes that are extremely common during the substitution step. This typically takes about thirty seconds and prevents wasting an hour tracking down why a simulation output is nonsensical. When coefficients involve decimals or fractions, multiply through by the least common denominator first to work with integers. This reduces computational error and makes factoring attempts more reliable. I convert decimals to fractions mentally whenever possible because integer arithmetic is less prone to rounding drift in intermediate steps. If you are solving quadratics as part of a larger system of equations, substitution often leads to quadratic expressions. In those cases, solving the quadratic exactly and keeping radicals in symbolic form rather than approximating early preserves accuracy through the rest of the system. Numerical approximation at the quadratic stage compounds error through every subsequent substitution.