Getting a Position Delta Neutral
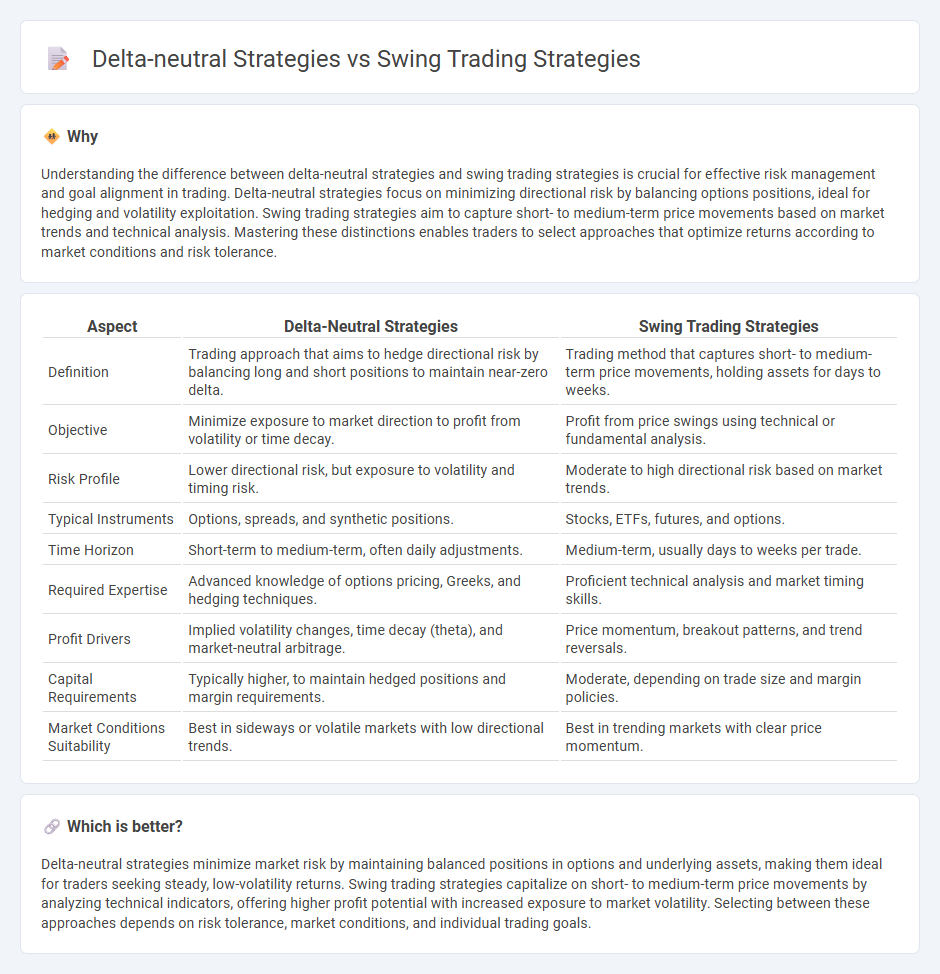
Delta neutral trading sounds more complicated than it usually is once you stop thinking about it as a strategy and start treating it like a mechanical process. The core idea is simple enough: you combine long and short option positions so the overall delta of your portfolio sits at or extremely close to zero. When delta is zero, small moves in the underlying asset don't matter to your P&L. You are insulated from direction. I spent about three years doing this actively before I mostly stepped back. The market environment shifted, the spreads got tighter, and the opportunity count dropped. But when it works, it works cleanly. When it doesn't, it doesn't.
Delta Neutral Option Trading Strategies
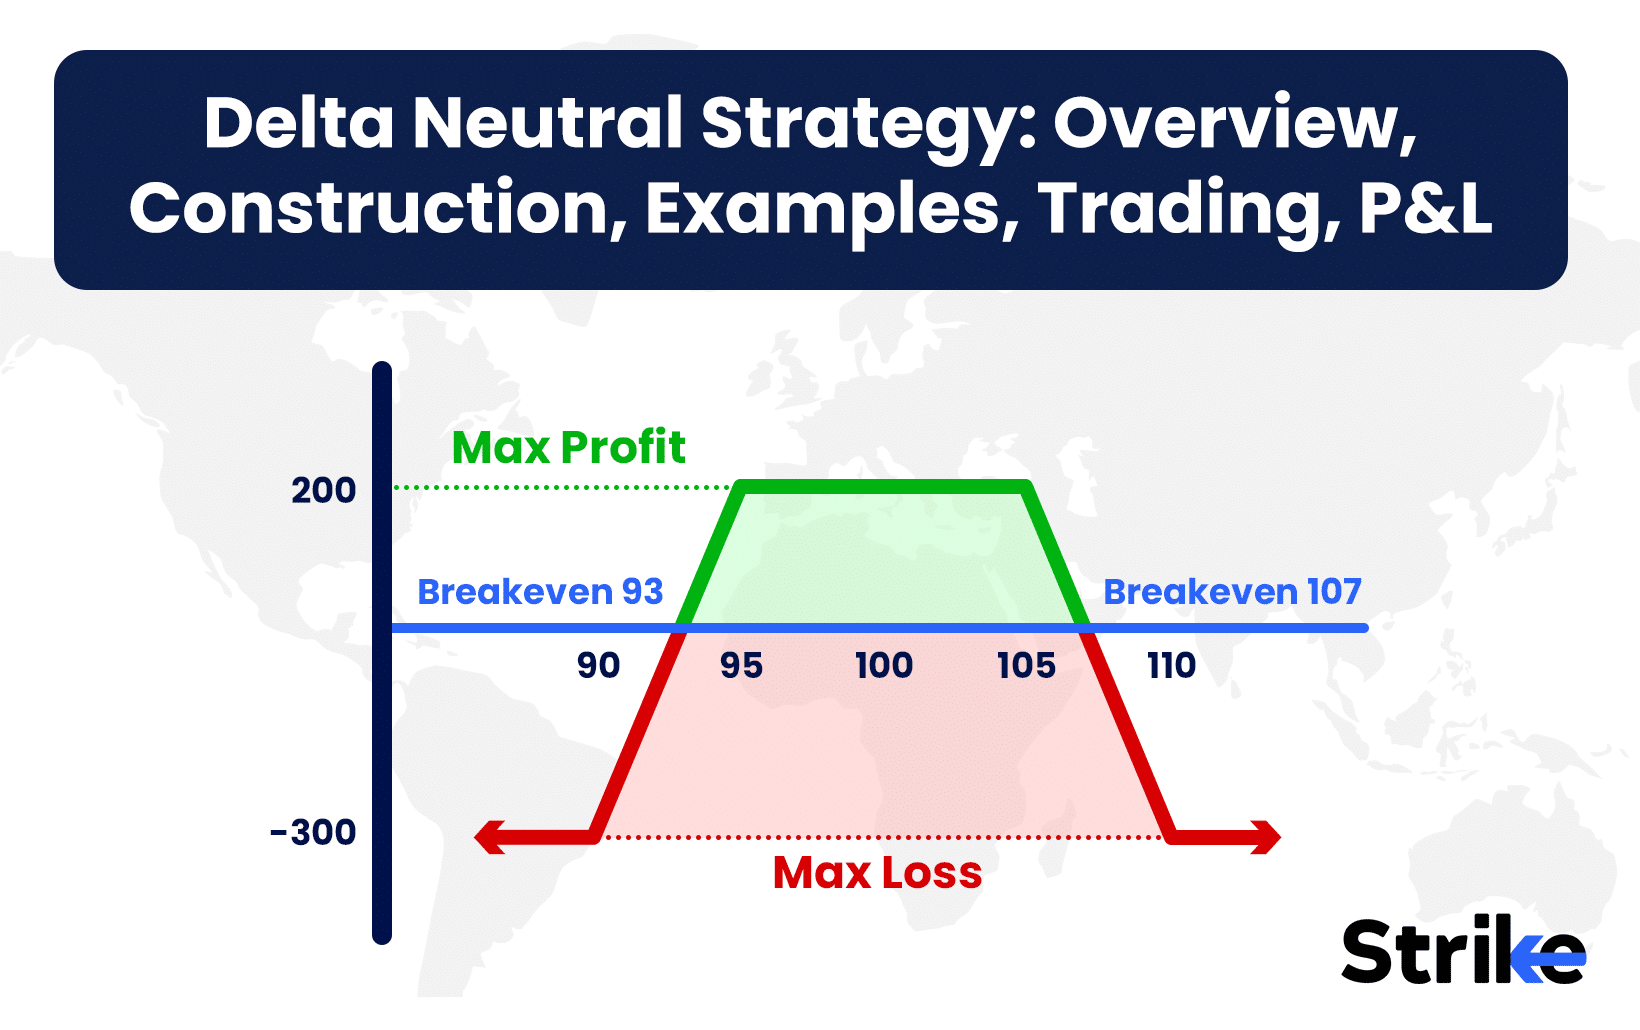
The most straightforward version is the iron condor. You sell an out-of-the-money call spread and an out-of-the-money put spread simultaneously. The deltas of the two legs offset each other. If the underlying drifts up, the put side gains delta while the call side loses it. You adjust by buying or selling the underlying to re-center. A second common approach is the calendar spread. Sell a near-term option and buy a longer-dated one with the same strike. The shorter option's delta decays faster, which creates a position that starts near delta neutral and can be managed as volatility shifts. This is less capital-intensive than the iron condor but requires closer monitoring of the term structure. Then there is the ratio spread. Sell one option and buy two of the same type at a different strike. It's asymmetric by design and only works well when you have a clear view on where the underlying should not go.
The math behind all of these is tracked through the Greeks. Delta measures directional exposure. Gamma measures how fast delta changes as the underlying moves. Theta measures time decay. Vega measures sensitivity to implied volatility. A position that is delta neutral today can become directionally biased tomorrow if gamma pushes delta away from zero faster than you can rebalance. That is the practical problem everyone runs into.
Get the Full Details

Setting Up and Managing the Position
Start by picking your underlying. High liquidity matters more than people admit. I used to trade this on SPX, QQQ, and individual names like AAPL and TSLA. SPX was cleaner because it settles cash and you can hold through expiration without assignment risk. Individual stocks introduce pin risk and early assignment on dividends, which complicates everything. Construct the position using options with similar implied volatilities on both sides. If the put side has noticeably higher IV than the call side, your delta neutral setup is already skewed. You think you are hedged. You are not. The market is telling you something about where flow is coming from. After the position is entered, monitor delta continuously. In practice, most traders use a threshold. If net delta moves past plus or minus five percent of the underlying's notional, you rebalance. Rebalancing means buying or selling shares to bring delta back to zero. You do this quickly. Every minute you sit with biased delta is a minute you are taking a directional bet you did not intend to make.
The real work is managing gamma risk. When the underlying approaches your short strikes, gamma accelerates. Delta shifts rapidly. You need to adjust more frequently, and the adjustments become more expensive because bid-ask spreads widen near expiration and near the money. This is where account size matters. A fifty-thousand-dollar account handles gamma differently than a five-hundred-thousand-dollar account. Smaller accounts get crushed by transaction costs during adjustment cycles. I also track vega exposure separately. A delta neutral position can still be heavily vega-long or vega-short. If you are vega-long and implied volatility collapses, you lose money even if the underlying does not move. Theta can offset this, but only partially. The relationship between theta and vega changes depending on time to expiration and moneyness. Near-term options have high theta but also high gamma. Longer-dated options have lower theta but more stable delta. Most traders pick the wrong balance.
A Specific Problem I Encountered
During the March volatility spike, I had an iron condor on SPX that was properly delta neutral entering the day. The market gapped down sharply in pre-market. By the time regular trading started, the put side was deep in the money and the call side was far out of the money. My delta had flipped to negative twenty-five. I needed to buy back call options to reduce exposure, but the bid-ask spread on those calls had widened to nearly four dollars per contract. Executing the hedge would have cost me more than the delta exposure itself was losing. My workaround was to use SPY futures instead of options for the hedge. Futures have no bid-ask spread issues on the order book and they provide pure directional exposure. I sold enough futures contracts to bring delta back to zero. This took about ninety seconds versus the three minutes it would have taken to work through the options chain. The futures hedge cost roughly twelve dollars in slippage compared to what the options hedge would have cost. Over the life of the position, that difference mattered. This is the kind of thing that does not show up in textbooks. Options markets break under stress. Futures markets tend to stay functional. When you are running delta neutral strategies, having a secondary vehicle ready is not optional.

What Beginners Miss
The first thing people get wrong is thinking delta neutral means risk free. It does not. It means you are not exposed to small moves in the underlying. Large moves, volatility expansion, and time decay all create risk. Gamma risk alone can wipe out a week of theta gains in a single session. Vega risk can turn a profitable position into a loser without the underlying moving a cent. The second thing people miss is transaction cost drag. Every adjustment costs money. If you are trading options with wide spreads, the cost of staying delta neutral can consume most of your expected profit. This is why SPX and index options are preferred over individual stock options by serious practitioners. The spreads are tight. The liquidity is consistent. The mechanics are cleaner. A third nuance is rollover behavior. When you roll a short option forward in time, you are not just extending duration. You are changing the delta profile, the gamma profile, and the vega exposure of the entire position. Rolling a short call forward usually increases delta on that side because the new option has higher delta at the same moneyness level. You then need to adjust the hedge again. This is a compounding problem that grows as expiration approaches.
When This Strategy Fails Completely
Delta neutral trading breaks down in two scenarios. The first is an event-driven gap. Earnings reports, FDA decisions, Federal Reserve announcements, or geopolitical events can cause the underlying to move five, ten, or fifteen percent in a single session. No amount of delta hedging protects you from gaps. You are simply exposed to the next opening price. Adjustments after the fact are expensive and often insufficient. The second scenario is persistent high implied volatility. If IV stays elevated for an extended period, the options you are selling carry rich premiums. That sounds good until you realize that high IV means the market expects large moves. Your short options get tested frequently. Theta decay slows down because the options lose value more slowly when volatility is high. Meanwhile, gamma risk increases. You end up adjusting constantly while making less money than you expected. This is why delta neutral strategies perform better in low-to-moderate IV environments. If you are dealing with one of these scenarios, the practical alternative is to reduce position size dramatically or switch to a different strategy entirely. Covered calls, cash-secured puts, or simple directional trades may offer better risk-adjusted returns in those conditions. Delta neutral is not a universal tool.
Practical Parameters
Most traders structure delta neutral positions with short strikes at plus or minus eight to twelve delta. This gives you a reasonable buffer before the short options approach the money. Tighter than eight delta and you collect less premium. Wider than twelve delta and you are exposed to gamma spikes too early. Time to expiration between thirty and forty-five days is the sweet spot for most iron condor and calendar spread traders. This range provides enough theta decay to generate profit while keeping gamma risk manageable. Anything shorter than twenty days and gamma becomes dangerous. Anything longer than sixty days and theta decay slows to a point where the trade needs a larger move to work in your favor. Adjustment thresholds vary by trader but a common range is plus or minus three to five delta on the overall position. Some traders adjust proactively before hitting the threshold. Others wait until the threshold is breached. Both approaches have merit. Proactive adjustment costs slightly more in transactions. Reactive adjustment risks larger losses from delayed responses.

Position sizing should never exceed five to ten percent of total portfolio value for a single delta neutral trade. These are high-management trades. Running multiple concurrent positions increases the chance of overlap in risk factors. If you hold three delta neutral positions on correlated underlyings, a single market event can stress all of them simultaneously. Correlation is a silent killer in portfolio construction. The mechanics of delta neutral trading are straightforward. The execution is where most people fail. Spreads, slippage, timing, correlation, and event risk all matter more than the theory suggests. Run the numbers carefully before entering. Have a plan for adjustments and exits. Accept that some periods will produce neutral results or small losses. The strategy is not a profit machine. It is a tool for managing a specific type of market environment.