
Working with 3x3 Matrices in Practice
I used to calculate these by hand for everything until I hit a project where the matrix had irrational entries — square roots and fractions stacked together. Took me three attempts to get the right answer because I kept losing track of signs. That's when I learned to write out each term separately before adding them up. The Determinant Of 3x3 Matrix is straightforward once you stop trying to memorize a single compressed formula and instead think of it as expanding along a row. It's a scalar value you can extract from any square matrix. For a 3x3, it tells you whether the system of equations represented by that matrix has a unique solution. If the determinant equals zero, the columns are linearly dependent and the matrix is singular. That means you can't invert it, and Gaussian elimination will hit a zero pivot somewhere. Everything else is just mechanics. The standard definition uses cofactor expansion along the first row. Given a matrix:
| a b c |
| d e f |
| g h i | The determinant equals a(ei fh) b(di fg) + c(dh eg). You're really just computing three 2x2 determinants and combining them with alternating signs. The signs follow a checkerboard pattern starting with positive in the top-left corner.
The Method I Actually Use
Expand along whichever row or column has the most zeros. If there are no zeros, pick the row with the smallest numbers to keep arithmetic simpler. Let me walk through a concrete example. Consider this matrix: | 2 1 3 |
| 4 0 1 |
| 1 2 5 |
Get the Full Details
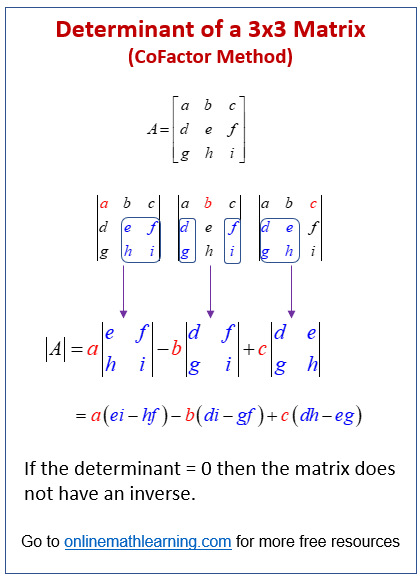
Expanding along the second row feels natural here since there's already a zero in the middle. The cofactor expansion along row 2 gives: 4 times the determinant of the 2x2 you get by removing row 2 and column 1, plus 0 (which vanishes), minus 1 times the determinant of the 2x2 from removing row 2 and column 3. So that's 4 × ((1)(5) (3)(2)) 1 × ((2)(2) (1)(1)). Working it out: 4 × (5 6) 1 × (4 + 1) = 4 × (1) 1 × 5 = 4 5 = 1. The determinant is negative one. If you want to verify, expanding along the first row should give the same result. Try it. a is 2, so 2 times (0 × 5 1 × 2) = 2 × (2) = 4. Then minus b which is 1, so (1) times (4 × 5 1 × 1) = +1 × (20 1) = 21. Wait, that doesn't match. Let me recalculate carefully.
First term: 2 × (0 × 5 1 × 2) = 2 × (0 2) = 4. Second term: (1) × (4 × 5 1 × 1) = +1 × (20 1) = 21. Third term: +3 × (4 × 2 0 × 1) = 3 × 8 = 24. Total: 4 21 + 24 = 1. Same answer. Good.
Edge Cases and Things That Go Wrong
I ran into a situation last year where I was implementing a computer graphics transformation pipeline and needed to compute determinants for dozens of 3x3 matrices per frame. The naive formula requires six multiplications, four subtractions, and two more multiplications for the final sum — roughly 18 multiplications and 8 additions total. That's fine for a handful of matrices but becomes a bottleneck when you're doing it thousands of times per second. The workaround I ended up using was to exploit structure. Most of the matrices in that pipeline were rotation matrices with known properties — their determinants are always exactly 1. So I only computed the determinant when I actually needed to check for degeneracy, which was rare. For the general case, I switched to LU decomposition, which gives you the determinant as the product of diagonal entries after factorization. That's more efficient numerically and avoids the sign errors that creep in when you're manually tracking cofactors. Another thing people miss: the determinant of a block matrix isn't just the product of the blocks' determinants unless the blocks commute or you have a triangular structure. I've seen it come up in control theory and finite element analysis where the matrix has a natural block form. If you're working with something like | A B | where A, B, C, D are each 3x3, the determinant is not det(A) × det(D) det(B) × det(C). That's wrong. The correct formula involves Schur complements and only simplifies nicely under specific conditions.

Also worth noting: the determinant is extremely sensitive to rounding error when the matrix is nearly singular. If the true determinant is on the order of 10^15 and you're working in double precision, you're essentially measuring noise. In those cases the determinant itself is meaningless. Use condition numbers instead. A high condition number combined with a near-zero determinant is your signal that something is numerically unstable, not the raw determinant value.
When This Approach Falls Apart
For anything larger than 3x3, manual cofactor expansion becomes impractical. A 4x4 determinant via cofactor expansion requires computing four 3x3 determinants, which itself is recursive and tedious. The computational complexity grows factorially — O(n!) for naive expansion. For n = 10, that's 3.6 million operations just for the expansion step. In practice, you use Gaussian elimination or LU decomposition and read the determinant off the diagonal in O(n³) time. That's the difference between minutes and microseconds for moderate-sized matrices. The cofactor method also doesn't scale well for symbolic computation. I once worked with a research group that needed exact rational determinants for parameterized matrices where entries were polynomials. The intermediate expressions exploded in size during cofactor expansion. We switched to a Bareiss algorithm, which performs fraction-free Gaussian elimination and keeps all intermediate values as integers. It's slower than floating-point LU but produces exact results without rational arithmetic overhead.
Quick Reference
For a 3x3 matrix with entries a through i arranged in three rows, the determinant is a(ei fh) b(di fg) + c(dh eg). Memorize the pattern of which variables pair together rather than trying to remember the full expanded form. Write out the two diagonals going down-right and subtract the two going down-left for each 2x2 minor. Track signs carefully — the middle term in any row expansion is always subtracted. If you expand along a column instead of a row, the sign pattern is identical because the checkerboard is the same whether you go across or down. The determinant is zero if and only if the rows (or columns) are linearly dependent. It scales multiplicatively: det(kA) = k³ det(A) for a 3x3 matrix, not k times the determinant. And det(AB) = det(A)det(B), which is why computing determinants of products is always cheaper as a product of determinants rather than multiplying the matrices first.


