Figuring Out What You Will Actually Pay Each Month
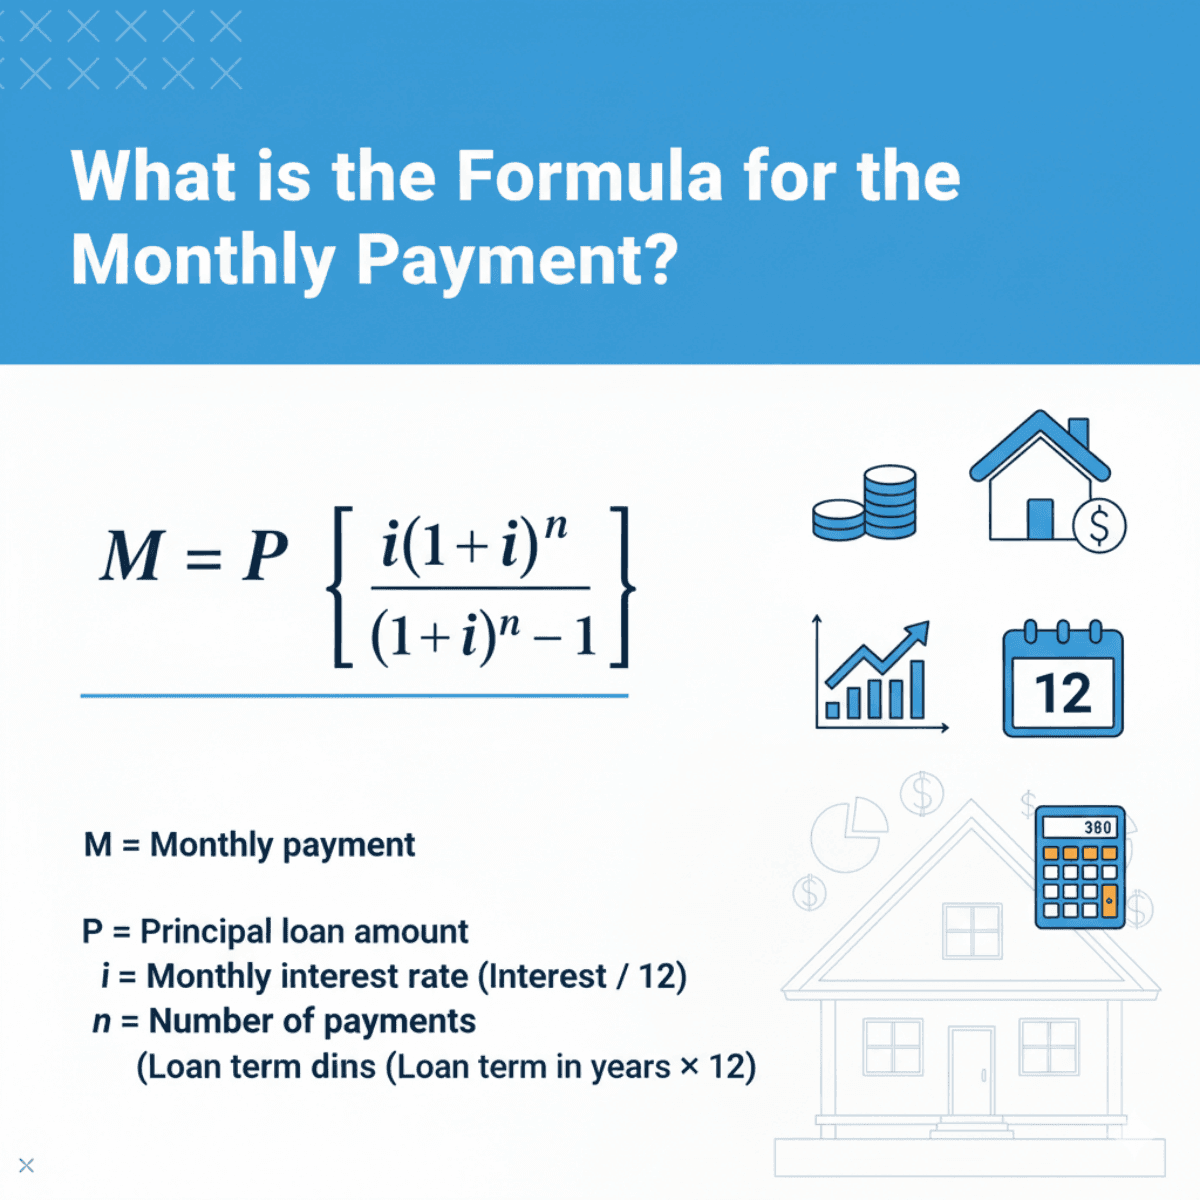
Most people who ask me how to determine mortgage payment are looking for a quick answer, but the reality is a bit more involved than just plugging numbers into an online calculator. I spent years working through loan estimates and payment schedules for clients, and the thing that always trips people up is not the formula itself, but understanding what goes into the final number and what does not. The core of it is the standard amortization formula, which looks like this: M = P [ i(1 + i)^n ] / [ (1 + i)^n – 1 ]. P is your principal loan amount, i is your monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments over the life of the loan. This gives you the principal and interest portion only. Everything else on your payment comes after. That breakdown matters because a lot of folks think the quote they see from a lender is their full monthly obligation, when in fact the principal and interest figure is usually only about 55 to 65 percent of what they actually send in each month. The rest is escrow, and that is where things get messier.
Escrow covers property taxes, homeowners insurance, and sometimes private mortgage insurance if you put down less than 20 percent. Lenders bundle all of that together into one payment called PITI, which stands for Principal, Interest, Taxes, and Insurance. If your property tax rate in your area is high, or your home is in a flood zone that requires additional coverage, your escrow portion can be significantly larger than average, and it can change year to year without much warning. I remember working with a client in Ohio who had been quoted a payment around $1,400 a month. When we went through the full calculation to properly determine mortgage payment including taxes and insurance, the actual number came out closer to $1,850. The gap was almost entirely property tax reassessment. The county had just done a reappraisal that bumped his assessed value by about 18 percent, and his lender had used the prior year's tax bill for the estimate. This is a common enough issue that I always tell people to ask for the actual current tax statement, not the previous year's figure, when they are running these numbers. Another thing people overlook is the difference between the note rate and the APR. The note rate is what you see advertised, but the APR folds in origination fees, discount points, and other closing costs into an annualized figure. Two loans with the same monthly payment can have very different AP Rs depending on the fees attached. If you are shopping around, do not get stuck comparing note rates alone, because they will mislead you on the true cost.
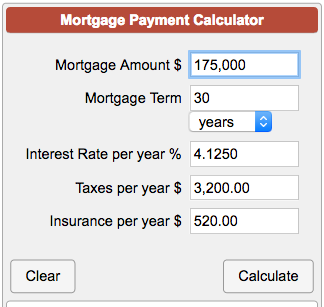
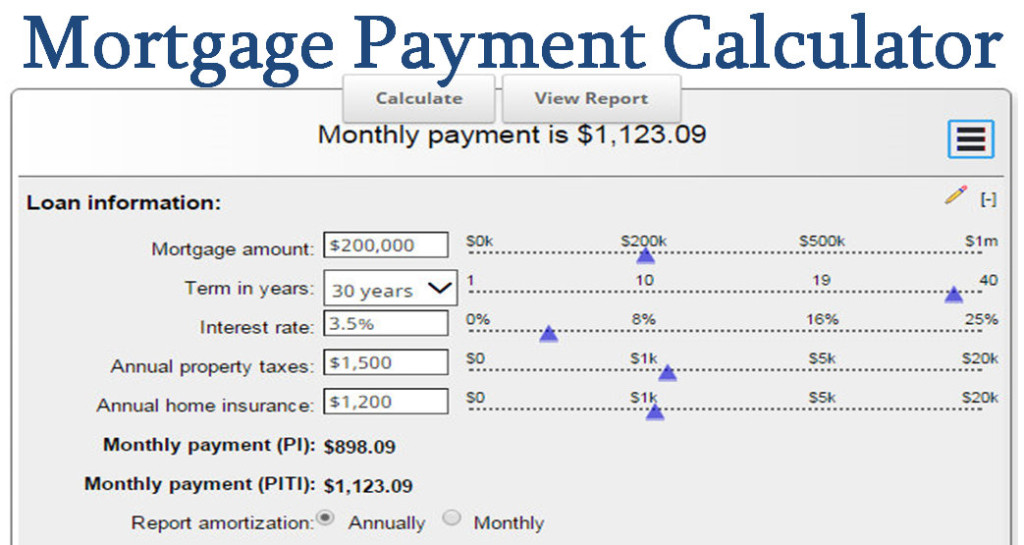
Here is a straightforward example. Say you are borrowing $350,000 at 6.5 percent annual interest for 30 years. Your monthly interest rate is 0.005417, and your total number of payments is 360. Plugging those into the formula gives you a principal and interest payment of roughly $2,212. That is your base. Then add property taxes, insurance, and PMI if applicable, and the total monthly payment could easily be somewhere between $2,500 and $2,800 depending on where the property is located. There are tools you can use to run these numbers yourself, and there are also spreadsheet templates that do the work for you. The advantage of building your own sheet or using a simple calculator is that you can adjust variables instantly, like testing what happens if your rate goes up half a point or if your escrow shortfall hits in year three. Most free calculators online only show the principal and interest portion, so you still have to manually add the escrow pieces, which is where the disconnect usually happens.
Get the Full Details
Where This Method Falls Apart
The amortization formula assumes a fixed-rate loan with a fully amortizing schedule. It does not handle adjustable-rate mortgages well without additional calculations, because the rate changes over time. If you are dealing with an ARM, you need to account for adjustment caps, margin rates, and index values, which complicates things considerably. For an ARM, the best approach is to model the payment at each adjustment period separately rather than relying on a single formula output. Interest-only loans are another edge case where the standard formula breaks down. During the interest-only period, your payment is simply the monthly interest on the principal, which is much lower than a fully amortizing payment. Then at the end of that period, the payment resets to a much higher amount because the principal never started being paid down. This is a trap a lot of buyers walk into without realizing it, and it is worth flagging early. The biggest limitation of relying on any calculator or formula is that none of them account for your personal financial situation. A payment might look affordable on paper, but if you have significant debt, variable income, or other irregular expenses, the number on the page does not reflect your actual capacity to pay. I always recommend running the payment through a debt-to-income analysis, which most lenders will do anyway during underwriting, but doing it yourself first saves time when you are pre-approaching multiple lenders.
If you want something more comprehensive than a basic online calculator, there are spreadsheets and loan modeling tools available that let you layer in escrow estimates, tax variations, and even different payoff scenarios. I tend to use a custom Excel template that pulls in current rate data and lets me adjust everything in real time. It takes maybe ten minutes to set up, and it pays off quickly when you are comparing multiple loan options side by side. The key takeaway is that determining mortgage payment is straightforward once you understand the components, but the devil is in the escrow details and the loan structure. Run the numbers yourself before you trust a lender's initial quote, double-check the tax and insurance assumptions, and always look at the APR alongside the note rate. That process alone usually reveals discrepancies that can save you a few thousand dollars over the life of the loan.