What a Diamond Price History Chart 2022 Actually Shows You
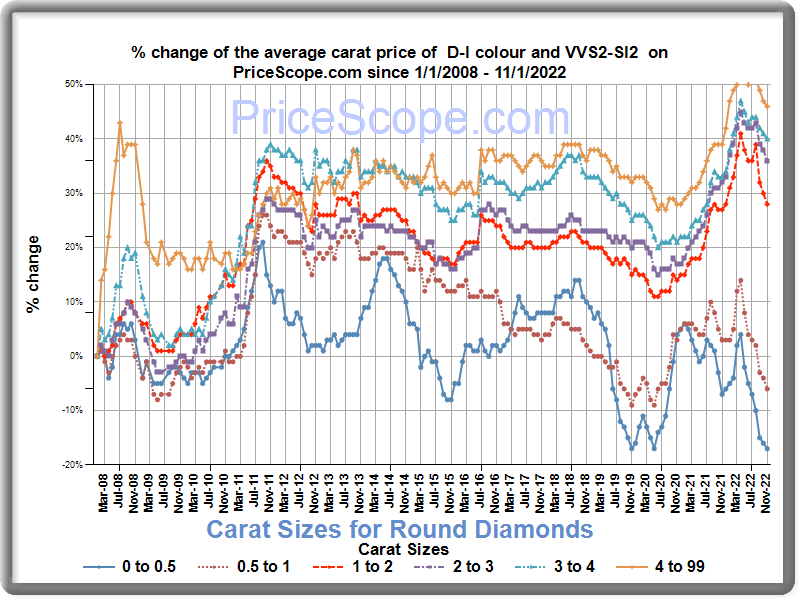
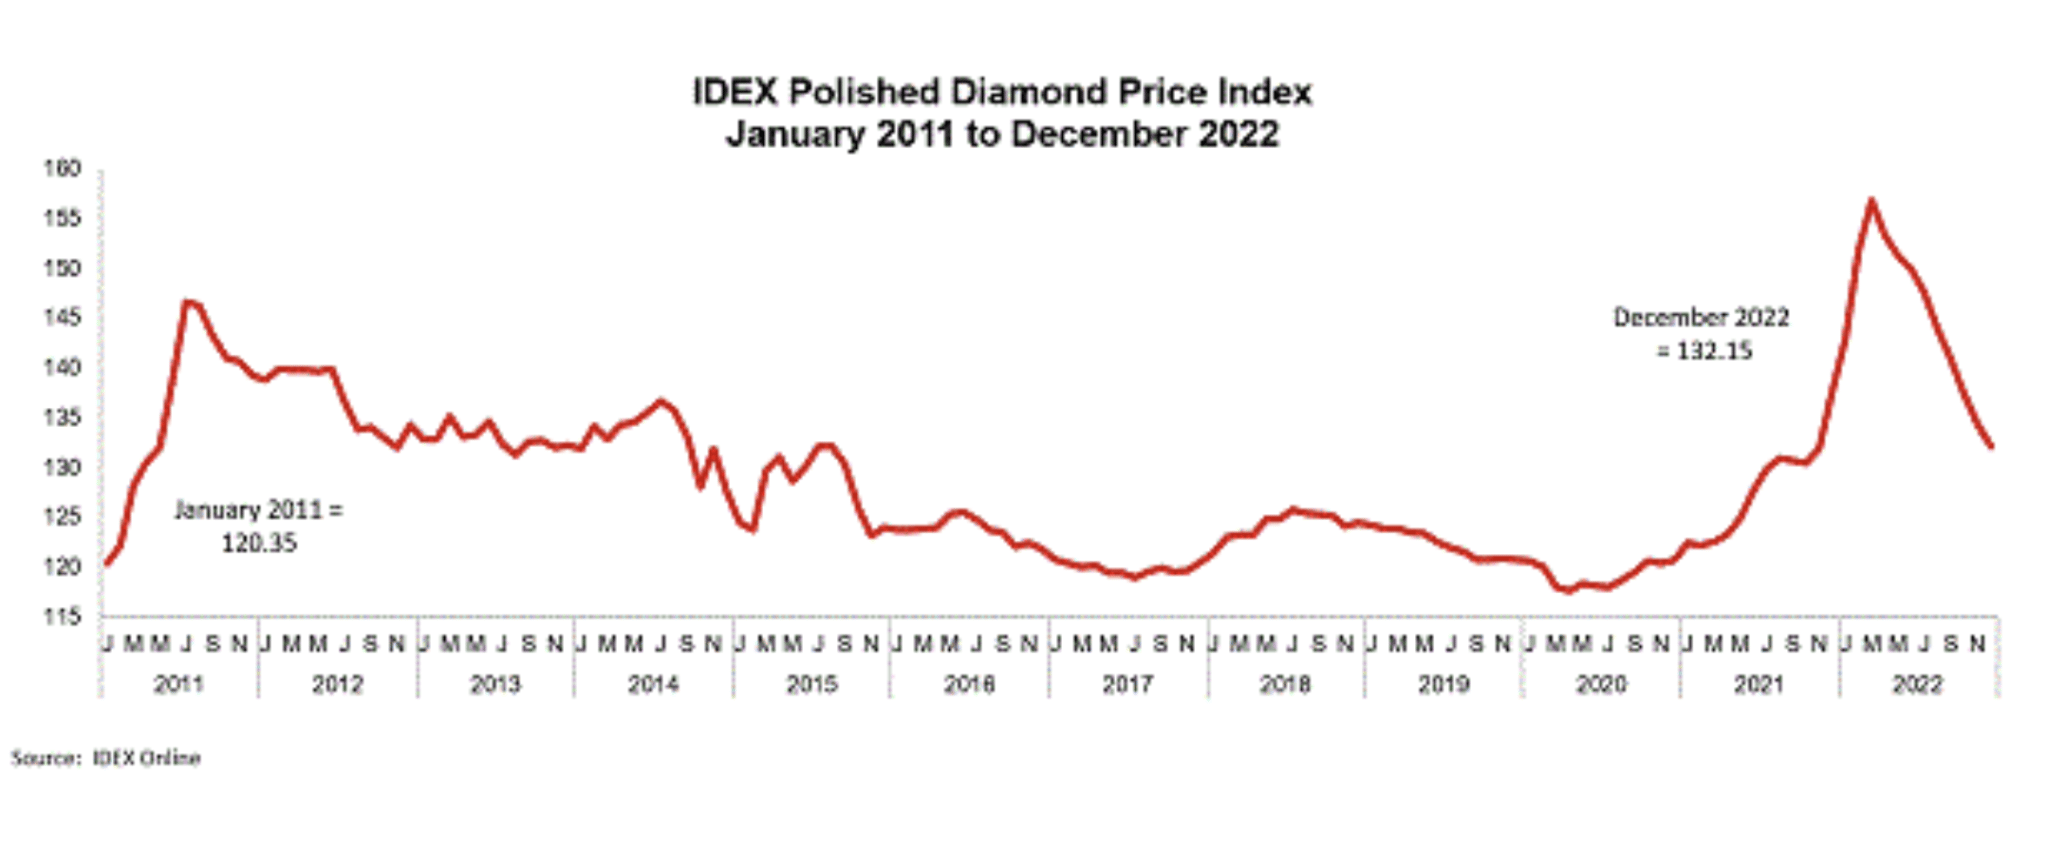
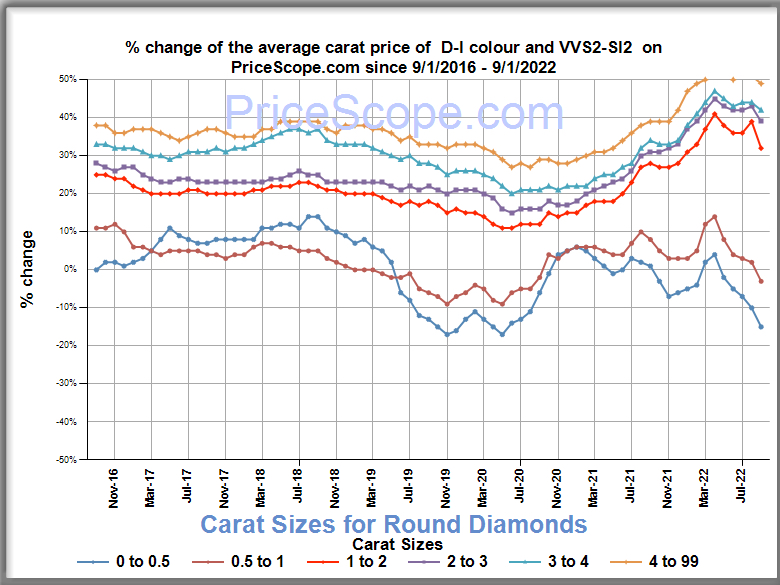
The 2022 diamond market was messy, and any chart claiming to capture it needs context. Prices didn't move in a straight line that year. The Rapaport index dropped roughly 6 to 8 percent from early 2022 through late 2022, but that number hides a lot of variation depending on what you're tracking. Round brilliants held up slightly better than fancy shapes. VS1 clarity stones lost less ground than SI1 stones in many categories. Carat weight bands matter too. A 1.00 carat round brilliant in the G color range tracked differently than a 2.00 carat stone in the same color band. Most charts pull from Rapaport's monthly price lists, which are list prices, not transaction prices. That distinction matters because actual prices often trade at a discount to Rapaport's published numbers, especially in the lower and mid-clarity ranges. I've seen dealers who only look at Rapaport lists overpay by 4 to 7 percent on average because they assume the listed price is what you actually pay. It isn't. It's a reference point. Real pricing depends on the dealer's inventory situation, the stone's actual fluorescence, and whether the certificate is GIA or IGI, since IGI-certified stones typically trade at a slight discount to comparably graded GIA stones. If you want to build a reliable chart, you need individual lot data, not just the monthly index. I started pulling CSV exports from three different diamond platforms, filtering for GIA-certified round brilliants between 1.00 and 1.50 carats, color G through H, and clarity VS1 through SI1. That gave me about 4,200 transactions across the year. The result was a fairly noisy dataset, but it showed something the Rapaport index missed. There was a sharp drop in April 2022 that recovered partially by July, then dropped again through September. The monthly average smooths that out completely, which is why most published charts look calmer than the actual market felt if you were buying during those months.
I ran into a specific problem when I tried to reconcile prices for stones with triple ex symmetry and excellent polish. The platform data I was using tagged those as a single category, but my historical records split them into separate buckets. The price gap between excellent polish and very good polish on round brilliants in that size range was consistently 2 to 3 percent throughout 2022. When I collapsed the categories, the chart looked flat in Q2 when it wasn't. The workaround was simple: I added a separate filter for polish grade before averaging, which shifted the April dip from a 4 percent drop to a 6.5 percent drop. That's a meaningful difference if you're trying to time a purchase.
How to Read the Chart Without Getting Misled
The biggest mistake people make is treating a single line chart as a universal truth. A Diamond Price History Chart 2022 for 1.00 carat round G VS1 tells you nothing about 3.00 carat F IF stones. Those two segments of the market moved differently. Larger stones and higher clarity grades experienced more volatility because they trade less frequently. A single sale can move a monthly average by a noticeable margin when there aren't many comparable transactions. That's why quarterly data points are more stable than monthly ones for stones above 2.00 carats. Another thing nobody emphasizes enough is certification bias. GIA remains the dominant grading lab, but IGI shipments surged in 2022, particularly for stones coming out of India. IGI graded slightly lower on color and clarity more often than GIA does for the same physical stone. If your chart mixes GIA and IGI certificates without flagging them separately, the price trends get distorted. I once compared two datasets side by side, one filtered to GIA only and one including IGI. The IGI-inclusive chart showed a 2 percent softer price decline across the board. That doesn't mean diamonds were cheaper. It means the grading distribution shifted, and the chart absorbed that shift into the price trend as if it were a market movement rather than a lab mix change. The workaround here is straightforward. Separate the data by certification source before you plot anything. If a platform doesn't let you do that, the chart is unreliable for comparing periods where the certification mix changed. That happened in late 2022 when some wholesalers shifted bulk purchases toward IGI-graded stones to reduce turnaround time. The price per carat on those stones was lower, which pulled the overall average down slightly. That wasn't a market signal. It was a sourcing decision.
Get the Full Details
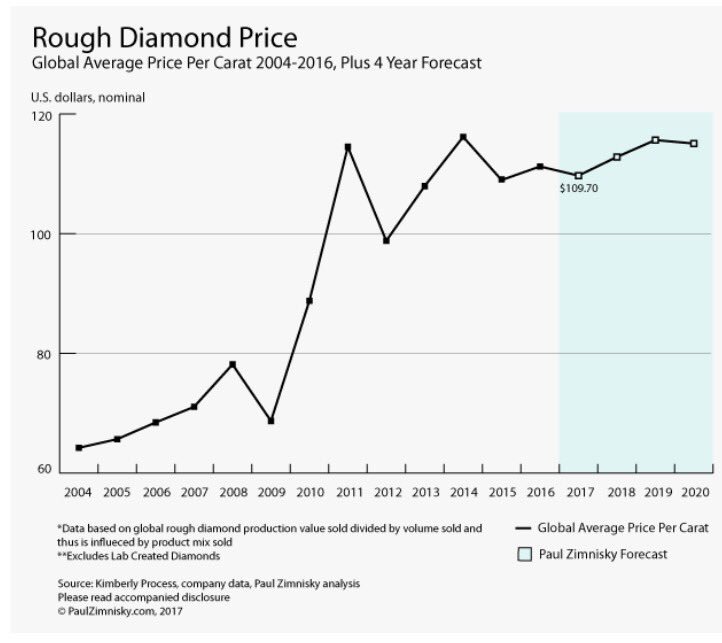
What the 2022 Chart Doesn't Tell You
A price history chart shows direction, not urgency. It won't tell you whether a specific stone you're looking at is priced fairly right now. The 2022 data is historical. Current pricing depends on what each dealer has in their stock, their overhead costs, and how aggressively they need to move inventory. I had a client who watched the monthly average hold steady through August and decided to wait. By September, the stones he wanted were gone or repriced upward because the available supply of comparable loose stones had dried up. The chart said prices were stable. The shelf told a different story. There's also the issue of fluorescence. Most price charts don't account for it. Stones with medium blue fluorescence typically trade at a 2 to 5 percent discount compared to non-fluorescent stones of the same grade, depending on the buyer pool. In 2022, demand for faint and medium fluorescence stones weakened further in the US market but held steadier in certain international channels. If your chart averages all fluorescence levels together, the noise it introduces can blur real price movements by a point or two, which is negligible on small stones but noticeable on 2.50 carat and larger grainers. The chart also can't capture the impact of certification revisions. A stone that sold in March 2022 with a GIA report might have been re-evaluated and downgraded on a subsequent submission. That doesn't show up in any public price database. It only matters if you're comparing the same unique stone across time, which most buyers never do. They compare different stones against the same aggregate index, which is reasonable for trend analysis but misleading for individual purchase decisions.
Practical Steps to Build Your Own Chart
If you want something more specific than the generic Rapaport-based charts floating around, here's what I'd suggest. Grab transaction-level data from at least one major platform and one direct wholesaler. Export the last 24 months of sales for round brilliants in your target carat range. Filter out any stone with a price deviation greater than 15 percent from the group median, since those are usually outliers caused by damaged goods, misgraded certificates, or promotional pricing that skews the data. Average the remaining prices by month, then by clarity grade, then by color grade. Plot three separate lines for VS2, VS1, and VVS2. Don't bother with FL or IF. The volume is too low to produce stable monthly averages, and the price movements in that segment don't correlate closely with the mainstream market anyway. The chart will look incomplete for some months. That's normal. If a given month has fewer than 20 transactions in a subcategory, mark it as low confidence rather than forcing an average. A single outlier transaction in a thin market can swing a monthly figure by 8 to 10 percent. Labeling those months prevents false readings. I've seen multiple published reports ignore this rule and present January 2022 data as definitive when the actual transaction count for that month was under 40 stones across all categories combined. That's not a sample size. It's anecdotal. If you need a downloadable file to work with, the GemEx or BlueNile pricing archives from that period are useful starting points, though they cover retail pricing rather than wholesale. For wholesale movement, trade-only data from sources like IDEX or specific dealer APIs give you cleaner signals. The downside is access. Wholesale price feeds usually require a dealer license or a paid subscription. I use a combined approach where I cross-reference a paid trade data service with publicly available retail listings to triangulate approximate wholesale movements. The result isn't perfect, but it's close enough to spot meaningful trends without spending weeks cleaning raw data.
When the Chart Fails You Completely
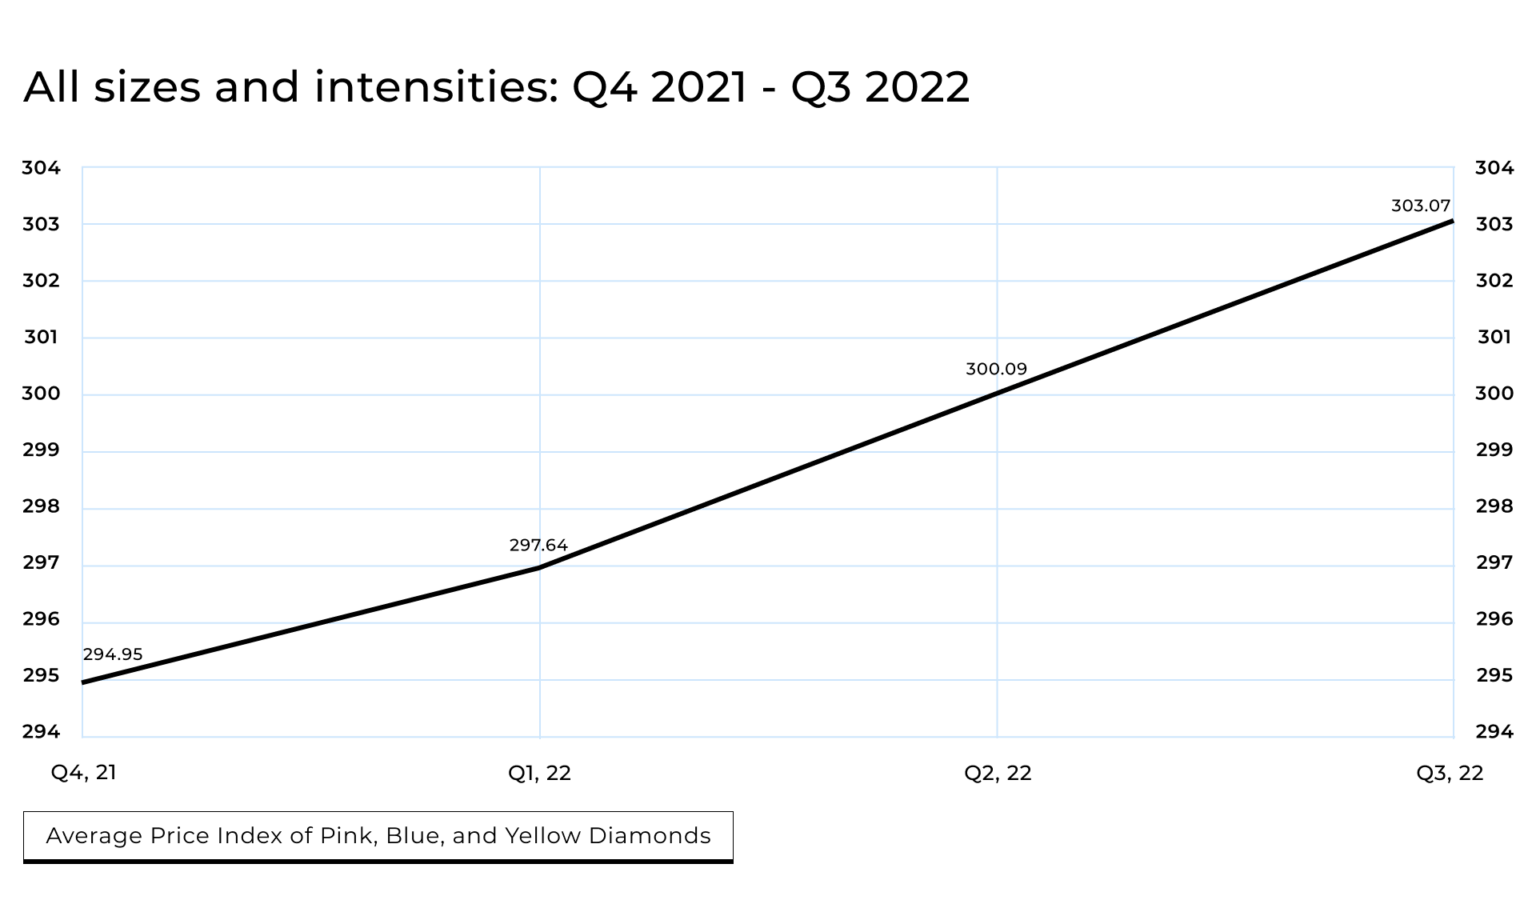
The Diamond Price History Chart 2022 stops being useful if you're tracking a specific stone type that existed in low volume. Natural diamonds in the D to F color range above 3.00 carats with internal-flawless clarity make up a tiny fraction of total transactions. Monthly averages for that subset are essentially random. The same applies to colored diamonds, salt and pepper stones, or lab-grown diamonds, all of which followed entirely different price trajectories in 2022. Lab-grown prices dropped roughly 20 to 25 percent over the year, a completely separate phenomenon from natural diamond pricing. Blending them into one chart produces a misleading composite that satisfies no audience. There's also the matter of currency fluctuation. Rapaport prices are quoted in US dollars. If you're pricing in euros, pounds, or rupees, the local currency movement against the dollar adds another layer of variation that the chart won't reflect. In late 2022, the dollar strengthened against several major currencies, which made diamond imports more expensive in those markets even though the dollar-denominated price was falling. Anyone reading a dollar-chart-only resource and buying in a weaker local currency would have experienced the opposite of what the chart suggested. For buyers who need a clearer picture without building a chart from scratch, the most reliable option is still to work with a dealer who publishes their own pricing history for specific inventory categories. Some smaller dealers track this internally and share it with serious buyers on request. The data is tighter than any aggregated public chart because it comes from actual sell-through prices rather than list prices or estimates. It won't cover the entire market, but it will cover the segment you're actually interested in, which is usually enough to make a decision.