Most people confuse these two fields because the job titles overlap
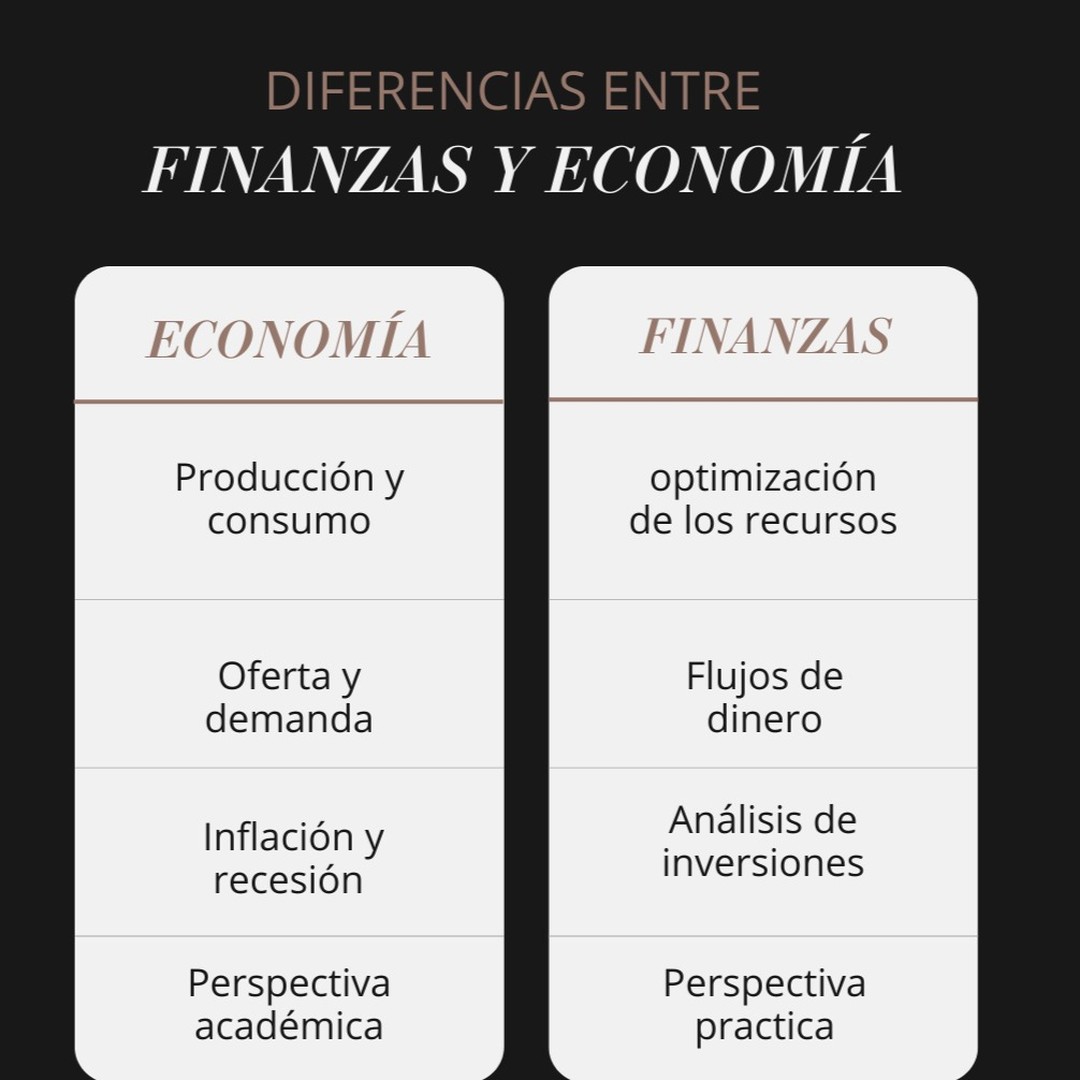
I spent seven years working at a mid-tier bank before moving into corporate finance, and I have watched more than a few colleagues mix up economics and finance to the point where it actually cost the company money. The core difference is not complicated, but the way the industry treats them makes the line blur in practice. Economics is the study of how societies allocate scarce resources. It looks at supply and demand at a macro level, how inflation moves, what drives employment numbers, and why countries grow or contract. Finance is the study of how individuals, companies, and governments manage money over time under conditions of uncertainty. Economics asks why the market moved. Finance asks how to position yourself relative to that movement. The academic separation came out of economics being rooted in social science and finance emerging from applied mathematics and accounting. That distinction mattered more fifty years ago than it does now. Modern economics programs teach financial modeling, and finance degrees require macro coursework. The crossover is real, and it is one reason people get confused.
Here is where the confusion becomes expensive. I once had a senior analyst on my team build a three-year revenue projection for a client based on GDP growth forecasts pulled from a macroeconomics paper. The math was correct. The model worked. The assumptions were wrong because gross domestic product growth in a specific sector does not map cleanly onto a single company's customer base. We lost the deal. The client's CFO called it amateur hour. She was right.
The practical distinction that actually matters
Economics deals with optimization under constraints. Finance deals with valuation under risk. These are related concepts but they require different toolkits. An economist uses econometric models, regression analysis, and large datasets to identify relationships between variables. A financier uses discounted cash flow models, option pricing theory, and portfolio theory to assign value to specific assets or decisions. One works with populations and aggregates. The other works with specific instruments and balance sheets. When you are trying to figure out whether interest rates will rise over the next twelve months, you are doing economics. When you are trying to decide whether to hedge a corporate bond position using interest rate swaps, you are doing finance. I remember running into this boundary issue at a pension fund I consulted for. They had hired an external economist to forecast long-term liability curves. The economist produced excellent work on demographic trends and inflation expectations. What they completely missed was the liquidity risk embedded in certain asset classes. The fund's liabilities were long-dated but the assets had hidden illiquidity premiums. The economist never built in a haircut for stress scenarios because that is not what the model was designed to do. Finance professionals would have flagged this immediately. I suggested we bring in someone with actuaries and fixed income traders to cross-check the economic assumptions against portfolio-level risk metrics. The adjustment cost us about forty thousand dollars in consulting fees but probably saved the fund from a twenty-million-dollar mismatch problem down the line.
Get the Full Details

Where the fields actually intersect in real work
Central bank policy decisions are economics until they hit your portfolio, then they become finance. A recession forecast is economics until you are deciding whether to issue debt or equity in that environment, then it is finance. Corporate earnings guidance involves both. You need economic context to understand the environment and financial rigor to model the cash flows. The counter-intuitive part that nobody teaches in intro courses is that economics is often better at explaining what happened than predicting what will happen. Finance professionals know this and build accordingly. We use scenario analysis and stress testing because the historical data economists love to analyze does not always repeat in useful ways. That is not a flaw in economics. It is just a fact about complex adaptive systems. A common pitfall I see beginners make is treating financial models as if they are more precise than the economic assumptions underneath them. You can build a perfectly formatted DCF model with twelve decimal places on every discount rate. If your terminal growth rate assumption is off by half a percentage point, the output is still garbage. Garbage in, beautiful spreadsheet out. It happens constantly.
What each field requires skill-wise
Economics training tends to emphasize statistical software, data interpretation, and causal inference. Finance training emphasizes accounting literacy, time value of money calculations, and risk management frameworks. The overlap is in quantitative skills. The divergence is in application. An economist might spend a week cleaning and analyzing a dataset on consumer spending patterns. A financier would spend that same week building a sensitivity table showing how a ten percent shift in consumer spending affects a company's debt service coverage ratio. Both approaches have blind spots. Economics can become so focused on theoretical elegance that it loses touch with operational reality. Finance can become so focused on numerical precision that it ignores structural changes in the environment. The best professionals I have worked with read both literatures and are honest about where their models fail. If you are trying to decide which path to take, the practical test is simple. Do you want to understand why economies grow and shrink, or do you want to figure out how to price assets within those economies. There is no right answer. Both fields pay well if you are competent. Most careers end up requiring a working knowledge of both regardless of which title you started with.