How to Actually Use a Dirt Bike Financing Calculator Without Overpaying
A dirt bike financing calculator is just a spreadsheet with a few formulas glued to it, but the difference between someone who pays 9% interest and someone who pays 12.5% often comes down to whether they actually understood what the calculator was telling them before they clicked submit. At its core, the tool takes three inputs — the purchase price, your down payment, and the loan term — and outputs a monthly payment based on an interest rate. That's it. The reason most people get tripped up isn't the math. It's that the inputs they're comfortable with are almost never the ones that produce the best outcome. I learned this the hard way back in 2019. I was buying a used 250cc Yamaha from a dealer who quoted me 11.9% for 36 months. The online calculator spat out $89 a month and looked fine on paper. But when I dug into the fine print, there was a $450 documentation fee rolled into the principal, a mandatory $12 a month credit insurance product, and a prepayment penalty if I paid it off early. The real rate was closer to 14%. The calculator didn't know about any of that because calculators don't talk to dealer paperwork. I walked away that day and bought the same bike two weeks later from a private seller with cash. Saved about $1,400 total over the life of the loan I would've taken.
The Math Behind the Numbers
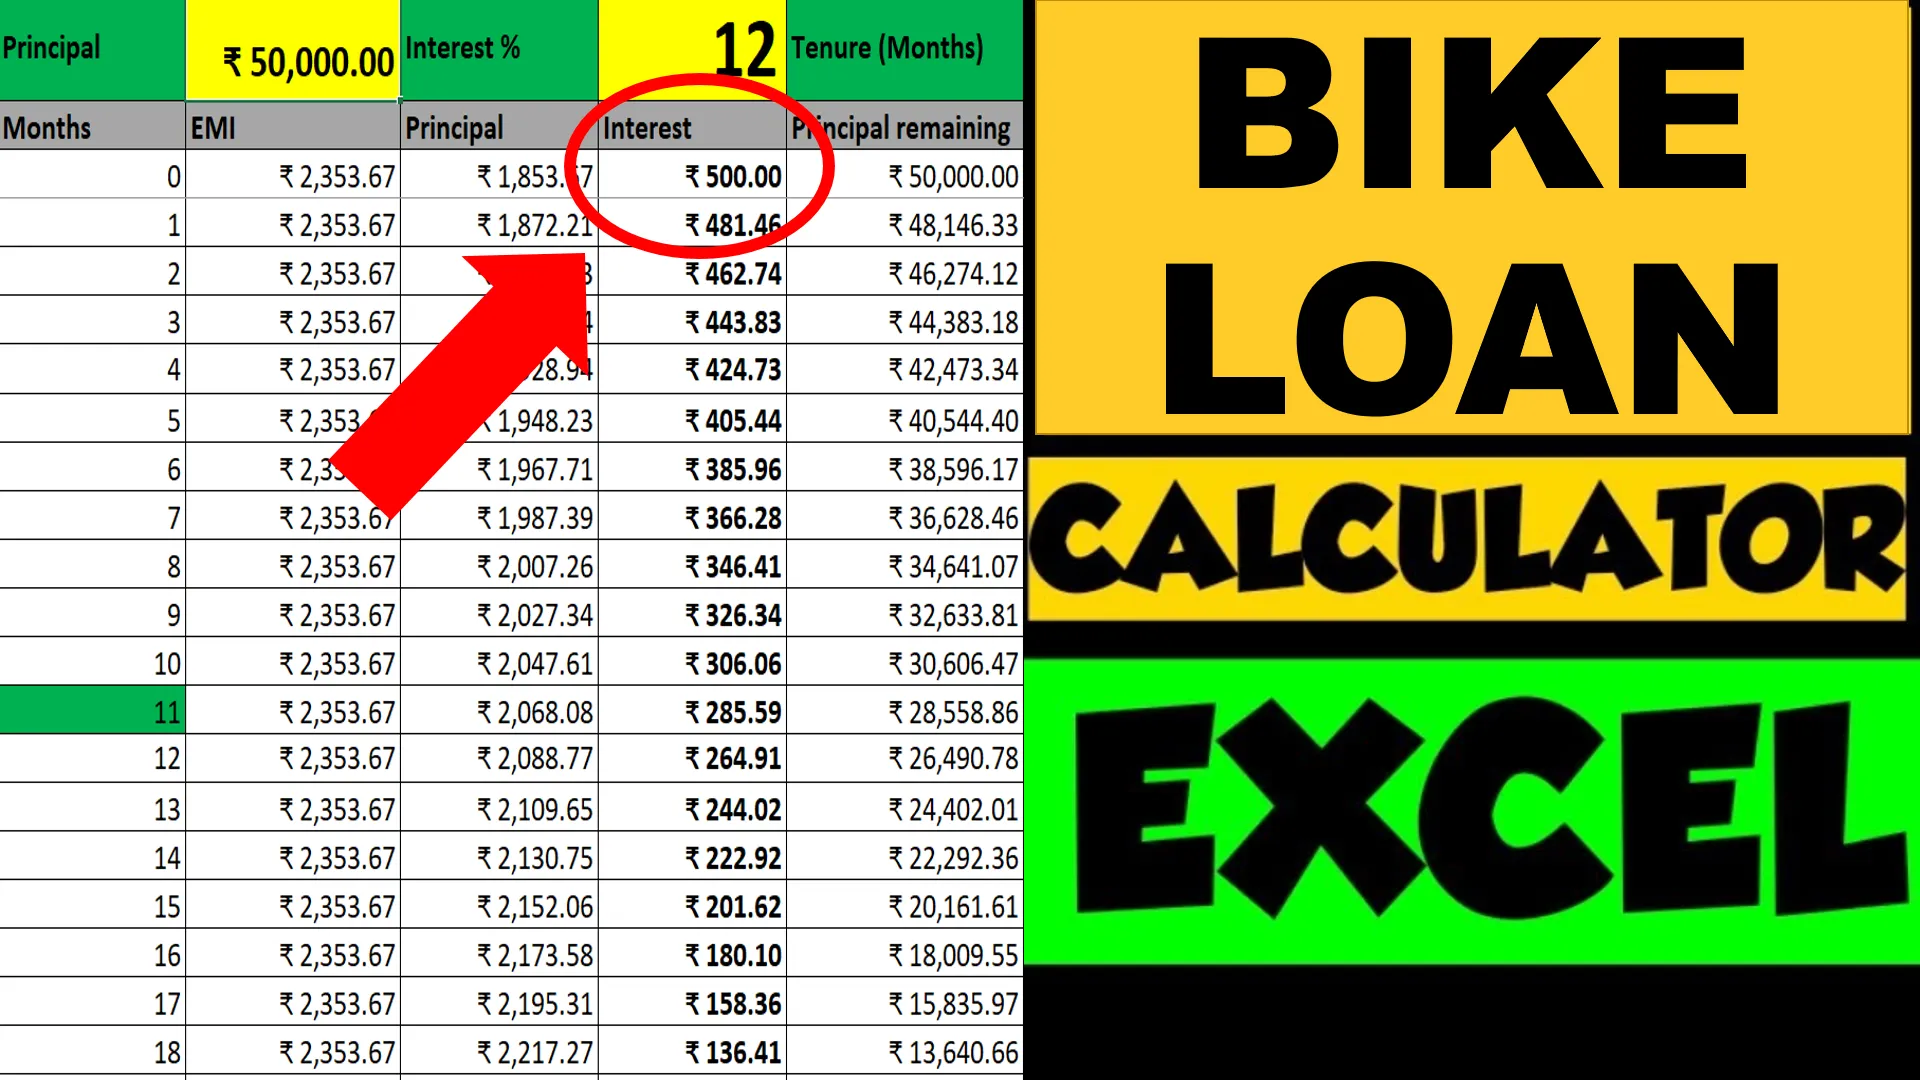
The standard amortization formula looks like this: M = P × [r(1+r)^n] / [(1+r)^n - 1]. P is your principal amount. r is your monthly interest rate (annual rate divided by 12). n is the number of months. Most people just plug numbers into a web calculator and move on, but understanding how the pieces move helps you spot when something is wrong. Here's the thing nobody tells you about that formula: in the first 12 months of a typical dirt bike loan, roughly 60 to 70 percent of your payment goes entirely toward interest. The principal barely budges. If you make a $200 extra payment in month three, you're not just paying down $200 of balance. You're reshaping the entire amortization curve and saving maybe $180 to $250 in total interest depending on your rate and term. That's the part the basic calculators don't show unless they have an extra payment field. Another thing to understand is how rate tiers work. A $3,000 dirt bike loan and a $12,000 dirt bike loan often carry different rates even with identical credit scores. Lenders treat anything over $7,500 as a different risk category. If you're financing a high-end factory 450 or a side-by-side, breaking the purchase into two transactions — one under the threshold, one over — sometimes gets you a better blended rate. Don't do this without checking the lender's policy first. Some explicitly prohibit it and call itFraudulent structure. But it's worth asking.
Setting Up Your Own Calculator
You can build a functional Dirt Bike Financing Calculator in Google Sheets or Excel in about eight minutes. Set up columns for purchase price, down payment, trade-in value, loan term in months, annual interest rate, and any fees. In the monthly payment cell, enter the PMT function: =PMT(rate/12, nper, -PV). Rate is the annual rate divided by 12. Nper is the number of payments. PV is the loan amount after subtracting down payment and trade-in but adding any rolled-in fees. To make it actually useful, add an amortization schedule below. Column A is the payment number. Column B pulls the principal portion with =PPMT(rate/12, row_number, nper, -PV). Column C pulls the interest portion with =IPMT(rate/12, row_number, nper, -PV). Column D tracks remaining balance. This takes you from a single number to a full picture of where every dollar goes month by month. I keep one of these sheets open every time I shop for a bike. When a dealer gives me a quote, I type their numbers into my sheet and compare them side by side. If their monthly payment matches mine but their total interest is $600 higher, I know there are hidden fees inflating the principal. If their payment is lower but the term is 60 months instead of 36, I know they're selling me time, not savings.
Get the Full Details

Common Mistakes That Cost Money
The biggest mistake I see is people locking in the longest term available. A 60-month loan on a $5,000 dirt bike at 10.9% looks attractive at $103 a month. But you'll pay $1,176 in interest over the life of the loan. The same loan at 36 months comes to $161 a month with $808 in interest. That's $368 more per month for $368 less in total cost. Mathematically identical. Psychologically very different. Another mistake is treating the advertised rate as the rate you'll get. The 5.9% rate on the brochure is for prime borrowers with 740+ credit scores and a 20 percent down payment. If your score is in the 620 range, expect the offer to land between 11% and 16%. That gap is where dealers make their margin. Call three lenders before you walk into a dealership. Credit unions usually beat dealer financing by 2 to 4 percentage points on motorcycle and ATV loans. There's also the gap insurance question. If you finance a brand new 450cc bike for $11,000 and total it within the first year, you'll owe the lender $9,200 but the bike is only worth $8,500 on the used market. Gap insurance covers that $700 difference. It costs about $100 to $200 added to the loan. Whether it's worth it depends on how long your term is and how fast the bike depreciates. Dirt bikes lose roughly 15 to 20 percent of their value in year one. That's steeper than cars. Gap insurance is more relevant here than it is for a Honda Civic loan.
When a Calculator Won't Help You
No calculator can account for a lender's hidden add-ons, a dealer's inflated bike price, or the fact that your credit score might drop three points between when you check the rate and when you actually sign. Also, calculators don't know about state-specific taxes. In some states, sales tax is calculated on the full purchase price before your down payment. In others, it's calculated after. That single difference can swing your monthly payment by $15 to $30 and your total cost by $100 to $200 over the loan life. If you're in a state where the tax calculation favors you, make sure the dealer isn't using the other method. Ask them to show you the tax line on the worksheet before you sign anything. Most will comply because they want the sale. If they hesitate, that's a red flag. One edge case I ran into recently: financing a bike that needs $2,000 in immediate repairs. The loan calculator said $149 a month and felt manageable. But that $149 was based on a $6,000 bike price that needed immediate work. I ended up making minimum payments on the loan while also spending $2,000 out of pocket on repairs, which meant I couldn't make extra principal payments for six months. The calculator never knew about the repairs. It only saw the bike price. I should've included the repair cost in the principal or waited until I had the cash on hand.
There are also situations where a calculator gives you a number but the real constraint is cash flow, not total cost. If a 48-month loan at 13% keeps you from missing rent, it's the right choice even though a 24-month loan at the same rate would save you money. The calculator can show you both scenarios. It can't tell you which one fits your actual bank account. That part is on you.
What to Do Before You Commit
Get pre-approved by a credit union or online lender before you walk onto the lot. This gives you a benchmark rate to compare against the dealer's offer. If the dealer beats it, fine. If they don't, you walk away with your pre-approval in hand and shop elsewhere. This single step saves people an average of 1.5 to 3 percentage points on their rate, which on a $7,000 bike over 36 months is roughly $280 to $560 in interest savings. Put at least 10 percent down if you can. Every dollar you don't put down is a dollar that accrues interest for the entire loan term. On a 36-month loan at 11%, that's about $30 to $40 in extra interest per $100 you finance instead of paying upfront. Small numbers individually. Not small when you're looking at a $3,000 to $5,000 down payment gap. Read the prepayment terms. Some lenders charge a fee if you pay off the loan early. Others don't. If there's an early payoff fee, factor it into your decision to accelerate payments. A $150 prepayment penalty on a loan where you'd save $400 in interest still leaves you $250 ahead. But if the penalty is 3 percent of the remaining balance, it can wipe out the savings entirely on a short-term loan.
The Dirt Bike Financing Calculator is a starting point, not a finish line. It tells you what a loan looks like on paper. The real work is in the paperwork that comes after.