How Mortgage Discount Points Actually Work
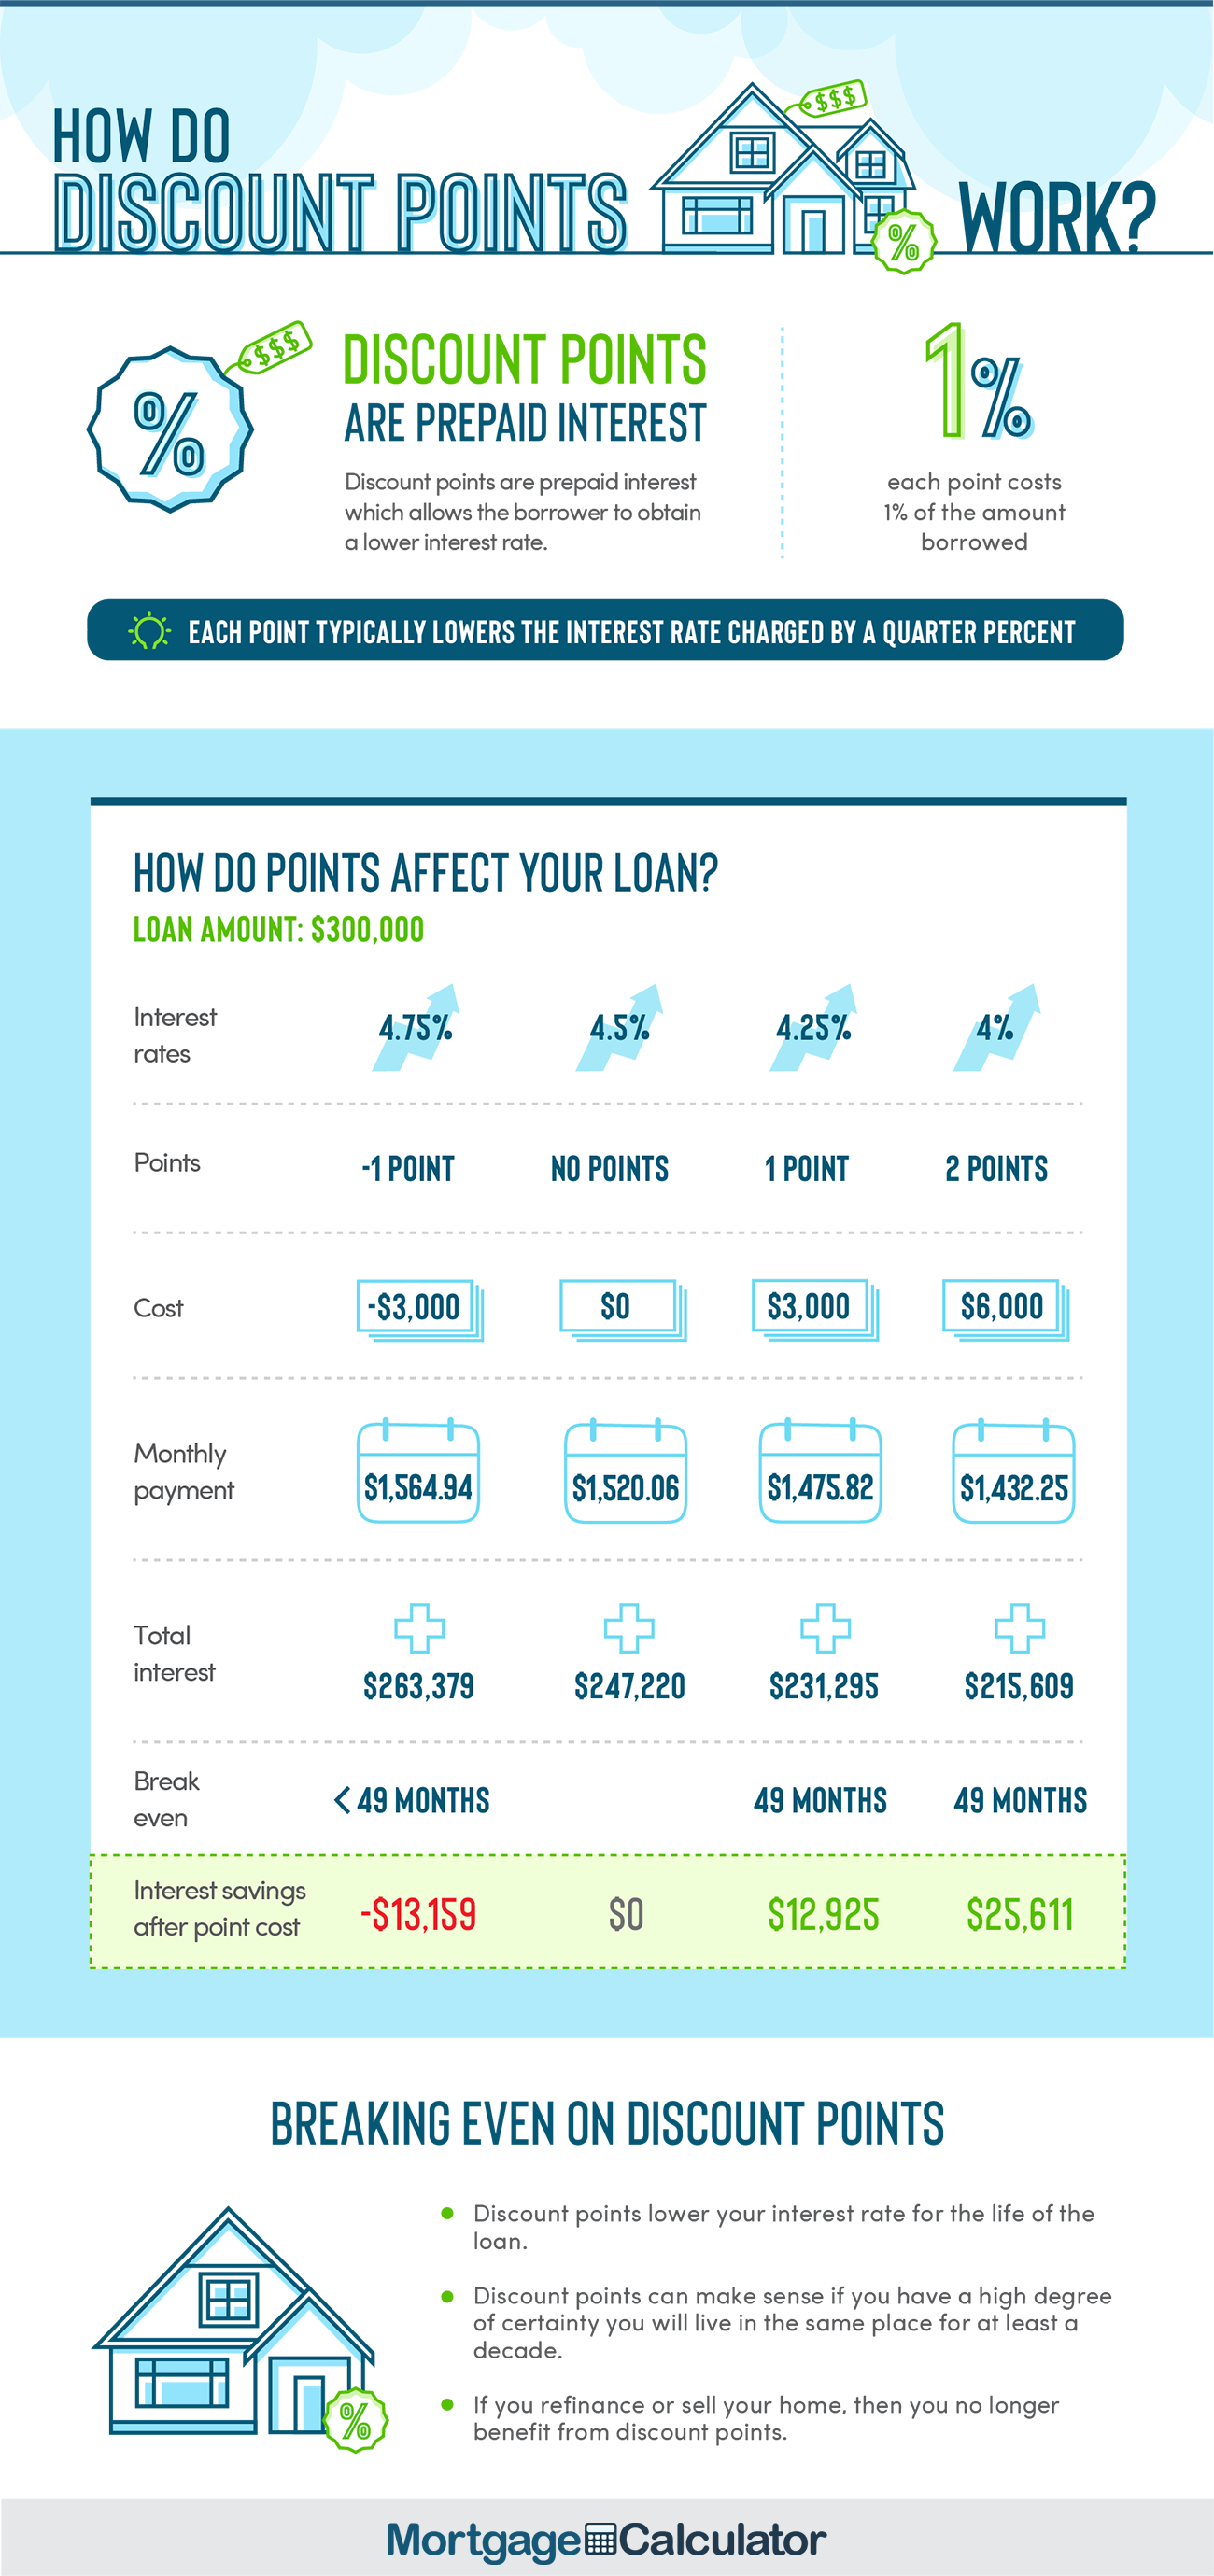
You pay upfront to lower your rate. That's the whole idea, but the math behind it is messier than most people expect. Discount points are each equal to 1% of your loan amount, and each one typically buys you 0.25 percentage points off your interest rate. A $400,000 loan with one point costs you $4,000 at closing. Two points cost $8,000. The rate drops from whatever the lender is offering by half a percent. Simple enough on paper. The real confusion starts when you try to figure out whether it's worth it. That's where Discount Points Calculation comes in, and it's not as straightforward as dividing your monthly savings by your upfront cost and calling it done. I learned that the hard way about four years ago on a refinance I was running for a client who wanted to stay under a 6% rate with minimal out-of-pocket at closing.
Running the Discount Points Calculation Correctly
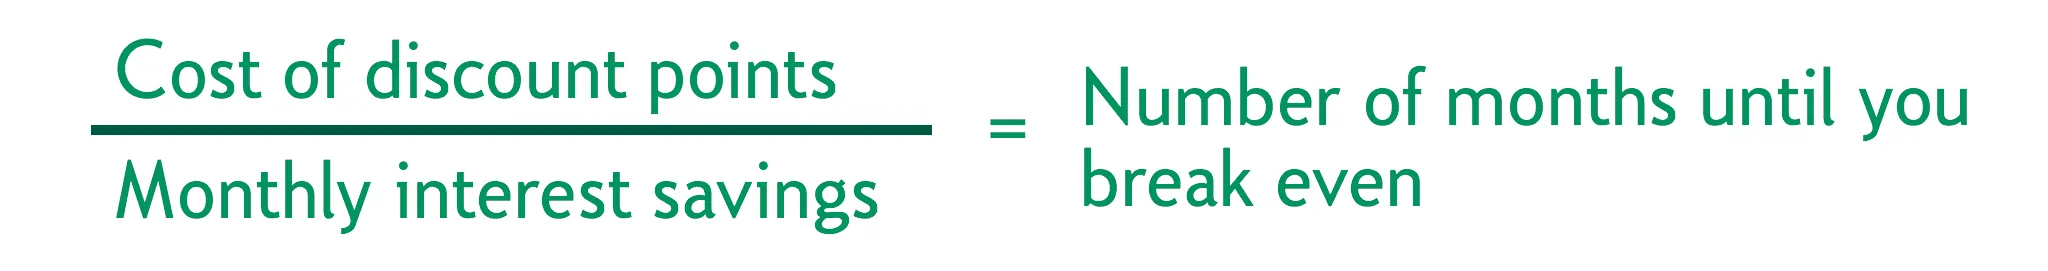
Start with your loan amount, the number of points you're considering, and the lender's stated rate reduction per point. Multiply the points by 1% of the loan to get your upfront cost. Then recalculate your monthly payment at the new rate and compare it to the payment at the original rate. The difference is your monthly savings. Divide the upfront cost by the monthly savings and you get your breakeven in months. Here's the part nobody tells you: the rate reduction isn't always exactly 0.25% per point. It varies by lender, by market conditions, and sometimes by how much you're borrowing. I had a situation where a big national lender was offering only 0.125% off per point on a jumbo loan, while a local credit union was giving 0.375% off on the same loan size. That's a massive difference in the math. The national lender's price looked better on the surface because their base rate was lower, but once you factor in how few basis points each point actually bought, the credit union won out. Let me walk through a concrete example. You're looking at a $400,000 conforming loan at 6.5% over 30 years. The lender offers 1 point for 0.25% off. One point costs $4,000. Your new rate would be 6.25%. At 6.5%, your monthly payment is $2,528.27. At 6.25%, your monthly payment is $2,464.17. That's a monthly savings of $64.10. Your breakeven is $4,000 divided by $64.10, which equals about 62.4 months. So you'd need to stay in the home for roughly five years and two months just to recover what you paid for the points.
Now here's where people go wrong. They look at the breakeven and say five years is fine, I'll stay longer, buy the points. But they forget to run a second calculation: total interest paid over the life of the loan with and without points. At 6.5% with no points, you pay $510,178 in interest. At 6.25% with one point, you pay $487,102 in interest plus the $4,000 you paid upfront, totaling $491,102. The total savings is $19,076. But if you sell or refinance before the breakeven point, you've actually lost money. The points are gone, and the lower rate never compensated for the upfront cost. I encountered a specific edge case that almost cost me a client relationship. A borrower wanted to roll the discount points into the loan balance instead of paying them at closing. On the surface this seems like free money — no out-of-pocket cost. But rolling $4,000 of points into a $400,000 loan means you're now paying interest on that $4,000 for the entire loan term. At 6.25% over 30 years, that extra $4,000 in principal costs an additional $945 in interest. So the real cost of those points isn't $4,000, it's $4,945. The breakeven shifts from 62 months to about 77 months. That's a full year and a half longer just because the points were financed instead of paid cash. Most borrowers don't realize this distinction, and most loan officers don't clarify it either. There's also the tax angle. Discount points are generally tax-deductible in the year you pay them if you're buying a primary home and the points meet certain IRS criteria. This changes the effective cost of points considerably. If you're in the 24% tax bracket, one point on a $400,000 loan effectively costs you $3,040 after the deduction, not $4,000. That shifts your breakeven from 62 months to about 47 months. But this only applies if you itemize deductions, and the TCJA raised the standard deduction enough that a lot of people no longer qualify. You need to run both scenarios before you assume the tax benefit is there.
Get the Full Details
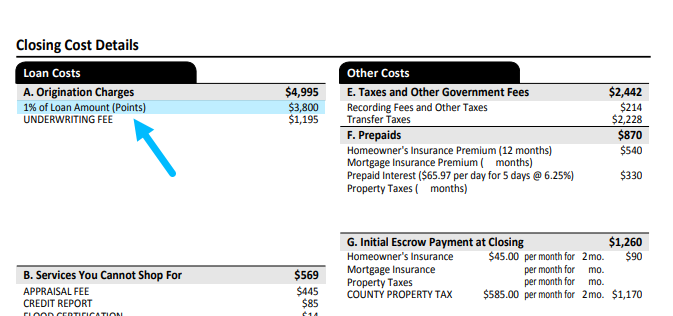
Another thing that trips people up: not everything a lender calls a "point" is actually a discount point. Origination fees, processing fees, and underwriting charges sometimes get labeled as points on the Loan Estimate form. Those fees don't buy you a rate reduction. They're just fees. The only way to tell the difference is to look at Section A of the Loan Estimate under "Origination Charges." Discount points should be listed separately from origination charges. If they're bundled together, ask the lender to break it out. I had to do this on a deal where the broker was charging 1.5 points but only reducing the rate by 0.25%, which meant one of those points was just an origination fee disguised as a discount point. The borrower saved nothing extra for that middle point. So when you're running your Discount Points Calculation, the practical approach is to get two numbers from the lender: the exact rate with and without the points, and a clear breakdown of what portion of your closing costs are actual discount points versus other fees. Then compute the monthly savings, the breakeven period, the total interest difference, and factor in your tax situation and how long you realistically plan to hold the loan. If the breakeven is longer than your planned ownership period, the points are a net loss regardless of what the marketing materials say. The calculator on the lender's website might show savings, but it won't tell you whether those savings matter for your specific timeline.