How Discount Points Actually Affect Your Monthly Payment
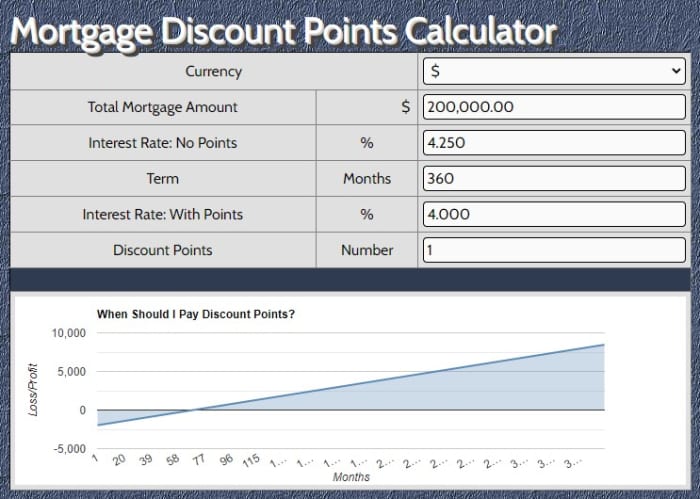
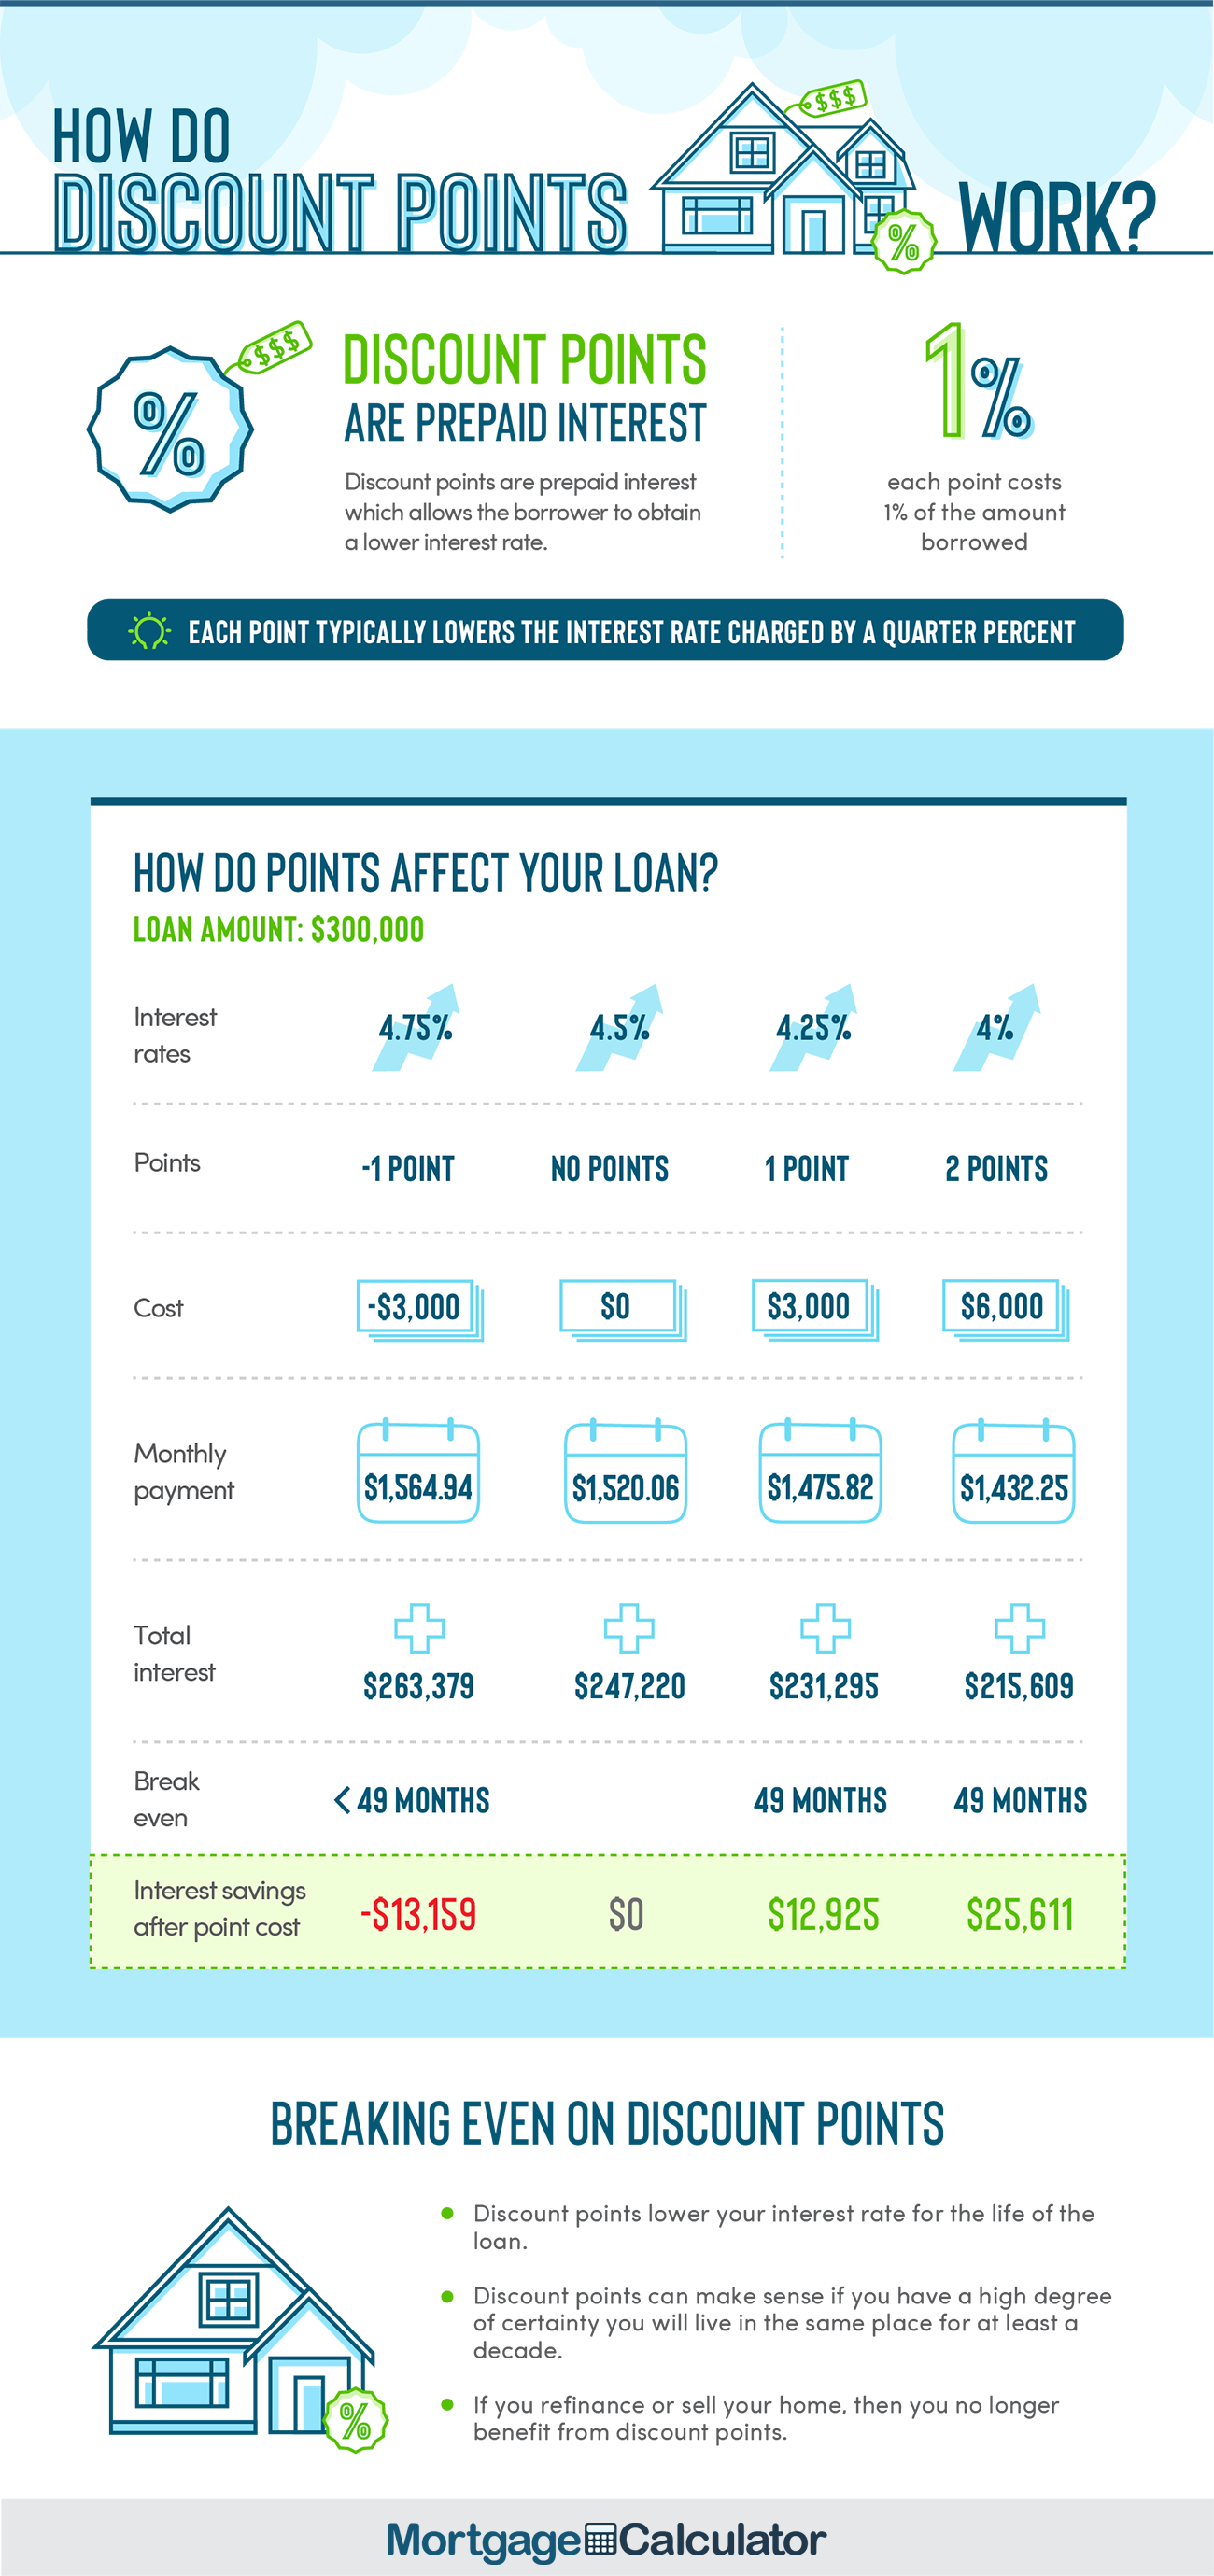
Points are paid upfront to lower your interest rate. One point equals 1% of the loan amount. You buy them to reduce monthly payments, not to save money in the short term. Most people get confused about which is which. Here is the math. The calculator takes your loan amount, current rate, and the number of points you want to buy, then shows the new rate and monthly payment. Simple enough. But the real value is in the breakeven analysis. To find breakeven yourself, divide the total cost of the points by your monthly savings. Say you are taking a $400,000 loan. One point costs $4,000. Without points you get 6.75%. With one point you get 6.5%. Your payment drops from about $2,592 to $2,531. That is a $61 monthly difference. Divide $4,000 by $61 and you get roughly 66 months. You need to stay in the home for over five years just to get your money back. After that, every month is pure savings.
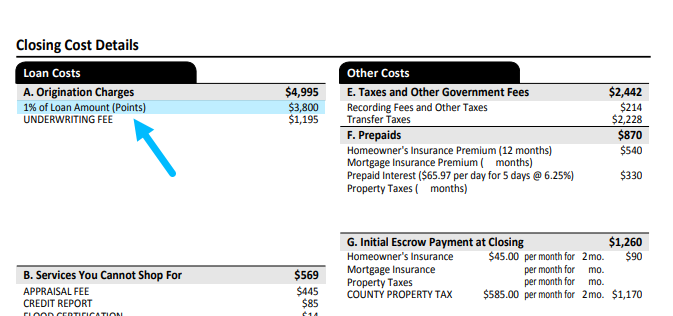
Things get messier than the basic math suggests. Points are usually sold in quarter-point increments, so you might see 0.25, 0.5, or 0.75 available at a given rate. Lenders price these differently, and the rate reduction per point is not linear. Buying two points might drop your rate by 0.5%, not 0.4%. Always check the actual numbers the lender quotes, not the formulaic expectation. I ran into this exact problem last year with a borrower who was comparing two different lenders. Lender A offered 0.375 points for a 0.375% rate drop. Lender B offered 0.5 points for the same 0.375% drop. The calculator showed Lender A as the better deal on paper, but Lender B was including origination fees in that point count while Lender A kept them separate. By the time I pulled the full loan estimate, the effective cost was nearly identical. The lesson is that any calculator showing points in isolation is only showing part of the picture. You need the full rate quote with all fees folded in before the math means anything. Another thing most people miss is the tax treatment. Points are generally deductible as mortgage interest in the year paid, but only if you itemize. Since the standard deduction went to $14,600 for single filers and $29,200 for married filing jointly in 2024, a lot of borrowers no longer benefit from the deduction at all. The points still lower your rate, but the tax savings that used to offset the upfront cost are gone for many people. Run the breakeven without assuming a tax benefit, and you will get a more honest answer about whether buying points makes sense for your situation.
There is also the question of refinancing. If you already bought points on your original loan and then refinance, those old points cannot be deducted all at once again. They are amortized over the remaining life of the original loan. Some calculators do not factor this in, which can make a refinance look cheaper on paper than it actually is when you consider the lost deduction. The bottom line is practical. Buy points if you plan to stay in the home for at least seven years, you itemize deductions, and the lender is offering a genuine rate reduction that is clearly priced. Skip them if you are moving in five years or fewer, if you take the standard deduction, or if the rate drop per point is unusually small. In those cases the upfront cost just sits there doing nothing until you sell. If you are comparing offers from multiple lenders, run each one through the same calculator using identical assumptions. Loan amount, term, and credit score should be the same across every comparison. The only thing that should change is the rate and points. Anything else, like different closing cost structures or varying mortgage insurance requirements, belongs in a separate calculation entirely.
Get the Full Details